

Key Highlights
- A sign-on bonus is a one-time financial incentive offered by employers to attract new hires, especially in competitive job markets.
- Sign-on bonuses help compensate for lower salaries and encourage quicker acceptance of job offers.
- In 2026, approximately 3% of U.S. job listings included sign-on bonuses, up from 1.8% in 2019, indicating their ongoing relevance.
- Taxation on sign-on bonuses includes federal withholding (22%), state taxes (10.23% in California), and FICA charges (7.65%), potentially leading to over 41% withheld from the bonus.
- Understanding tax implications is crucial for families, as it affects the net amount received and overall financial planning.
- Employers can use either the aggregate method or the percentage method for taxing bonuses, impacting the amount withheld and take-home pay.
- Strategies to minimise taxes on bonuses include contributing to retirement accounts, utilising Flexible Spending Accounts (FSAs), making charitable donations, and discussing withholding options with employers.
- Proactive financial planning can help families manage tax burdens and invest in long-term goals, such as education funding.
Introduction
Imagine landing a new job with a sign-on bonus, but feeling confused about how it affects your family’s finances. Understanding the intricacies of a sign-on bonus can be overwhelming for parents navigating new job opportunities. Many parents feel lost when it comes to understanding how taxes affect their bonuses. This guide will help you navigate these challenges, ensuring you make the most of your financial opportunities. Together, we can explore the essential aspects of sign-on bonuses, offering insights and strategies to help you make informed decisions that align with your family’s financial goals.
Define Sign-On Bonuses and Their Purpose
Imagine receiving a financial boost just as you start a new job – sounds appealing, right? A sign-on incentive, commonly known as a sign-on bonus after taxes, is a one-time financial benefit that employers offer to attract new hires. This payment typically comes when you begin your new role and serves several important purposes:
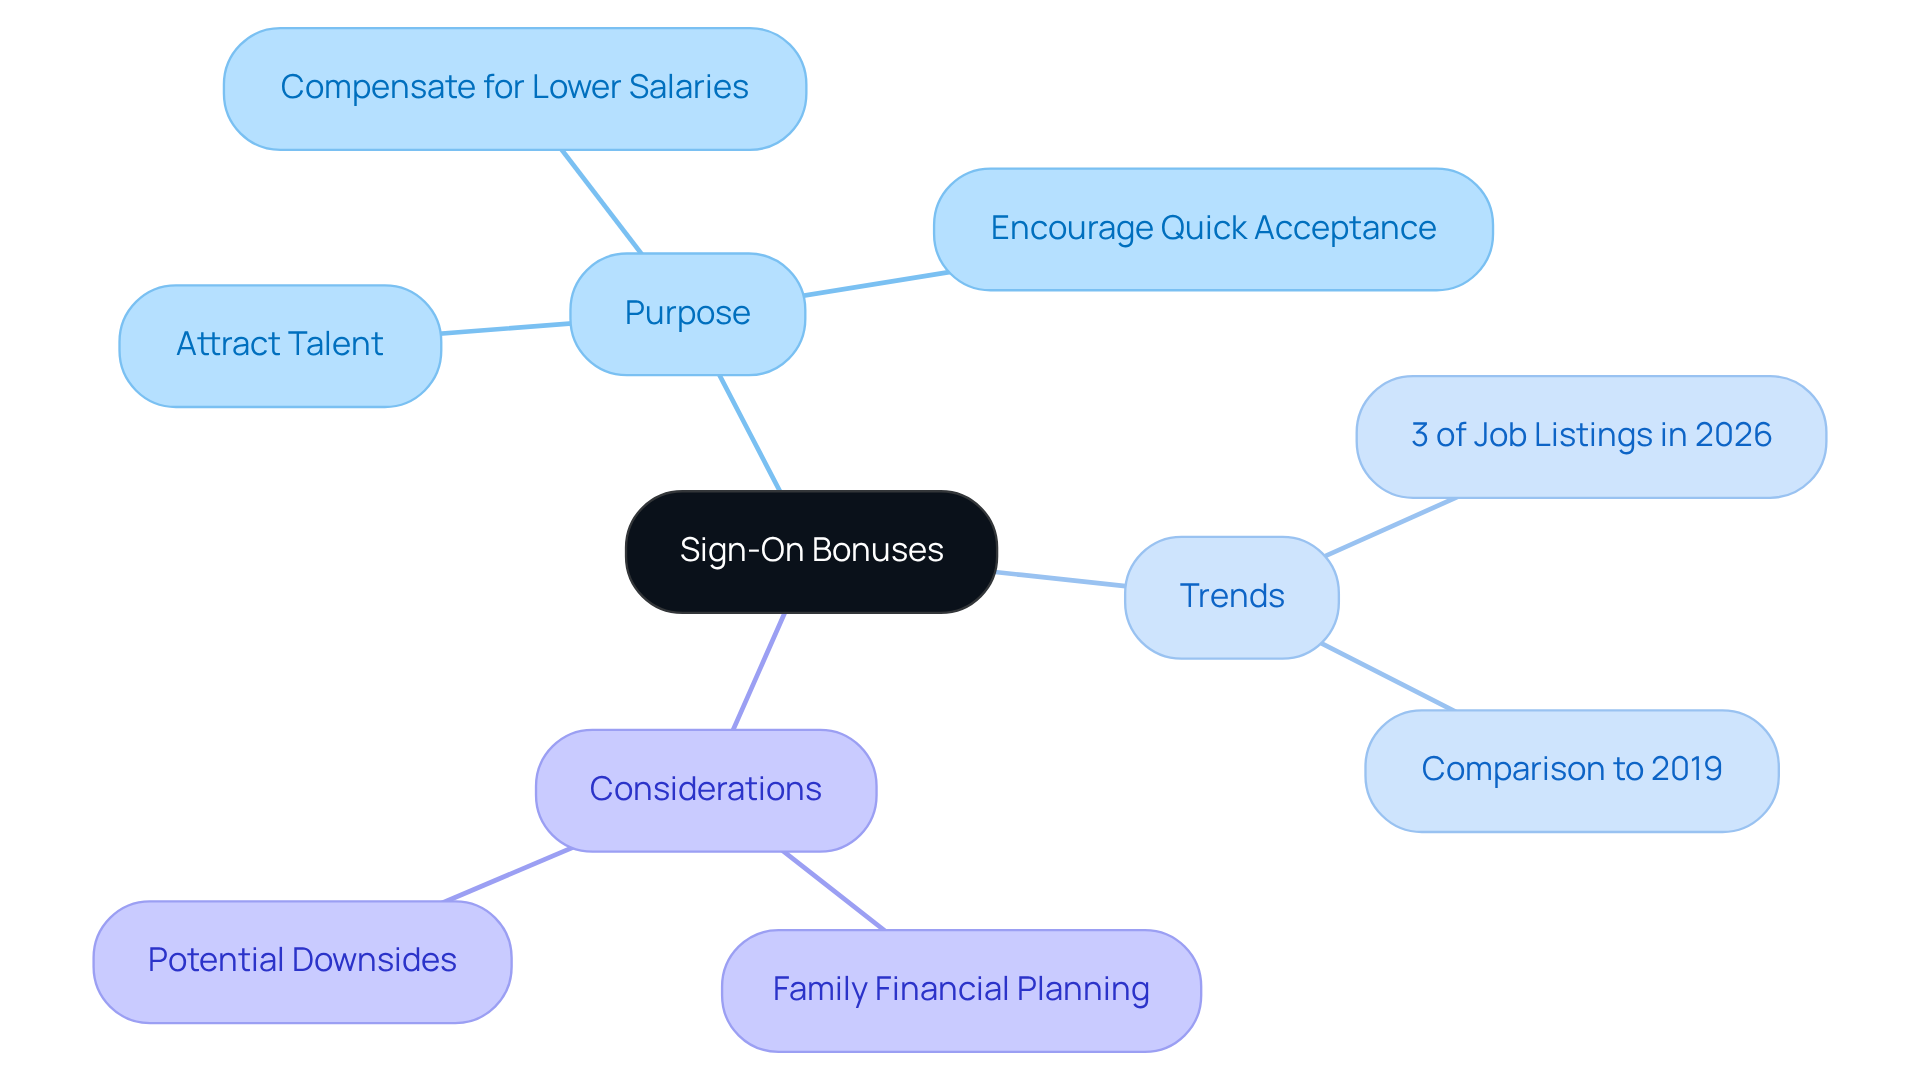
- Attract Talent: In competitive job markets, companies use sign-on bonuses to entice candidates who might be considering multiple offers. This strategy works especially well in sectors facing labor shortages, where skilled professionals are in high demand.
- Compensate for Lower Salaries: Sometimes, employers offer these incentives to make up for a lower base salary or to offset benefits that a new hire might lose by leaving their previous job. This helps make the overall compensation package more appealing.
- Encourage Quick Acceptance: By providing a financial incentive, employers hope to motivate candidates to accept job offers more quickly, which can shorten the hiring process.
In 2026, about 3% of job listings in the U.S. included a sign-on incentive. While this number has decreased from previous years, it remains significantly higher than the 2019 average of 1.8%. This trend highlights the ongoing importance of sign-on incentives in attracting talent, particularly in high-demand fields like healthcare and technology.
Many parents feel overwhelmed when evaluating job offers, especially when financial incentives are involved. A well-negotiated sign-on bonus after taxes can greatly influence budgeting and career choices, making it essential for families to consider how these incentives align with their long-term financial goals. For instance, families like Allison and Brian, who sought advice from Bright Advisers, learned how to enhance their economic potential through strategic tax planning. They discovered that incorporating tax optimization into their financial plans not only minimized their tax liabilities but also secured their children’s future through education funding. This thoughtful planning gave them peace of mind, allowing them to cherish more moments with their family.
However, it’s also important to be aware of potential downsides. The normalization of sign-on incentives can lead to increased costs for employers and possible resentment among employees who don’t receive them. Keeping this balanced perspective in mind can help young parents navigate their career choices more effectively. Understanding these incentives can empower you to make choices that benefit your family’s future.
Explain Taxation of Sign-On Bonuses
Imagine receiving a sign on bonus after taxes that feels like a financial boost, only to discover how much is deducted. The IRS categorizes a sign on bonus after taxes as additional earnings, which means they’re subject to various levies, including federal, state, and payroll charges. Here’s a gentle breakdown of how these bonuses are typically taxed:
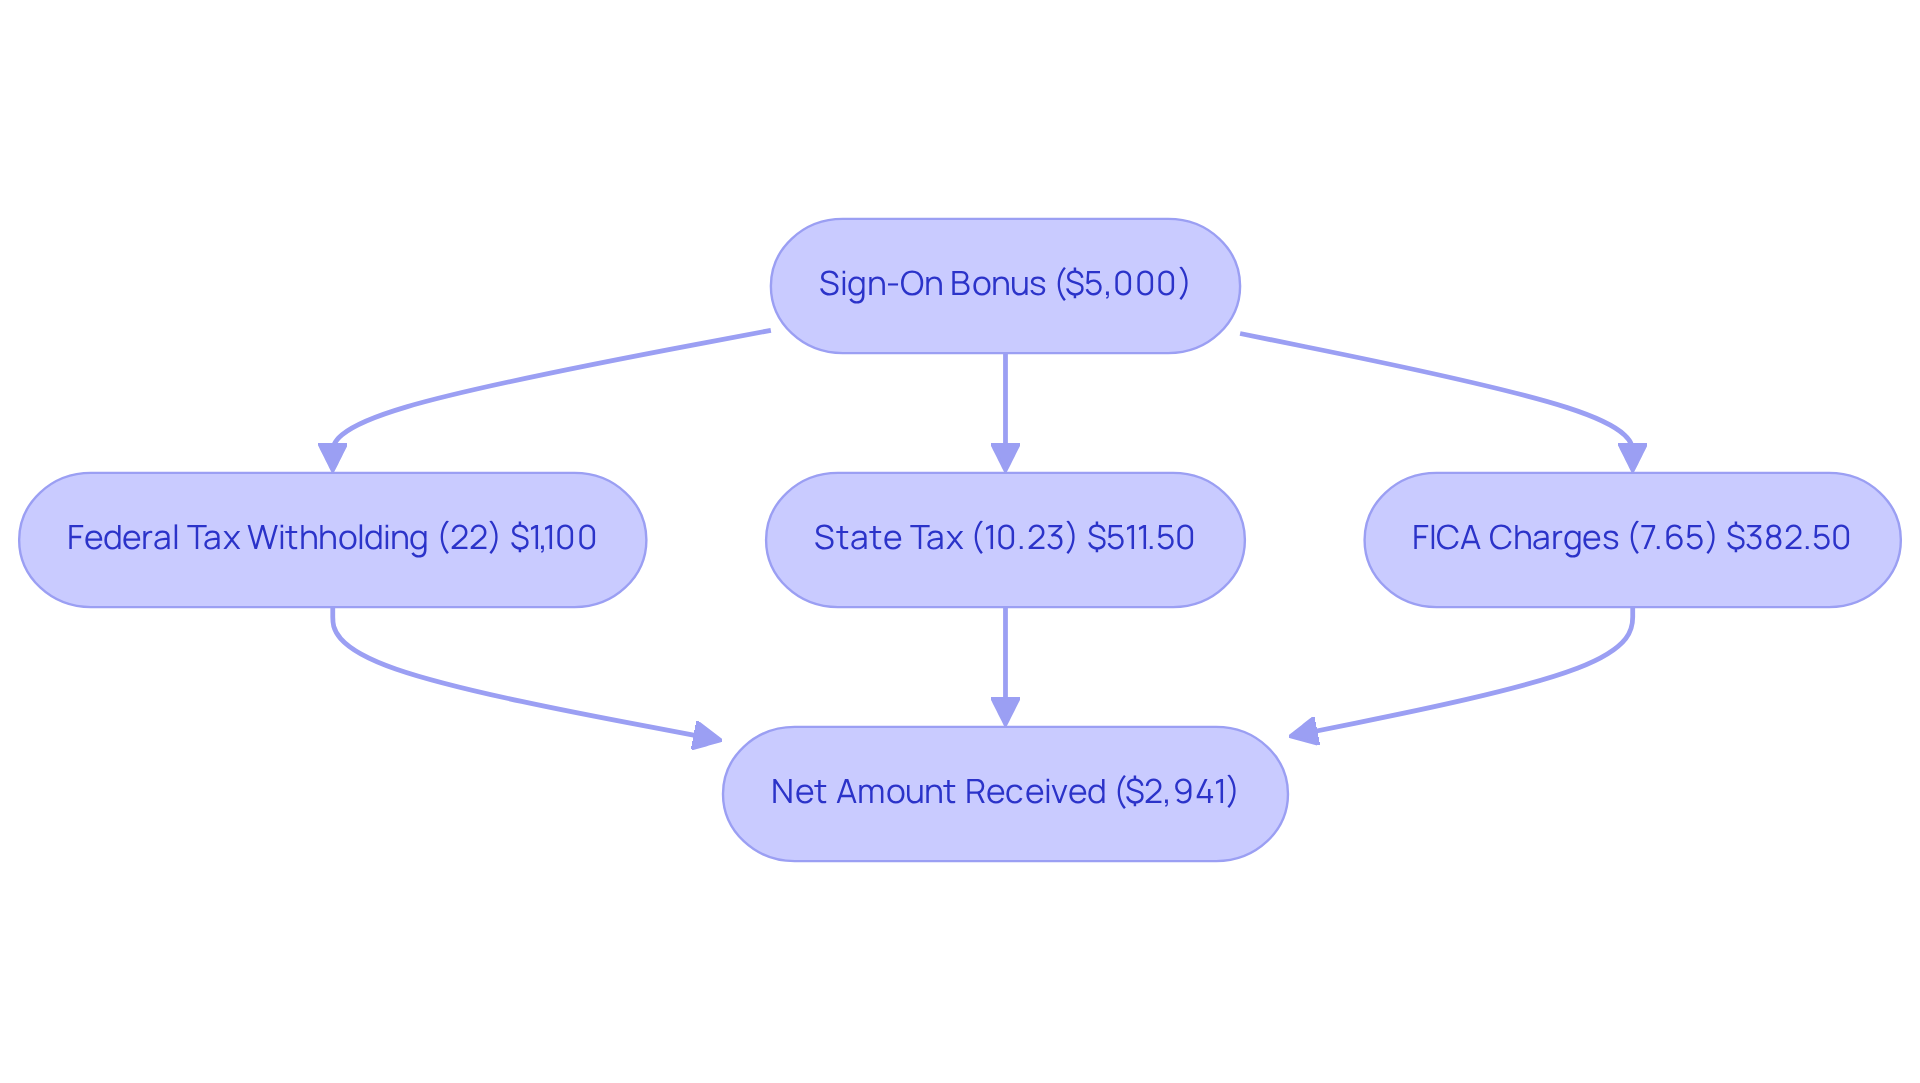
- Federal Tax Withholding: Employers generally withhold a flat rate of 22% for federal taxes on bonuses. So, if you obtain a $5,000 sign on bonus after taxes, approximately $1,100 will be deducted for federal levies.
- State Taxes: In California, the state tax rate for additional payments, such as a sign on bonus after taxes, is 10.23%, which can significantly affect the net amount received. For instance, a $5,000 incentive would result in approximately $511.50 in state levies, reflecting what one might expect as a sign on bonus after taxes.
- FICA Charges: Social Security and Medicare contributions apply as well, totaling 7.65% of your additional payment, including the sign on bonus after taxes. This means that from a $5,000 incentive, approximately $382.50 would be allocated for these levies, reflecting the sign on bonus after taxes.
When you add it all up, you might be surprised to find that nearly 41.18% could be withheld from your sign on bonus after taxes. This means that from that $5,000 sign on bonus after taxes, you might only see about $2,941 in your pocket, which can feel disheartening.
Comprehending these tax implications is crucial for families, as it directly influences the net amount received from the sign on bonus after taxes and should be considered in overall financial planning. For instance, employees in the 12% federal tax bracket who have 22% withheld may find themselves eligible for a significant refund when filing their taxes. Understanding your personal tax situation can make a big difference. If 22% was withheld from your bonus, you may have overpaid by 10 points, which is crucial for anticipating potential refunds.
At Bright Advisers, we understand that young families, like those of Jay & Emma or Emily & Mark, often face unique financial challenges. By incorporating tax planning strategies into our tailored wealth management solutions, we empower families to enhance their economic situations. This way, they can allocate resources effectively for both immediate needs and long-term goals, such as education funding and retirement planning. Together, we can navigate the complexities of financial planning, giving families the freedom to make informed decisions that align with their aspirations.
Compare Aggregate and Percentage Tax Methods
Navigating the world of sign-on incentives can feel overwhelming, especially when it comes to understanding the implications of a sign-on bonus after taxes on your family’s finances. Let’s break it down together.
When it comes to taxing sign-on incentives, employers typically choose between two primary methods: the aggregate method and the percentage method.
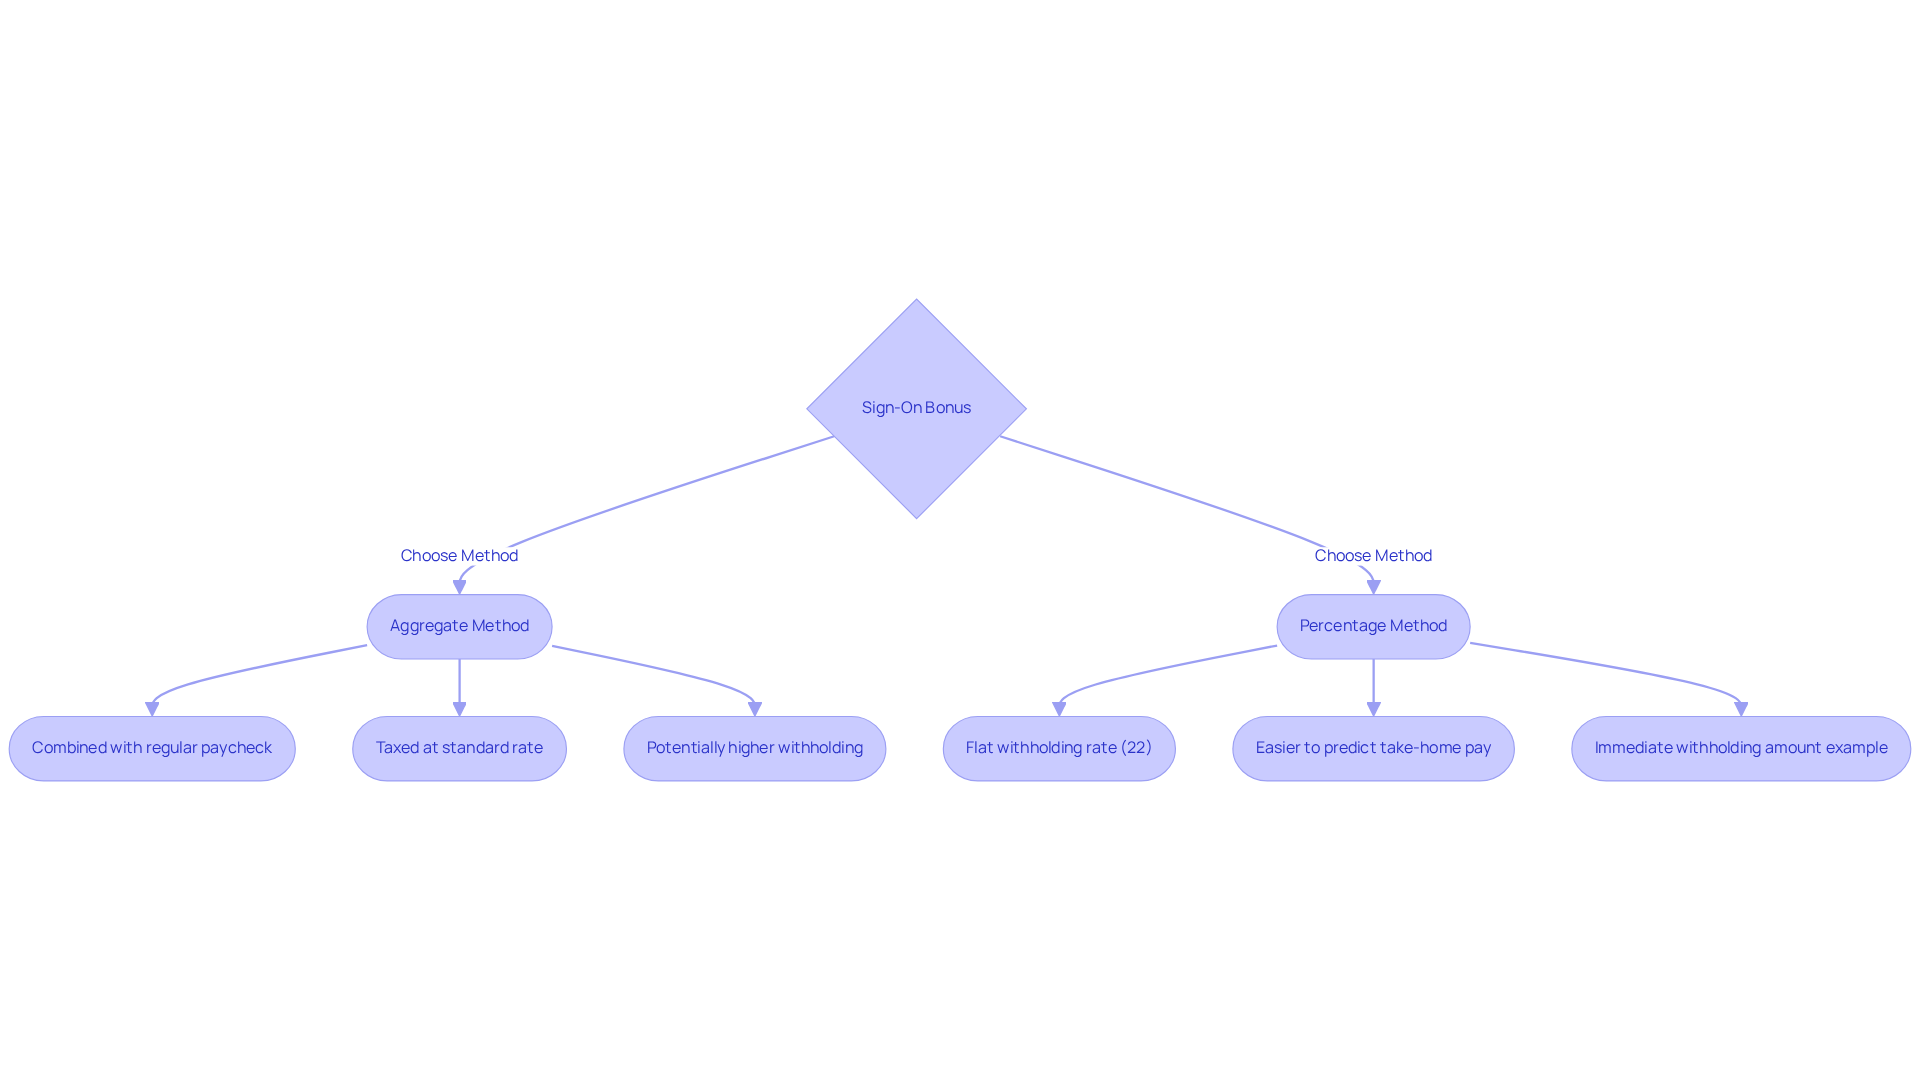
- Aggregate Method: This approach combines your additional compensation with your regular paycheck for the pay period. The total amount is taxed at your standard income tax rate. This can lead to increased withholding if the additional payment pushes you into a higher tax bracket. Imagine receiving a bonus that unexpectedly raises your tax rate – this can impact your family’s budget more than you might think.
- Percentage Approach: This method applies a flat withholding rate, usually 22%, directly to the additional payment amount, regardless of your regular income. This approach is often simpler and can result in lower immediate tax withholding, making it easier to predict your take-home pay.
Understanding these tax methods is crucial for families like yours, as it helps determine how much of that sign-on bonus after taxes will be available for immediate use versus what will be set aside for taxes. For instance, if you receive a $5,000 bonus, using the percentage approach would mean a withholding of $1,100, leaving you with $3,900. On the other hand, if the aggregate method pushes your income into a higher bracket, you might see a larger portion withheld, which could affect your budgeting.
We recommend taking a moment to review your W-4, ensuring your tax withholding aligns with your family’s needs. Consulting with an advisor can also help you navigate these complexities effectively. By understanding these tax methods, you can make informed decisions that support your family’s financial well-being.
Identify Strategies to Minimize Bonus Taxes
Imagine receiving a sign-on bonus after taxes and feeling the weight of tax implications looming over your family’s financial plans. It’s a common concern for many families, but there are ways to ease that burden and make the most of your extra earnings.
By embracing these strategies, you can make the most of your sign-on bonus after taxes and ease your family’s financial journey.
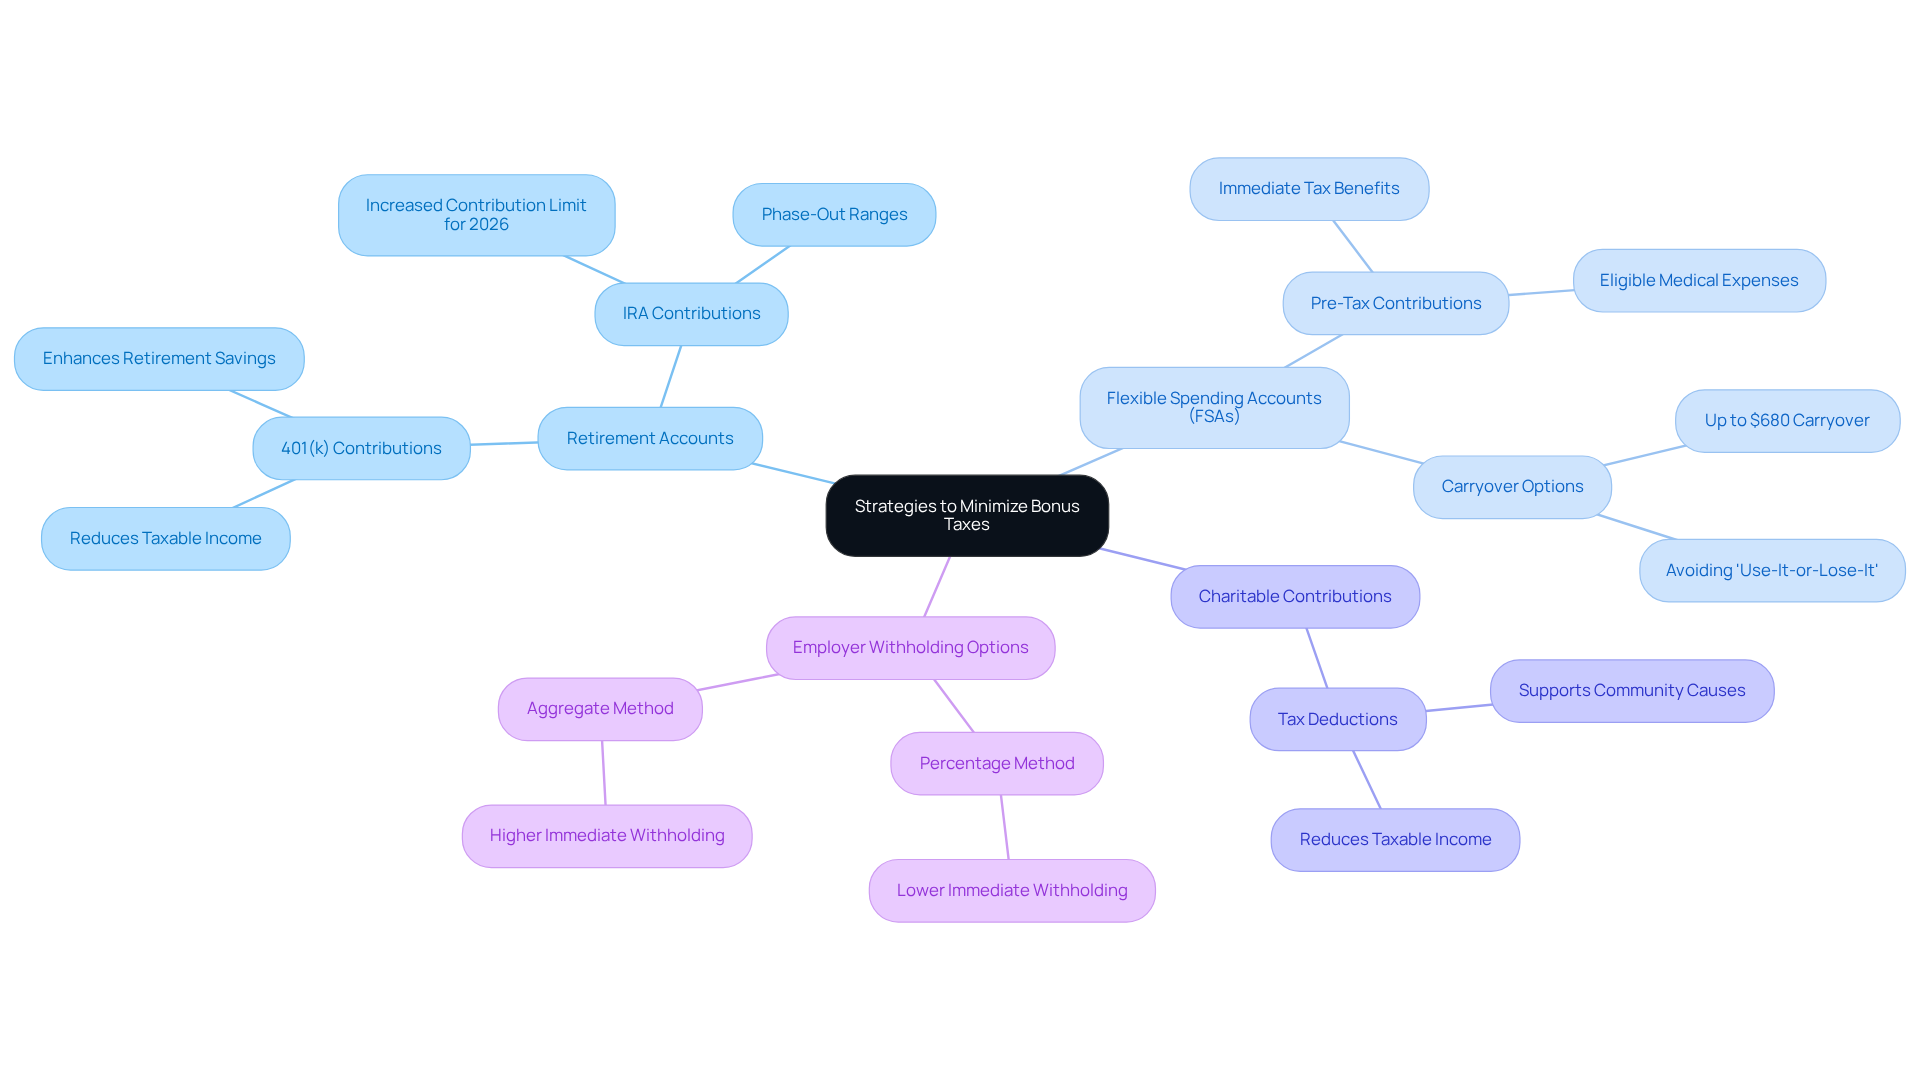
- Think about putting a portion of your bonus into retirement accounts: Allocating some of your bonus to a 401(k) or IRA can significantly reduce your taxable income for the year. Not only does this lower your overall tax liability, but it also enhances your retirement savings, paving the way for long-term financial growth.
- Consider how Flexible Spending Accounts (FSAs) can be a smart way to stretch your bonus further: If your employer offers an FSA, directing part of your extra compensation to fund it can be a wise move. Contributions to FSAs are made with pre-tax dollars, effectively decreasing your taxable income and providing immediate tax benefits.
- Plan for charitable contributions: Donating a portion of your extra earnings to charitable organizations can yield tax deductions, further reducing your taxable income. This strategy not only benefits your tax situation but also supports causes you care about, making a positive impact on your community.
- Have a heart-to-heart with your employer about your bonus withholding options: Engaging in a conversation with your employer about the withholding approach used for your incentive can be beneficial. Choosing the percentage method might result in reduced immediate tax withholding compared to the aggregate method, allowing you to keep more of your extra payment upfront.
By taking proactive steps, families can transform their financial outlook and invest more in their children’s futures. Families who actively contribute to retirement accounts and utilize FSAs often report a more manageable tax burden, enabling them to allocate funds toward essential expenses and savings goals. With these strategies, you can turn a potential tax burden into an opportunity for your family’s future.
Conclusion
Navigating the world of sign-on bonuses can be tricky, especially when it comes to understanding their tax implications. These bonuses can be a wonderful financial boost, but understanding the tax implications can feel overwhelming for many families. By understanding how these bonuses are taxed and discovering ways to lessen the tax impact, families can make informed decisions that align with their long-term financial goals.
Throughout this guide, we’ve shared key insights, including:
- The purpose of sign-on bonuses
- The various tax methods employed by employers
- Effective strategies to optimize the financial impact of these bonuses
Families are encouraged to consider the aggregate and percentage tax methods, as well as proactive measures like contributing to retirement accounts or utilizing Flexible Spending Accounts. These approaches not only help in managing tax burdens but also enhance overall financial well-being.
Ultimately, knowing the ins and outs of sign-on bonuses and their tax implications can help families feel more confident in their financial choices. By taking control of their financial planning and seeking guidance from trusted advisors like Bright Advisers, families can secure their financial futures and create lasting legacies for their children. With the right strategies and support, families can turn these bonuses into stepping stones for a brighter financial future.
Frequently Asked Questions
What is a sign-on bonus?
A sign-on bonus is a one-time financial benefit offered by employers to attract new hires, typically provided when an employee starts their new role.
What purposes do sign-on bonuses serve?
Sign-on bonuses serve several purposes: they attract talent in competitive job markets, compensate for lower salaries, and encourage candidates to accept job offers more quickly.
How prevalent are sign-on bonuses in job listings?
In 2026, about 3% of job listings in the U.S. included a sign-on incentive, which is an increase from the 2019 average of 1.8%.
Why might families consider sign-on bonuses when evaluating job offers?
Families may consider sign-on bonuses because they can significantly influence budgeting and career choices, aligning with long-term financial goals.
Can sign-on bonuses have downsides?
Yes, potential downsides include increased costs for employers and possible resentment among employees who do not receive them.
How can families benefit from strategic tax planning related to sign-on bonuses?
Families can enhance their economic potential through strategic tax planning, which can minimize tax liabilities and secure future funding for education, providing peace of mind.
List of Sources
- Define Sign-On Bonuses and Their Purpose
- 30 Average Bonus Statistics [2026]: What Is The Average Bonus Percentage? – Zippia (https://zippia.com/advice/average-bonus-statistics)
- Construction Salary Trends 2026: Pay Is Up — Are You Priced Right? (https://thebirmgroup.com/construction-salary-trends-in-2026-and-what-that-means-for-hiring-and-getting-hired)
- What is a Sign-On Bonus, and How Big Should They Be? (https://pave.com/blog-posts/what-is-a-sign-on-bonus-benchmarks)
- Healthcare Hiring Keeps Signing Bonuses Alive in a Cooling Labor Market – Indeed Hiring Lab (https://hiringlab.org/2026/02/26/healthcare-hiring-keeps-signing-bonuses-alive-in-a-cooling-labor-market)
- Explain Taxation of Sign-On Bonuses
- California Bonus Tax Rate 2026: How Much Will Be Withheld? (https://paycheckcalculatorcalifornia.com/california-bonus-tax-rate)
- 2026 California Bonus Tax Calculator – Percent (https://paycheckcity.com/calculator/flatbonus/california)
- How Are Bonuses Taxed: State and Federal Law in California (https://allisonsoares.com/california-tax-law/how-are-bonuses-taxed-in-california)
- Publication 15 (2026), (Circular E), Employer’s Tax Guide | Internal Revenue Service (https://irs.gov/publications/p15)
- Compare Aggregate and Percentage Tax Methods
- How Are Bonuses Taxed? Here’s What You Need to Know (https://northwesternmutual.com/life-and-money/how-are-bonuses-taxed)
- How Bonuses Are Taxed (https://turbotax.intuit.com/tax-tips/jobs-and-career/how-bonuses-are-taxed/L7UjtAZbh)
- How Are Bonuses Taxed? (https://experian.com/blogs/ask-experian/how-are-bonuses-taxed)
- Bonus tax rate: How bonuses are withheld in 2025 and 2026 (https://empower.com/the-currency/work/bonus-tax-rate)
- Identify Strategies to Minimize Bonus Taxes
- 401(k) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill)
- What is an FSA? Uses, Rules, and 2026 Limits (https://empower.com/the-currency/life/what-to-know-about-fsas)
- 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500)
- How Flexible Spending Accounts (FSAs) Can Lower Your Taxes (https://eztaxreturn.com/blog/how-flexible-spending-accounts-fsas-can-lower-your-taxes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading