

Overview
The Mega 401(k), often referred to as the Backdoor Roth, is an invaluable resource for young families. It allows for significantly higher contributions—up to $70,000 for those under 50 in 2025—while providing essential tax advantages that enhance your financial security during retirement.
Imagine being able to save more, ensuring a stable future for your children. This strategy not only boosts your savings potential but also offers the flexibility to adapt your financial plans over time. It addresses the common concern of depleting savings, reassuring you that a stable future is within reach.
Remember, we’re here for you as you navigate this important journey.
Key Highlights:
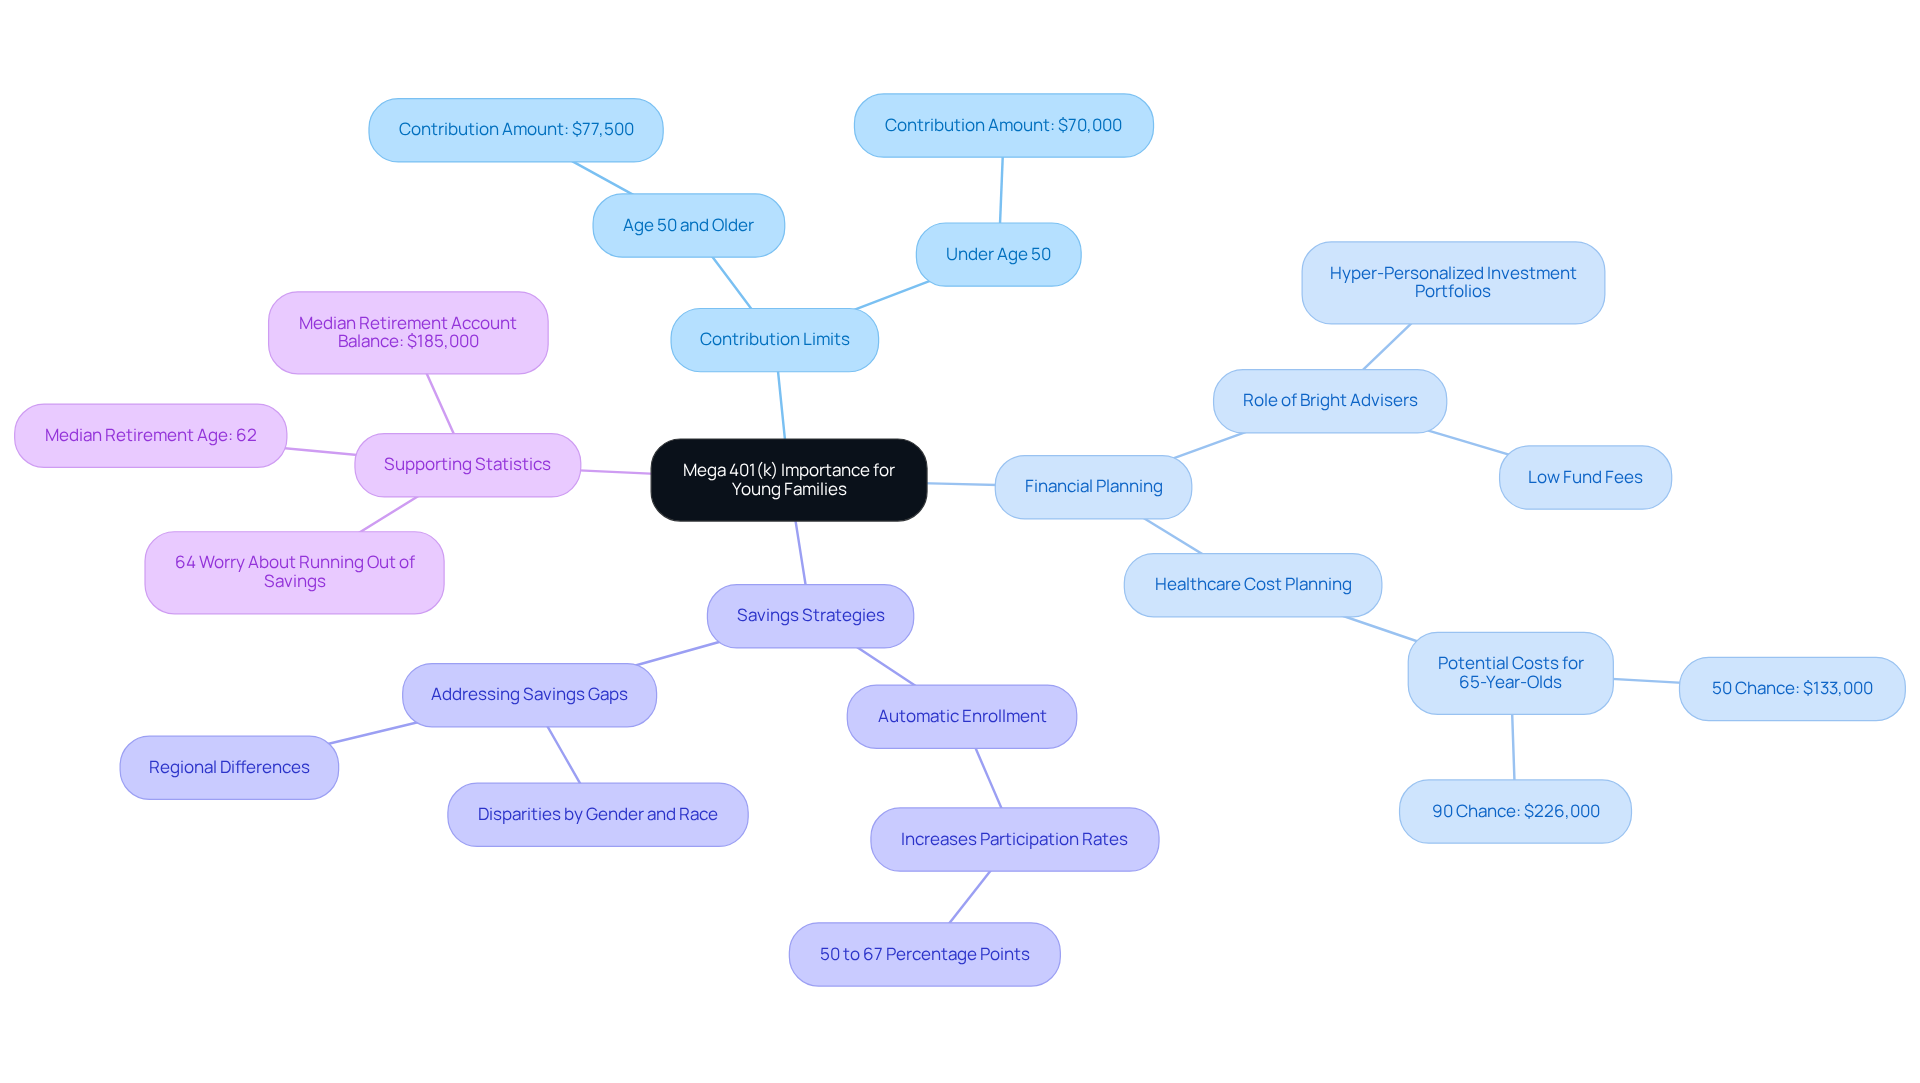
- The Mega 401(k), or Backdoor Roth, allows contributions of up to $70,000 for those under 50 and $77,500 for those 50 and older in 2025, making it vital for young families’ savings.
- Using the Backdoor strategy can significantly reduce tax burdens and enhance financial security for families during retirement.
- Bright Advisers offers tailored wealth management solutions, integrating technology to create personalised investment portfolios for families.
- Research shows that 64% of individuals worry about depleting their savings, highlighting the need for effective financial planning.
- Automatic enrolment in savings plans can boost participation rates, particularly among younger employees.
- The Mega 401(k) allows for both pre-tax and after-tax contributions, maximising savings and providing tax-free growth in Roth accounts.
- Families can adapt their savings strategies over time through the flexibility of transferring after-tax contributions to retirement accounts.
- Potential drawbacks include the complexity of the Mega Backdoor Roth, plan limitations on after-tax contributions, liquidity issues, and possible tax implications during conversions.
Introduction
As the financial landscape evolves, young families are faced with the task of navigating their future. The Mega 401(k) stands out as a powerful tool for building wealth, offering a unique opportunity to secure a brighter tomorrow. This innovative savings strategy not only allows for significantly higher contributions than traditional plans but also provides substantial tax benefits that can alleviate future financial burdens.
However, as families consider this promising opportunity, it’s important to acknowledge the complexities and potential pitfalls that can accompany such a robust retirement plan. Imagine if you could effectively leverage the Mega 401(k) to create a prosperous future for your loved ones while steering clear of common missteps.
Together, we can explore how to make the most of this financial tool, ensuring that your family’s goals and values are at the forefront of your planning. We’re here for you every step of the way, ready to support you in this journey towards financial security.
Define the Mega 401(k) and Its Importance for Young Families
The 401(k) plan, often referred to as the Backdoor Roth, represents a transformative savings strategy that allows individuals to contribute significantly more to their accounts than traditional limits allow. Imagine being able to save up to $70,000 in 2025 if you’re under age 50, or even $77,500 if you’re 50 or older. This strategy is particularly crucial for young families, as it not only boosts their savings for the future but also has the potential to reduce their tax burdens. By utilizing the Backdoor strategy, families can pave the way for a more secure financial future, easing the stress of economic uncertainty during retirement and allowing them to focus on nurturing their children.
At Bright Advisers, we prioritize innovative wealth management solutions tailored specifically for families. By integrating advanced technology, we create hyper-personalized investment portfolios that resonate with your unique family values. Our strategies, including smart beta and tactical portfolios, work hand-in-hand with the mega 401k to enhance your overall investment efficiency. Research from Allianz reveals that 64 percent of individuals worry more about exhausting their savings than about passing away, underscoring the importance of comprehensive financial planning for the years ahead.
Moreover, the US Bureau of Labor Statistics shows that automatic enrollment in savings plans can significantly boost participation rates, especially among younger employees, making these essential financial tools more accessible. The disparities in savings for later life highlight the necessity for tailored approaches like the Backdoor strategy, which can help bridge the gaps in savings across different demographics. For instance, while median account balances for individuals aged 55 to 64 hover around $185,000, many families may find this insufficient to maintain their desired lifestyle in retirement.
By embracing the Backdoor strategy alongside Bright Advisers’ commitment to low fund fees, families can better prepare for the financial demands of retirement. Together, we can ensure that you have the resources needed to support your loved ones for years to come. We’re here for you, ready to navigate this journey together.
Explain How the Mega 401(k) Works: Contributions and Tax Benefits
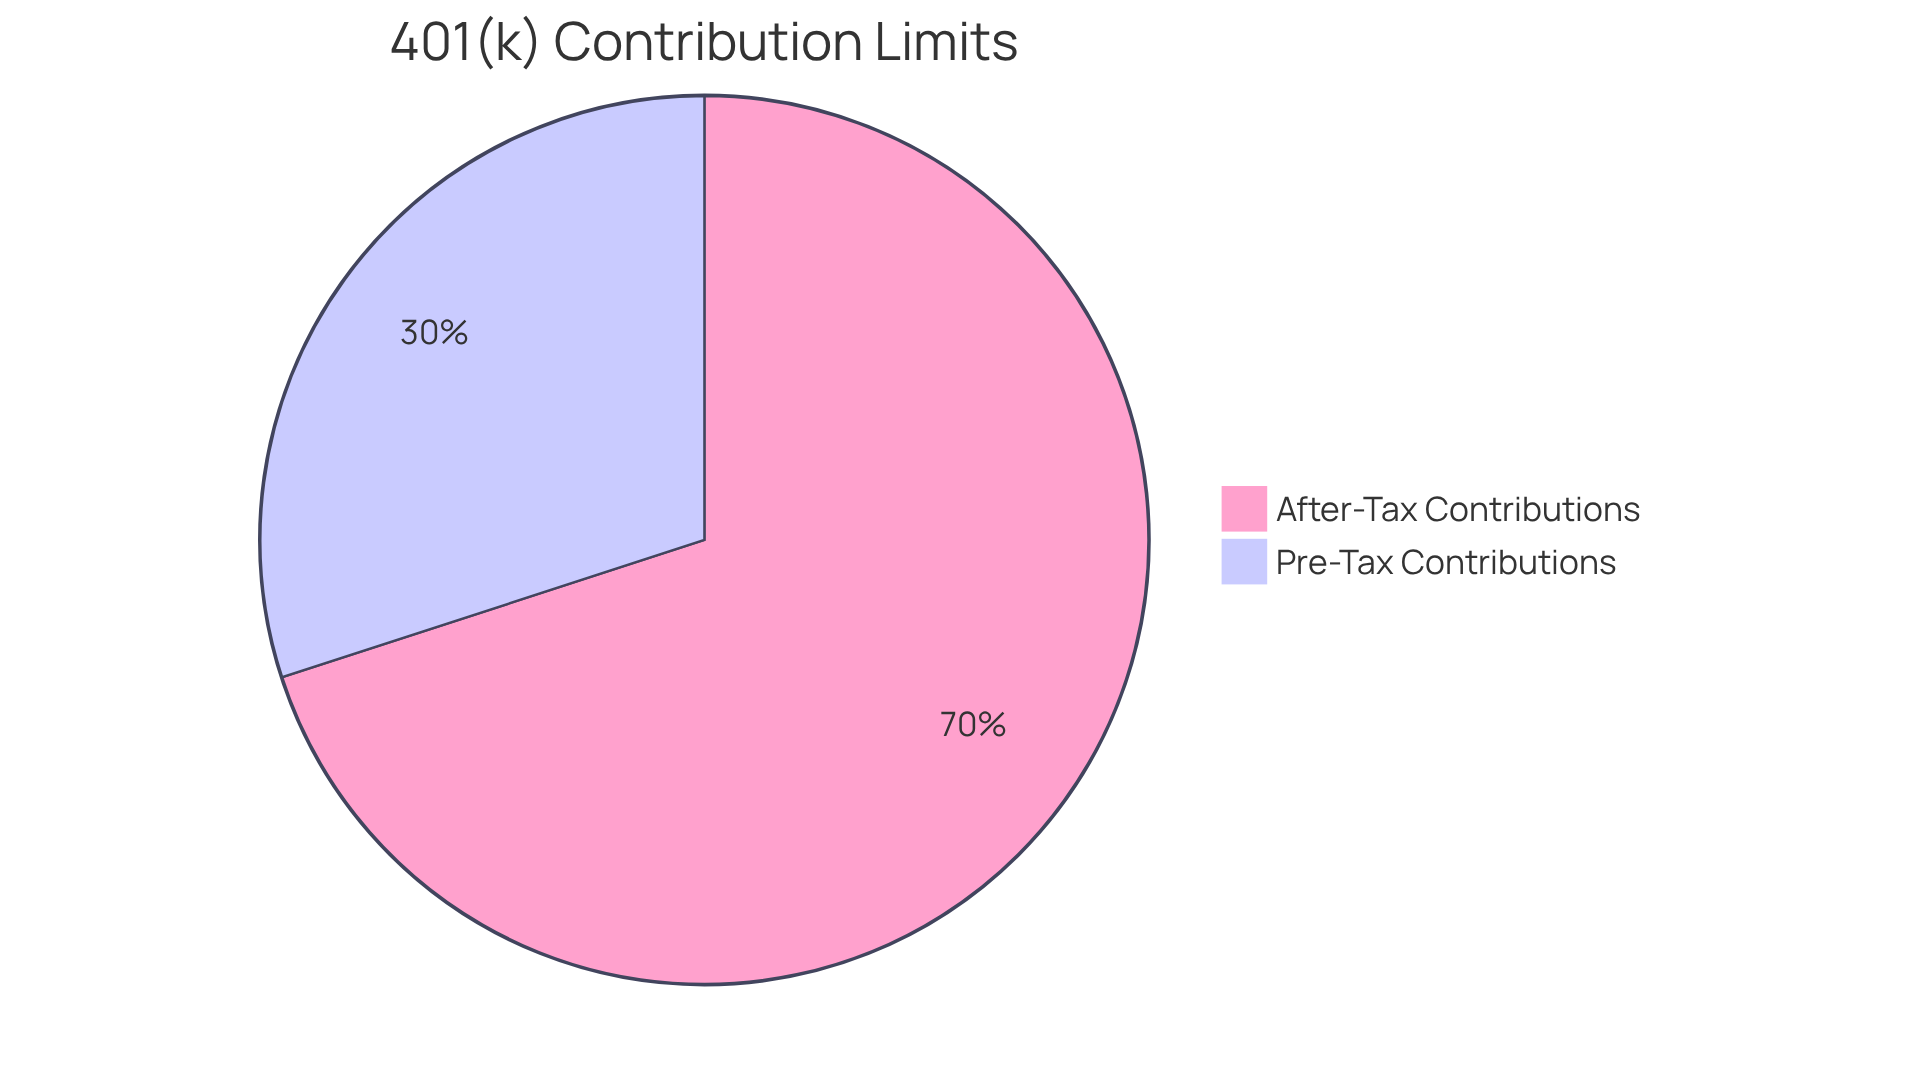
The 401(k) plan offers a wonderful opportunity for young families like Jay and Emma, allowing for both pre-tax and after-tax contributions. This powerful resource can help enhance your wealth growth and ease financial stress. Imagine being able to contribute up to $23,500 (or $31,000 if you’re 50 or older) to your 401(k) on a pre-tax basis.
But there’s more! The Backdoor strategy opens the door for additional after-tax contributions, which can reach up to $46,500 in 2025. Picture this: these after-tax contributions can be converted to a Roth account, providing you with tax-free growth and withdrawals in your later years.
This dual benefit not only maximizes your contributions but also allows you to enjoy significant tax advantages. It’s a way to balance your savings for the future while ensuring your children’s educational needs are met. Together, we can navigate this journey toward a stable financial future, making the mega 401k an appealing choice for your family’s long-term security.
Highlight the Benefits of the Mega 401(k) for Family Financial Planning
The Mega 401(k) offers remarkable advantages for family financial planning that can truly make a difference:
-
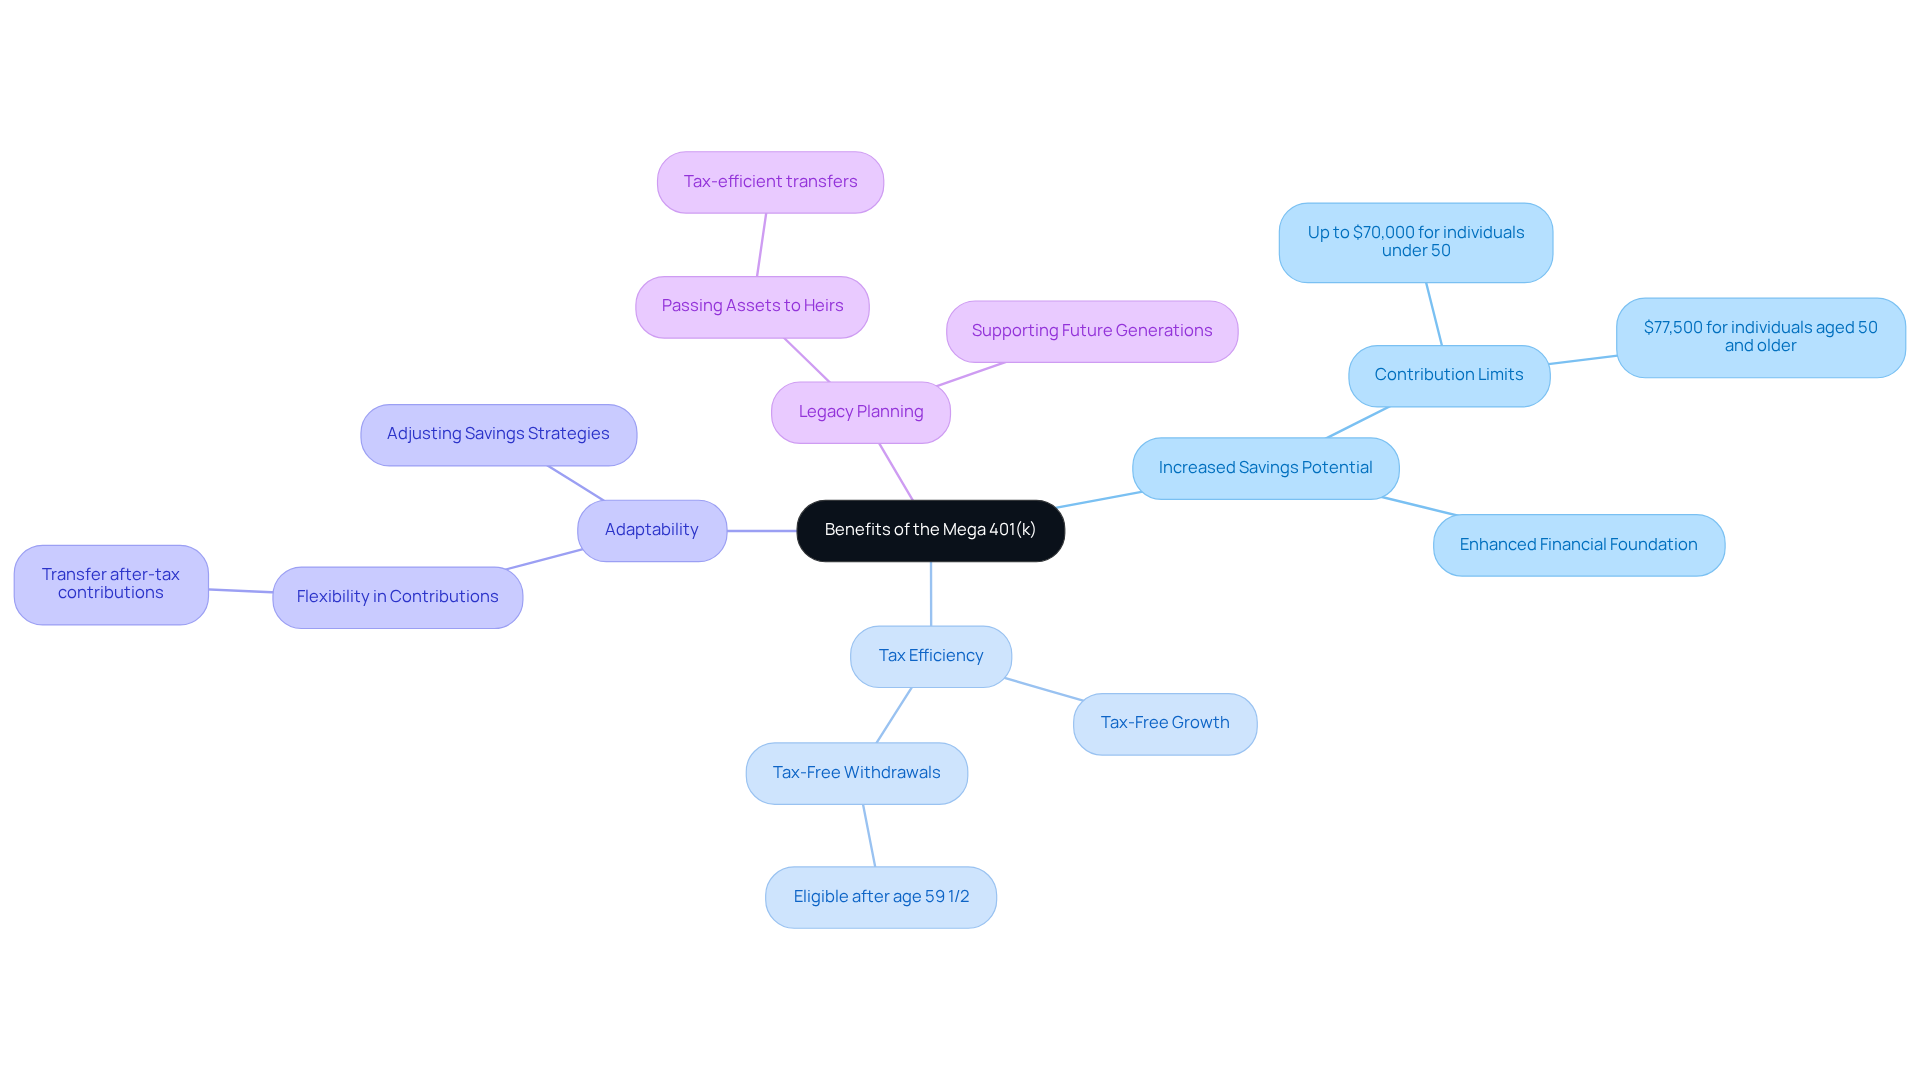
Increased Savings Potential: Imagine being able to save more for your family’s future! With contributions to a mega 401k reaching up to $70,000 for individuals under 50 and $77,500 for those aged 50 and older in 2025, families can build a stronger financial foundation. This strategy empowers you to secure a brighter tomorrow for your loved ones.
-
Tax Efficiency: It’s important to understand that contributions to a Roth-style account grow without tax, and eligible withdrawals in later years are tax-free. This means that the growth of your savings can lead to significant savings over time, making it an attractive option for families anticipating higher tax brackets in the future.
-
Adaptability: Think about how your financial needs may change over time. The ability to transfer after-tax contributions to a retirement account provides families with the flexibility to adjust their savings strategies as their circumstances evolve. This adaptability is essential for managing your family’s changing financial landscape, including strategies like a mega 401k.
-
Legacy Planning: By optimizing your savings for the future, you can create a lasting financial legacy for your children. Individual retirement account assets can be passed down to heirs in a tax-efficient manner, ensuring that future generations have the resources they need for education and other important milestones.
Consider the success stories of families like Emily and Mark, who have seen significant increases in their retirement savings by utilizing the Backdoor contribution strategy. This approach not only enhances their financial security but also prepares them to support their children’s educational aspirations.
Together, we can navigate this journey towards a secure and prosperous future for your family.
Discuss Potential Drawbacks and Considerations of the Mega 401(k)
While the 401(k) plan offers numerous benefits, it’s essential to consider some potential drawbacks and factors that may impact your family’s financial journey:
-
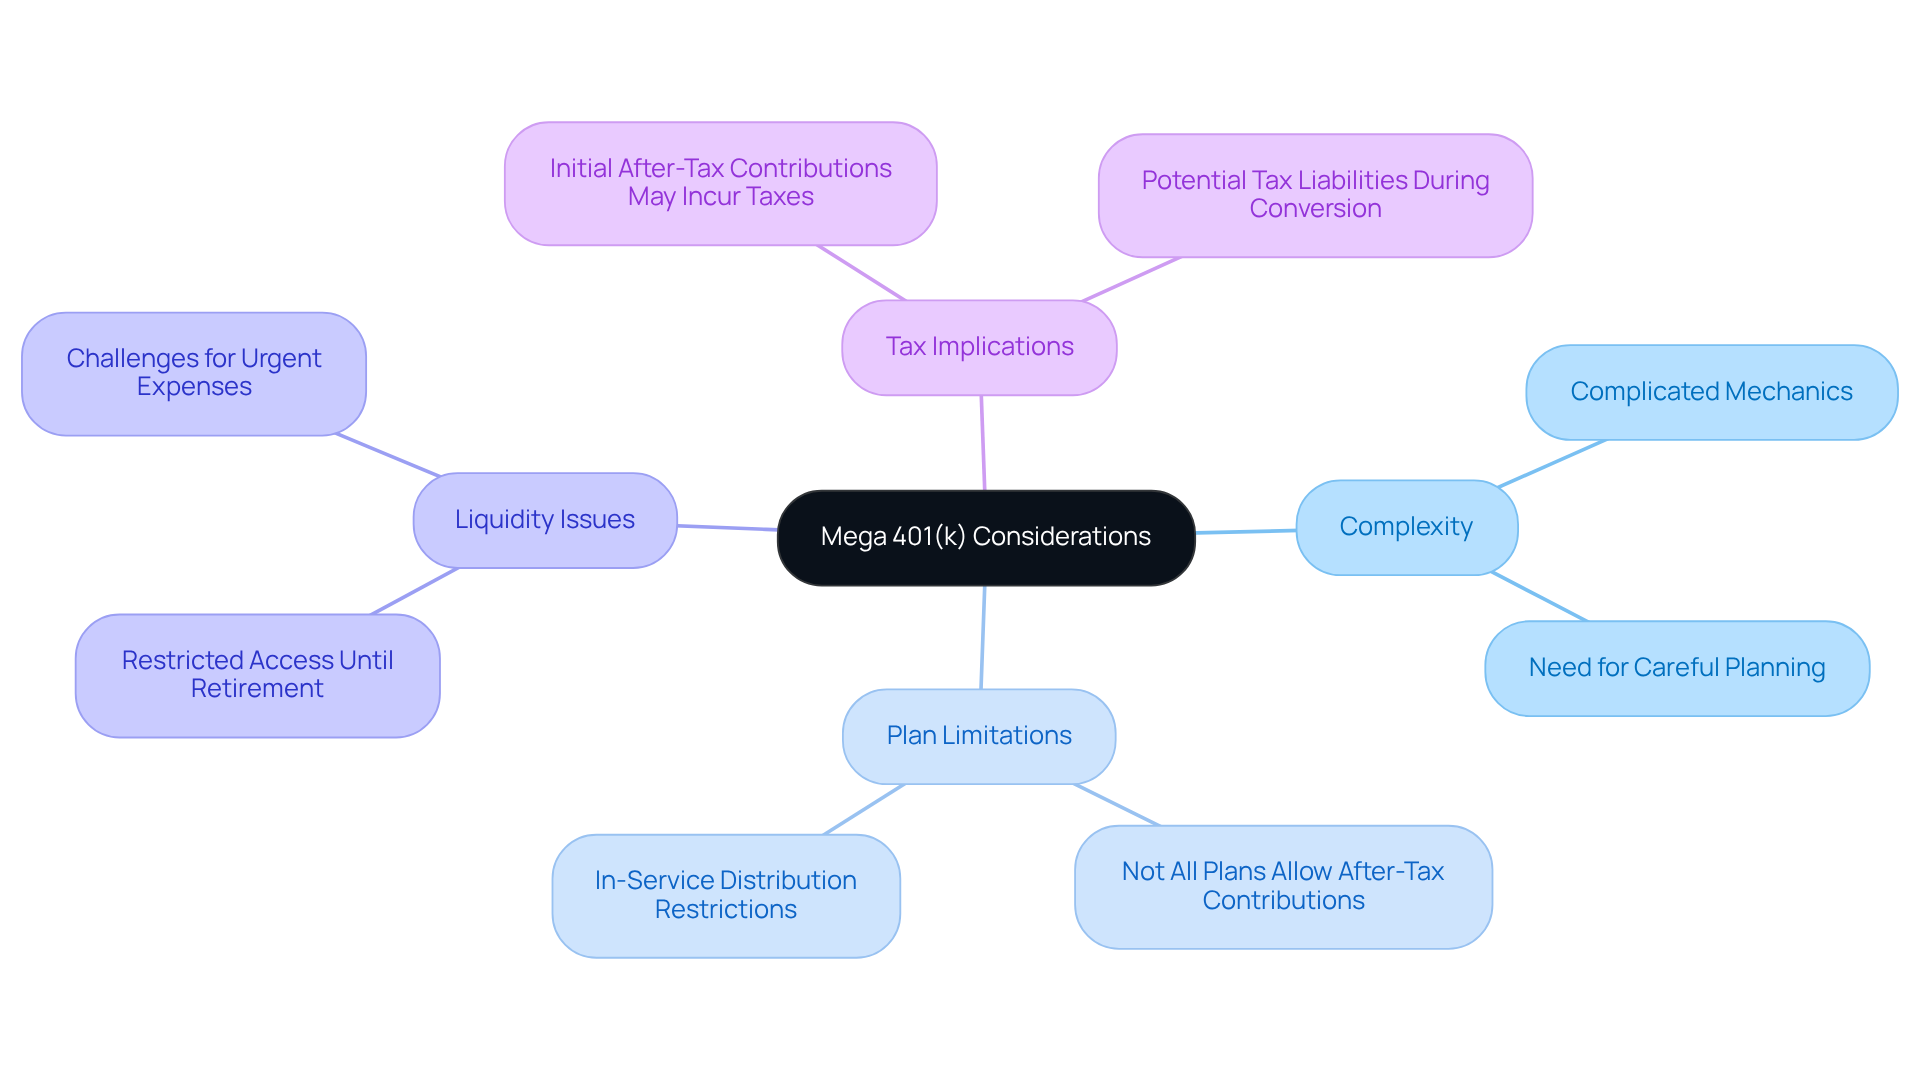
Complexity: The mechanics of the Mega Backdoor Roth can be complicated. It’s important to approach this with careful planning and a solid understanding of the tax implications that could affect your family.
-
Plan Limitations: Not all employer-sponsored 401(k) plans allow for after-tax contributions or in-service distributions. This limitation can restrict access to the valuable mega 401k strategy, so it’s worth checking your specific plan details.
-
Liquidity Issues: Contributions to a 401(k) are typically restricted until retirement age. This can be challenging for families who might need access to funds for urgent expenses, so it’s crucial to plan accordingly.
-
Tax Implications: While the growth is tax-free, remember that the initial after-tax contributions may still incur taxes. Families should be prepared for potential tax liabilities during the conversion process, ensuring that you’re well-informed as you navigate these waters.
Together, we can navigate this journey and ensure that you make the best decisions for your family’s future.
Conclusion
The Mega 401(k) represents a pivotal opportunity for young families to enhance their retirement savings and secure a stable financial future. Imagine if you could significantly increase your contributions beyond traditional limits while enjoying potential tax benefits. This innovative savings strategy not only helps in building a robust financial foundation but also alleviates the stress associated with planning for retirement.
Throughout this article, we have highlighted the advantages of the Mega 401(k). From the ability to contribute up to $70,000 in 2025 to the flexibility of after-tax contributions that can be converted to a Roth account, the benefits are substantial. Additionally, the potential for tax-free growth and withdrawals, along with the legacy planning opportunities it offers, underscores the importance of this strategy in family financial planning. It’s important to understand that while there are many benefits, being aware of the complexities and limitations that may accompany the Mega 401(k) ensures that families are well-prepared to navigate these challenges.
In reflection, embracing the Mega 401(k) can be a transformative step for young families aiming to secure their financial future. By understanding its intricacies and harnessing its benefits, families can enhance their savings and create a lasting legacy for future generations. Together, we can navigate this journey, and taking action today to explore the Mega 401(k) could lead to a more prosperous tomorrow. This makes it a vital consideration in any comprehensive financial plan.
Frequently Asked Questions
What is the Mega 401(k) and why is it important for young families?
The Mega 401(k), often referred to as the Backdoor Roth, is a savings strategy that allows individuals to contribute significantly more to their retirement accounts than traditional limits. It is particularly important for young families as it helps boost their savings for the future and can reduce their tax burdens.
How much can individuals contribute to a Mega 401(k) in 2025?
In 2025, individuals under age 50 can contribute up to $70,000 to a Mega 401(k), while those aged 50 or older can contribute up to $77,500.
What are the benefits of using the Backdoor strategy for savings?
The Backdoor strategy allows families to save more for retirement, potentially easing the financial stress associated with economic uncertainty during retirement, and enables them to focus on nurturing their children.
How does Bright Advisers support families in wealth management?
Bright Advisers offers innovative wealth management solutions tailored for families, creating hyper-personalized investment portfolios that align with their unique values. They integrate strategies like smart beta and tactical portfolios to enhance overall investment efficiency.
What does research from Allianz indicate about financial concerns?
Research from Allianz reveals that 64 percent of individuals worry more about exhausting their savings than about passing away, highlighting the importance of comprehensive financial planning for the future.
How does automatic enrollment in savings plans affect participation rates?
The US Bureau of Labor Statistics shows that automatic enrollment in savings plans can significantly increase participation rates, particularly among younger employees, making these financial tools more accessible.
What are the median account balances for individuals approaching retirement?
Median account balances for individuals aged 55 to 64 are around $185,000, which may be insufficient for many families to maintain their desired lifestyle in retirement.
How can families better prepare for retirement using the Backdoor strategy?
By embracing the Backdoor strategy in conjunction with Bright Advisers’ commitment to low fund fees, families can enhance their preparation for the financial demands of retirement, ensuring they have the necessary resources to support their loved ones.
List of Sources
- Define the Mega 401(k) and Its Importance for Young Families
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)
- Explain How the Mega 401(k) Works: Contributions and Tax Benefits
- Mega Backdoor Roth Conversions: Everything You Need to Know (https://rgwealth.com/insights/mega-backdoor-roth-strategies)
- Mega Backdoor Roth: What They Are And Contribution Limits August 2025 Edition (https://forbes.com/sites/investor-hub/article/mega-backdoor-roth-what-it-is-contribution-limits)
- 7 Key Insights on Mega Backdoor Roth Contribution for Families – Bright Advisers (https://brightadvisers.com/7-key-insights-on-mega-backdoor-roth-contribution-for-families)
- Mega Backdoor Roth Explained: Eligibility, Contribution Limits, and Tax Benefits (https://withum.com/resources/mega-backdoor-roth-explained-eligibility-contribution-limits-and-tax-benefits)
- Highlight the Benefits of the Mega 401(k) for Family Financial Planning
- What Is a Mega Backdoor Roth Conversion? (https://smartasset.com/retirement/mega-backdoor-roth-conversion)
- 7 Key Insights on Mega Backdoor Roth Contribution for Families – Bright Advisers (https://brightadvisers.com/7-key-insights-on-mega-backdoor-roth-contribution-for-families)
- Average 401(k) Balance by Age in 2025 – NerdWallet (https://nerdwallet.com/article/investing/the-average-401k-balance-by-age)
- 2024 Pulse of the American Retiree Survey: Midlife Retirement ‘Crisis’ or a 10-Year Opportunity? (https://news.prudential.com/latest-news/prudential-news/prudential-news-details/2024/2024-Pulse-of-the-American-Retiree-Survey/default.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading