

Overview
When it comes to managing your family’s wealth, understanding the fees involved is crucial. Imagine if you could make informed decisions that truly benefit your family’s future. The reality is that big banks typically charge fees ranging from 1% to 2% of assets under management, whereas private managers offer a more varied range, charging between 0.5% and 2%.
It’s important to understand how even a small difference in these fees can significantly impact your family’s wealth accumulation over time. For instance, consider how a lower fee might allow you to save more for your children’s education or your family’s future dreams.
Personalized services from private managers often provide greater value, even if their fees are on the higher end of the spectrum. They can tailor their strategies to align with your family’s unique goals and values, ensuring that your financial journey is as smooth as possible.
Together, we can navigate this journey, focusing on what truly matters for your family’s well-being. We’re here for you, ready to help you make the best choices for your loved ones. Remember, the right support can make all the difference in achieving your family’s financial aspirations.
Key Highlights:
- Wealth management includes financial planning, investment management, estate planning, and tax planning to help families manage their assets.
- Bright Advisers uses innovative technology for personalised financial planning, focusing on families’ unique needs and goals.
- Investment strategies like the Diversified Premia Strategy and Opportunity Strategy help optimise returns for long-term objectives.
- Estate planning is crucial for securing legacies and minimising tax implications for families.
- Wealth management fees from big banks typically range from 1% to 2% of assets under management, including management, performance, and hidden fees.
- A 1% fee can significantly erode wealth over time, highlighting the importance of fee comparison in investment decisions.
- Private asset managers charge between 0.5% and 2% AUM, offering personalised strategies and transparency that can enhance family financial outcomes.
- The choice between big banks and private wealth managers should consider cost, value of personalised services, and long-term financial impact.
Introduction
Navigating the complexities of wealth management can feel overwhelming, especially for families striving to secure their financial future. Imagine if you could confidently understand the various services available to you. It’s crucial to grasp the differences in fee structures between big banks and private asset managers.
This article gently explores the nuances of wealth management fees, illustrating how even minor variations can lead to significant long-term implications for your investment growth. Are you truly getting the best value for your family’s investments, or could hidden costs be lurking in the fine print?
Together, we can navigate this journey towards financial clarity.
Understanding Wealth Management: Key Concepts and Services
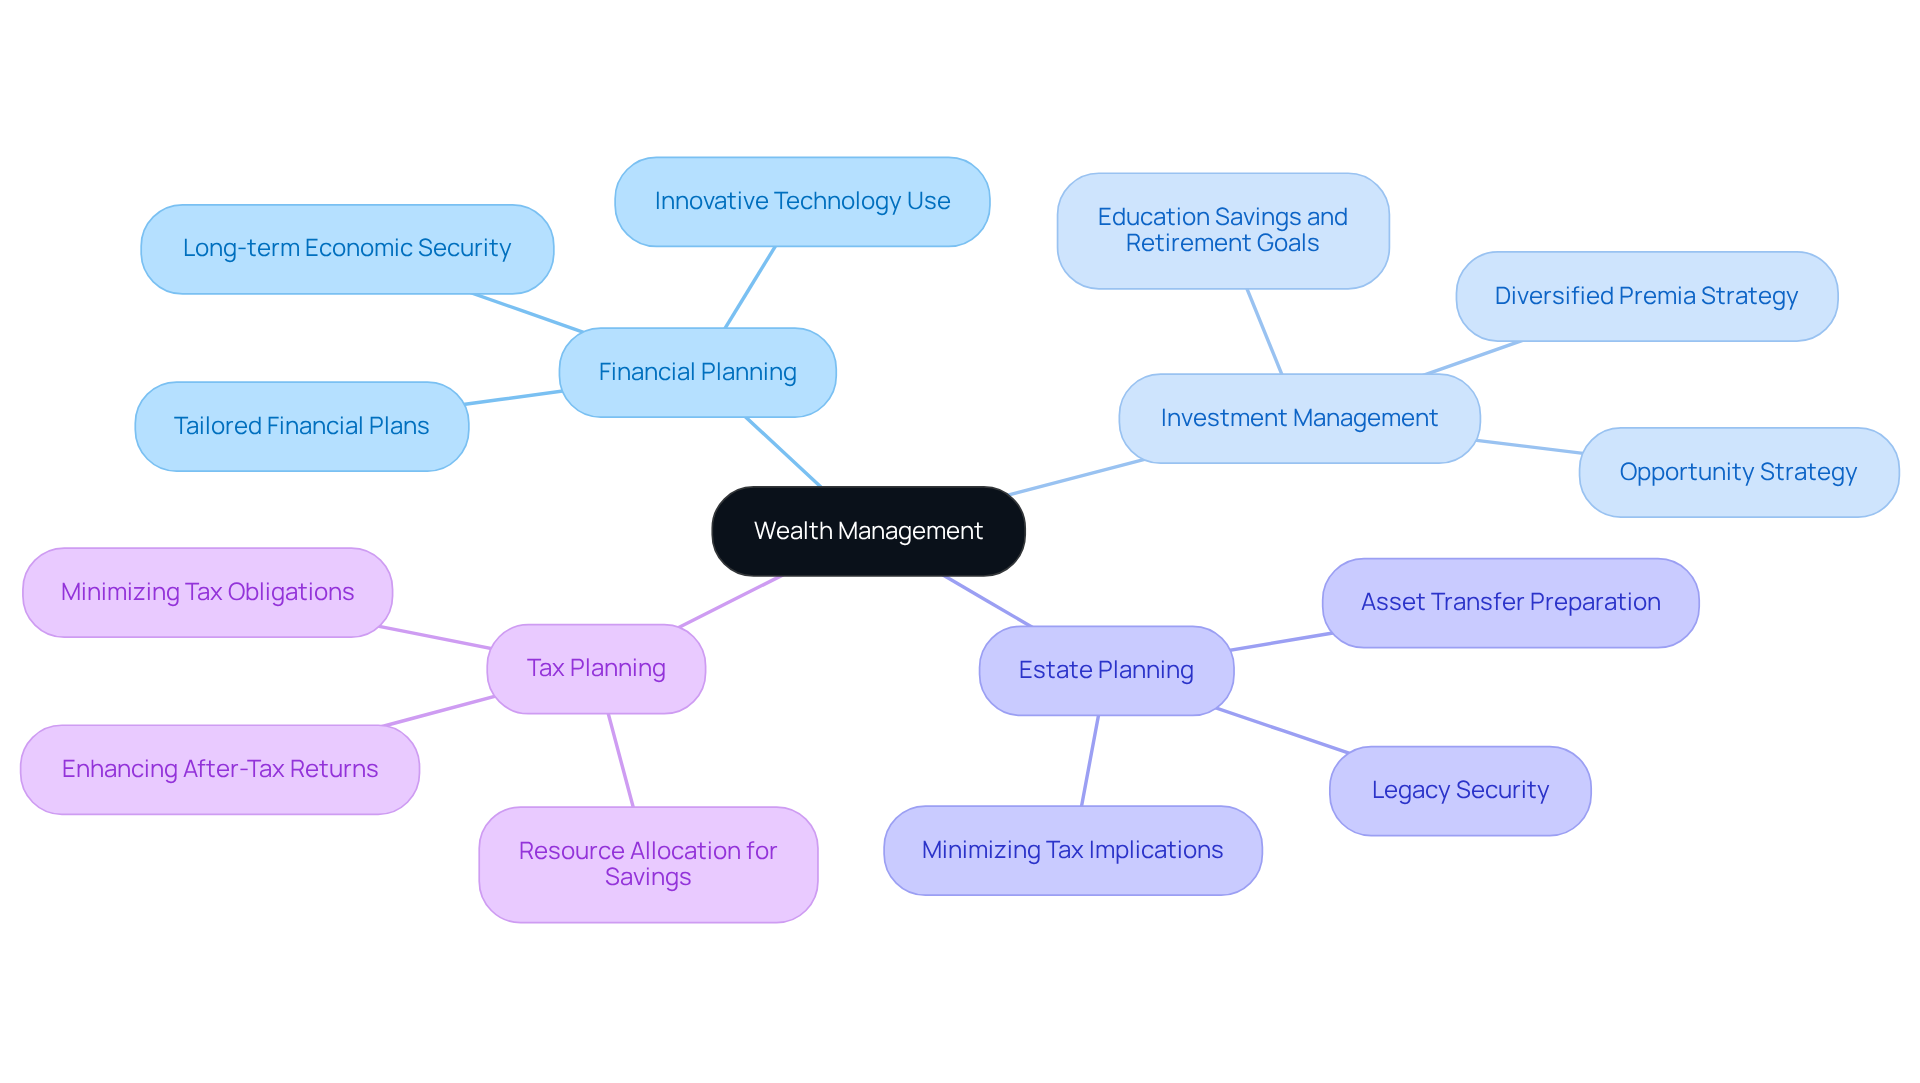
Wealth management encompasses a variety of economic assistance designed to help you and your family efficiently oversee your assets. Understanding these services is vital as you navigate your financial journey.
Financial Planning: Imagine having a financial plan that truly reflects your values and vision. At Bright Advisers, our caring team collaborates with you to develop a durable plan tailored to your family’s needs. This comprehensive approach is particularly essential for families with young children, as it lays the groundwork for future economic security and stability. With our innovative in-house technology, personalized monetary planning becomes accessible, removing unnecessary fund fees and capturing valuable tax-loss harvesting opportunities.
Investment Management: As a young family, managing your investment portfolio is crucial to optimizing returns while balancing risk. Our hyper-personalized investment strategies, such as the Diversified Premia Strategy, provide exposure to U.S. large cap equity, while the Opportunity Strategy focuses on dynamic growth factors. These strategies align with your long-term goals, such as education savings and retirement, ensuring that your investments work effectively for your family’s future.
Estate Planning: Preparing for the transfer of assets upon death is vital for securing your legacy and providing for your children’s future. At Bright Advisers, we emphasize not just managing portfolios but nurturing your family’s well-being. We ensure that your personal wishes are honored while minimizing tax implications.
Tax Planning: Organizing your finances to minimize tax obligations and enhance after-tax returns is a crucial aspect of our offerings. Effective tax planning can significantly impact your family’s financial health, allowing you to allocate more resources toward savings and investments.
It’s important to understand how these offerings can assist you in making a wealth management fees comparison between major banks and private asset managers. The intricacy and customization of these services can significantly affect the wealth management fees comparison and the value provided to you. As families like yours increasingly strive to create and preserve resources, incorporating these offerings becomes essential in achieving your financial goals. Remember, we’re here for you, and together, we can navigate this journey.
Analyzing Big Bank Wealth Management Fees: Structure and Impact
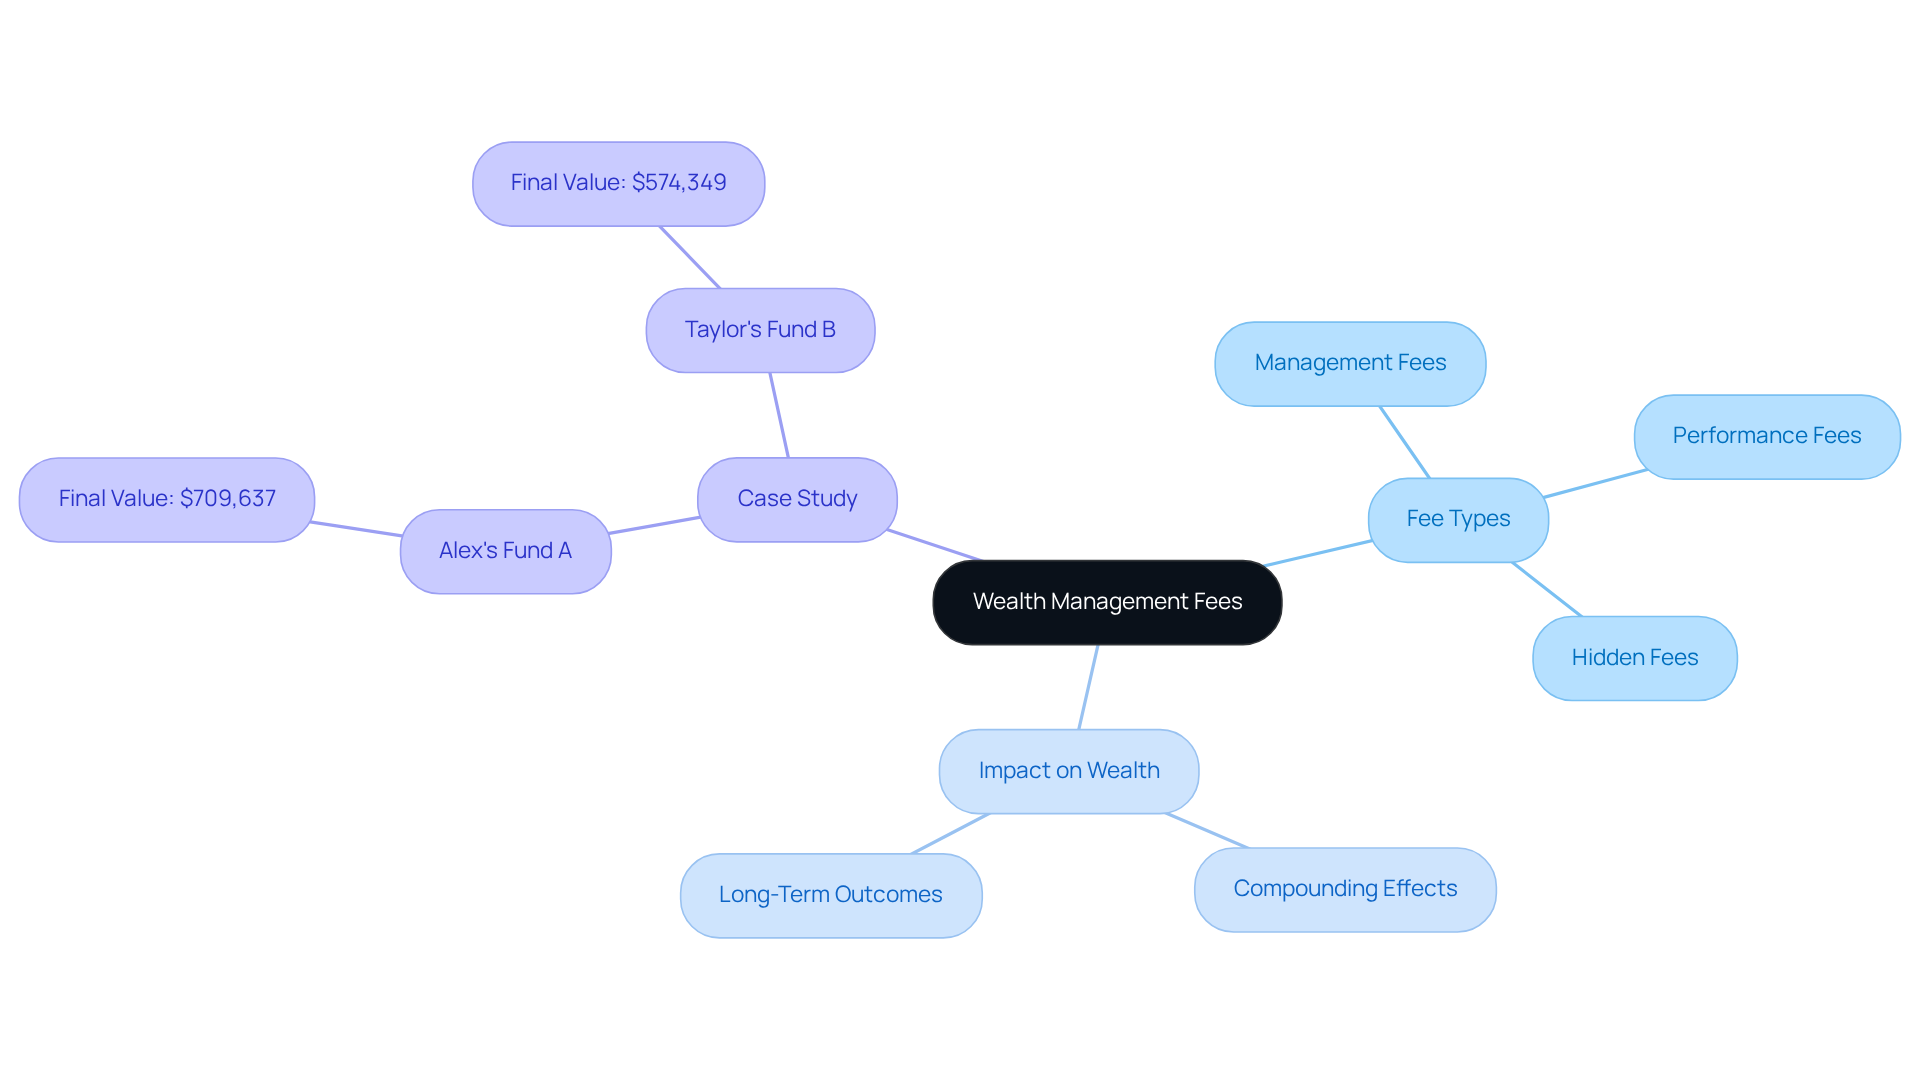
Navigating the world of wealth management can feel overwhelming, especially for young parents striving to secure their family’s financial future. Large banks often implement a tiered fee system for their wealth management services, making a wealth management fees comparison essential, as they typically charge between 1% and 2% of assets under management (AUM). This fee structure can include several components that are important to understand:
- Management Fees: A percentage of the total assets managed, which may vary based on the size of the portfolio.
- Performance Fees: Additional charges linked to investment performance, intended to encourage higher returns, but they can also raise overall costs.
- Hidden Fees: Costs related to trading, fund management, and other services that may not be immediately clear to clients.
It’s crucial to recognize the profound impact that the wealth management fees comparison can have on your family’s wealth. For instance, a seemingly modest 1% fee can significantly erode wealth over time due to the compounding effect. Imagine if a small difference in fees could lead to a vast difference in your investment returns. Research shows that even a slight variation in costs, as highlighted in wealth management fees comparison, can result in substantial differences in long-term outcomes. In fact, a 1% annual charge can reduce total returns by as much as 30% over 35 years, underscoring the long-term effects of costs on your family’s financial growth.
In contrast, Bright Advisers is committed to maintaining low fund charges across most of its models, making financial management more accessible for families like yours. While some clients may hold legacy fee-bearing mutual funds and ETFs, focusing on low-fee options—especially in fixed income and alternative asset classes—can greatly enhance long-term investment growth.
However, clients often encounter unexpected expenses due to the lack of clarity in pricing arrangements. It’s vital to carefully evaluate these charges before choosing a major bank’s asset management services. Consider the case of two investors, Alex and Taylor. Alex’s lower-cost Fund A grew to $709,637, while Taylor’s higher-fee Fund B reached only $574,349. This wealth management fees comparison illustrates the significant impact that fee differences can have on investment growth.
Understanding the full spectrum of charges empowers you to make informed decisions, ultimately safeguarding your family’s economic future. Remember, we’re here for you—together, we can navigate this journey towards financial well-being.
Evaluating Private Wealth Management Fees: Benefits and Considerations
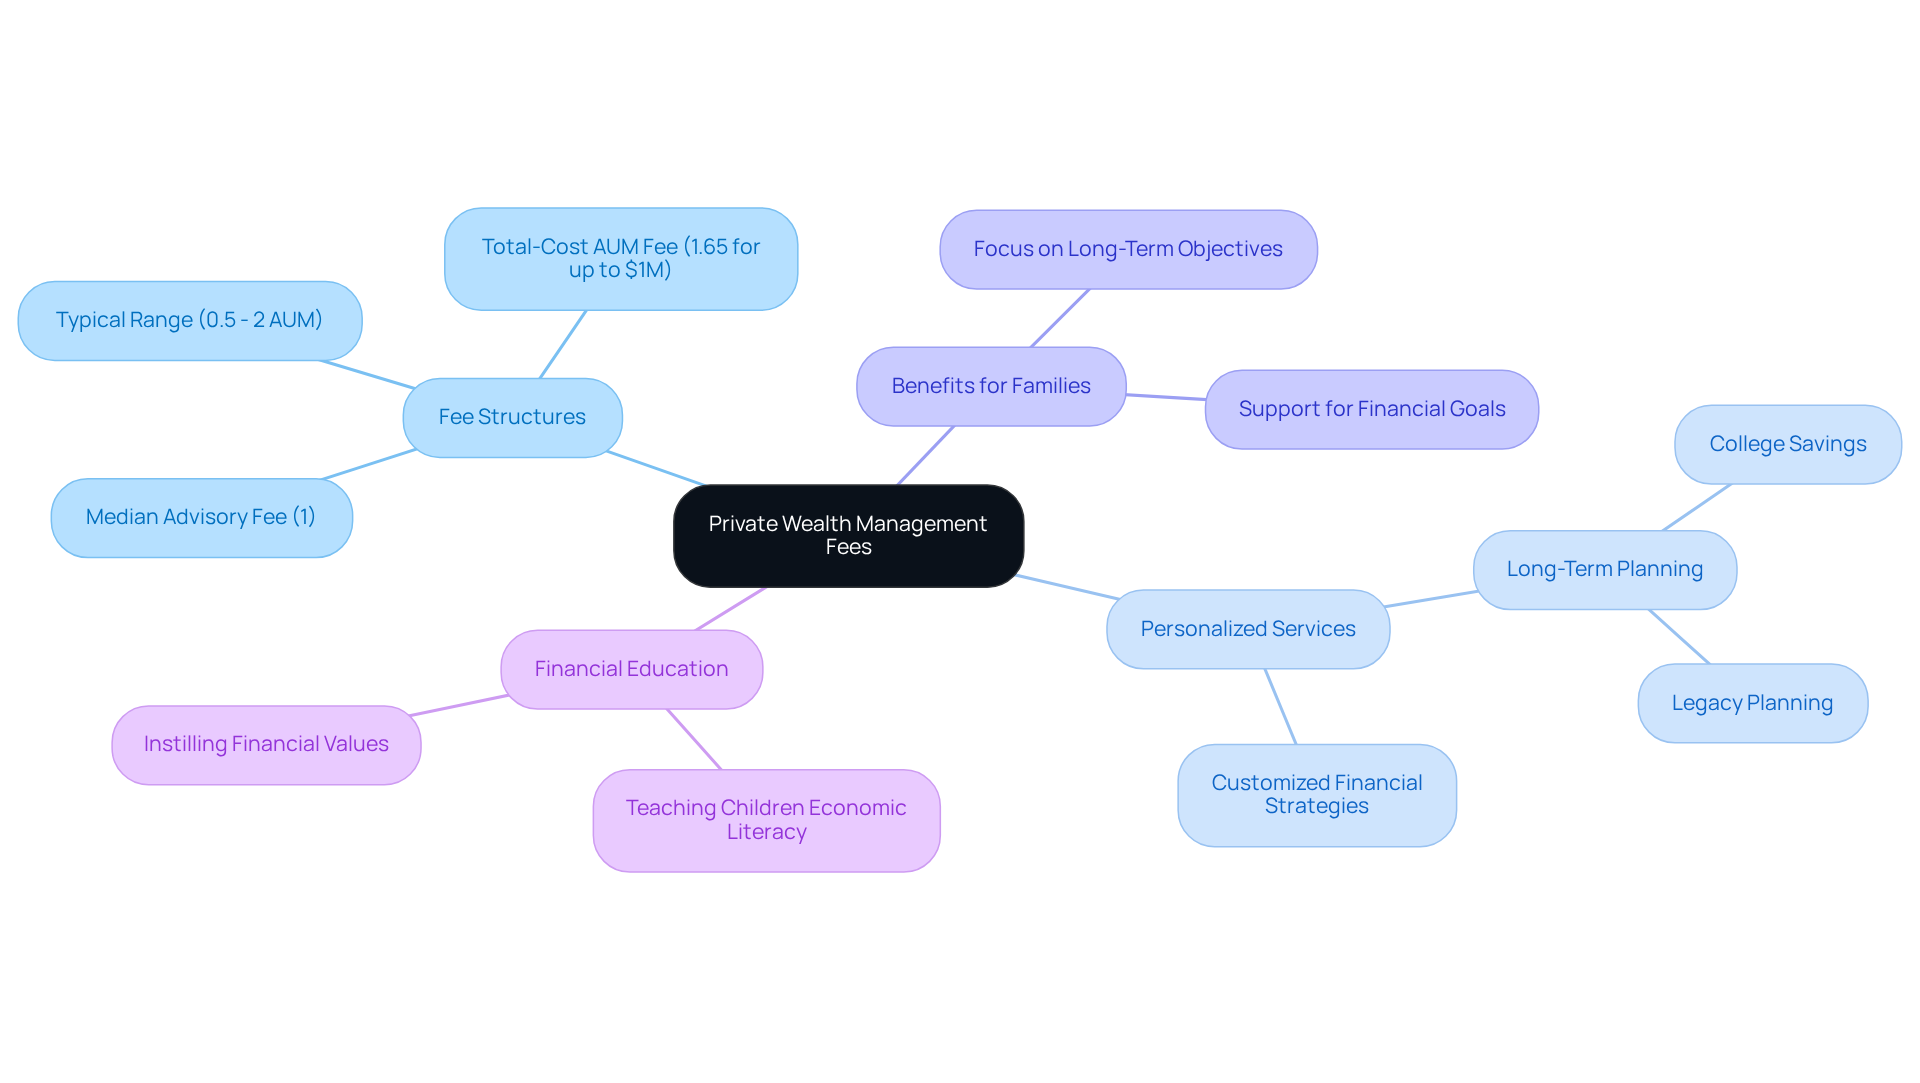
Private asset management companies typically charge between 0.5% and 2% of assets under management (AUM), with fees influenced by the complexity of services offered. For families, especially those with young children, the benefits of choosing a private manager can be significant.
Imagine having a financial partner who understands your unique goals. Private managers offer personalized services that create customized financial strategies tailored to your family’s values. This approach is particularly vital for families focusing on long-term objectives like education and legacy planning. For instance, a personalized investment plan can help parents save for their children’s college education while also addressing their retirement needs.
Understanding the wealth management fees comparison is important to grasp the cost structures involved. Many private wealth managers prioritize transparency, which includes providing clients with a wealth management fees comparison to ensure they have a clear understanding of all associated fees. This openness stands in stark contrast to traditional banks, where hidden fees can accumulate unexpectedly. A straightforward fee system fosters trust, empowering families to make informed choices about their financial futures.
In addition to investment management, private companies often extend their support to include financial education for children. This invaluable resource helps families instill economic literacy in the next generation, equipping children with the knowledge they need to make sound financial decisions as they grow.
While the wealth management fees comparison between private asset managers and major banks may show alignment, the personalized approach and additional services often provide greater value. Families striving to create and maintain multi-generational resources can greatly benefit from these tailored strategies, ensuring their financial goals are met while focusing on what truly matters—their loved ones. Together, we can navigate this journey toward a secure financial future.
Comparing Value: Big Banks vs. Private Wealth Managers in Wealth Management
When considering the differences between big banks and private wealth managers, several important factors come to light that can truly impact your family’s financial journey.
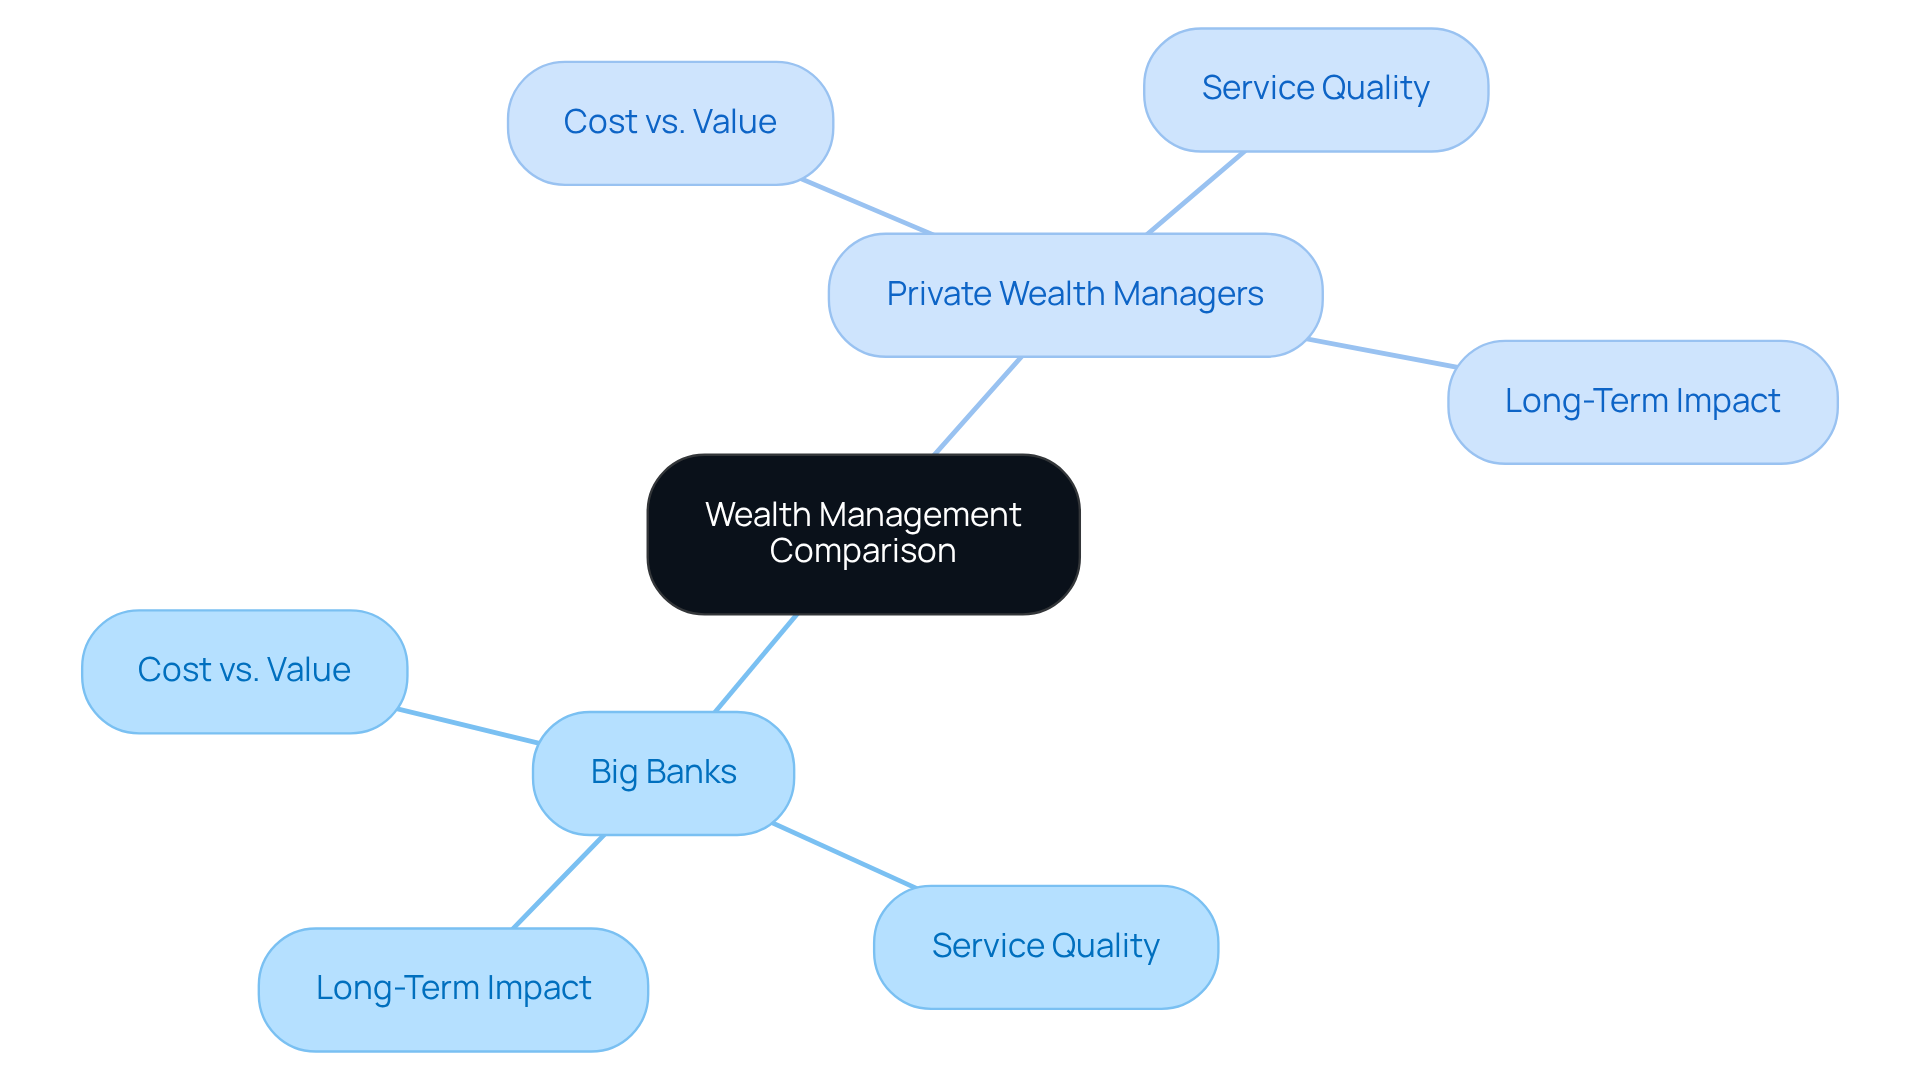
Cost vs. Value: While big banks might offer lower fees, a wealth management fees comparison reveals that the true value of personalized services and comprehensive financial planning from private wealth managers often outweighs that cost difference. Imagine having customized solutions that align perfectly with your family’s unique objectives—this can make all the difference in achieving your dreams.
- Service Quality: Private asset managers typically provide an exceptional level of service, characterized by direct access to dedicated advisors and tailored strategies. This personalized approach is especially beneficial for families, as it fosters a deeper understanding of your financial situation and enhances decision-making.
- Long-Term Impact: Families working with private asset managers may enjoy more favorable long-term financial outcomes. These experts prioritize education and legacy planning, ensuring that financial knowledge and values are passed down effectively to future generations. This comprehensive asset management not only secures your family’s financial stability but also nurtures a culture of informed resource stewardship.
Ultimately, the choice between big banks and private wealth managers should be guided by your individual financial goals, the complexity of your needs, and the wealth management fees comparison, along with the vital role that personalized service plays in achieving lasting financial success. Remember, we’re here for you—together, we can navigate this journey toward a secure and prosperous future for your family.
Conclusion
Navigating the landscape of wealth management can feel overwhelming, especially for families striving to secure their future. It’s crucial to understand the differences between the services offered by big banks and private wealth managers. By comparing wealth management fees and recognizing the value of personalized financial strategies, families can make informed decisions that align with their long-term goals.
Imagine if you could choose a path that not only meets your financial needs but also nurtures your family’s values. While big banks may present lower fees, the comprehensive and tailored services provided by private managers often yield greater benefits. Even minor differences in costs can significantly impact wealth accumulation over time. Private managers prioritize transparency and personalized service, enhancing financial outcomes and fostering a culture of financial literacy within families.
Ultimately, the choice between big banks and private wealth managers should reflect your family’s unique needs and aspirations. Understanding how wealth management fees are structured and appreciating the value of personalized services is essential for securing a prosperous future. We encourage you to assess your unique situation and consider the long-term implications of your financial decisions. Together, we can navigate this journey, ensuring you choose the path that best supports your goals and nurtures your legacy.
Frequently Asked Questions
What is wealth management?
Wealth management encompasses a variety of economic assistance designed to help individuals and families efficiently oversee their assets and navigate their financial journey.
Why is financial planning important?
Financial planning is essential as it creates a plan that reflects your values and vision, providing a foundation for future economic security and stability, particularly for families with young children.
How does Bright Advisers assist with financial planning?
Bright Advisers collaborates with clients to develop a durable financial plan tailored to their family’s needs, utilizing innovative in-house technology to make personalized monetary planning accessible and cost-effective.
What is investment management, and why is it important for young families?
Investment management involves optimizing investment portfolios to balance returns and risk. It’s crucial for young families to ensure that their investments align with long-term goals like education savings and retirement.
What investment strategies does Bright Advisers offer?
Bright Advisers offers hyper-personalized investment strategies, including the Diversified Premia Strategy for U.S. large cap equity exposure and the Opportunity Strategy focusing on dynamic growth factors.
What is the role of estate planning in wealth management?
Estate planning is vital for preparing the transfer of assets upon death, securing your legacy, and providing for your children’s future while minimizing tax implications and honoring personal wishes.
How does tax planning impact financial health?
Tax planning organizes finances to minimize tax obligations and enhance after-tax returns, significantly impacting a family’s financial health by allowing more resources to be allocated toward savings and investments.
How can I compare wealth management fees between banks and private asset managers?
Understanding the intricacy and customization of wealth management services can help you make a comparison of fees between major banks and private asset managers, as these factors can significantly affect the value provided.
List of Sources
- Understanding Wealth Management: Key Concepts and Services
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 30+ Financial Advisor Statistics (https://bizplanr.ai/blog/financial-advisor-statistics)
- Wealth Management Industry Statistics 2025: Data-Driven Insights and Projections (https://coinlaw.io/wealth-management-industry-statistics)
- Wealth Management – United States | Market Forecast (https://statista.com/outlook/fmo/wealth-management/united-states)
- Analyzing Big Bank Wealth Management Fees: Structure and Impact
- Small Fees Have A Big Impact On Your Investments (https://forbes.com/advisor/investing/impact-of-investment-fees)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Wealth Management: What It Is, Costs, Minimums – NerdWallet (https://nerdwallet.com/article/investing/what-is-wealth-management)
- Small fees, big impact: Understanding the long-term cost of investment fees (https://fifthperson.com/small-fees-big-impact-long-term-cost-fees)
- Investment Management: Report on
Mutual Fund Fees and Expenses (https://sec.gov/news/studies/feestudy.htm)
- Evaluating Private Wealth Management Fees: Benefits and Considerations
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Independent Financial Advisor Fee Comparison: All-In Costs (https://kitces.com/blog/independent-financial-advisor-fees-comparison-typical-aum-wealth-management-fee)
- Money Lessons You Can Learn From 5 Timeless Quotes (https://northwesternmutual.com/life-and-money/money-lessons-you-can-learn-from-5-timeless-quotes)
- The Benefits of Working with a Wealth Manager (https://buttonwoodfg.com/the-benefits-of-working-with-a-wealth-manager)
- Comparing Value: Big Banks vs. Private Wealth Managers in Wealth Management
- Overview of Private Wealth Management | CFA Institute (https://cfainstitute.org/insights/professional-learning/refresher-readings/2025/overview-private-wealth-management)
- Global: top wealth management and advisory firms 2024, by client satisfaction| Statista (https://statista.com/statistics/1482707/leading-wealth-management-and-advisory-firms-worldwide-client-satisfaction-rate)
- Quotes of the World’s greatest people on wealth management – Serrari Group (https://serrarigroup.com/quotes-of-the-worlds-greatest-people-on-wealth-management)
- How the Private Banking & Wealth Management Industries Work (https://umbrex.com/resources/how-industries-work/banking-financial-services/how-the-private-banking-wealth-management-industry-works)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading