

Overview
Exceeding the Roth IRA contribution limit can lead to a 6% excise tax on the excess amount for each year it remains uncorrected. This situation can create significant financial stress for families. It’s crucial to understand that timely corrective actions, such as withdrawing excess contributions or reallocating them to a traditional IRA, can help you avoid penalties.
Imagine if you could take control of your financial future and protect your family’s well-being. By addressing these excess contributions promptly, you can ensure compliance with contribution limits and maintain peace of mind.
We’re here for you, guiding you through these important decisions. Together, we can navigate this journey and help you secure the financial stability your family deserves.
Key Highlights:
- A Roth IRA allows individuals to contribute after-tax income, with tax-free withdrawals in retirement under certain conditions.
- For 2025, the contribution limit is $7,000 for individuals under 50 and $8,000 for those 50 and older, with limits phasing out for higher earners.
- Exceeding the Roth IRA contribution limit incurs a 6% excise tax on the excess amount for each year it remains uncorrected.
- Individuals can avoid penalties by withdrawing excess contributions before the tax filing deadline or applying them to the following year’s limit.
- Recharacterizing excess deposits from a Roth IRA to a traditional IRA is another corrective option.
- Common misconceptions include the belief that anyone can contribute to a Roth IRA regardless of income, and that excess contributions can be withdrawn without consequences.
- The combined contribution limit for both Roth and traditional IRAs is $7,000 for 2025, or $8,000 for those aged 50 and older.
Introduction
Navigating the complexities of retirement savings can feel overwhelming, especially when it comes to understanding the rules surrounding Roth IRA contributions. Imagine if you could confidently manage your savings without the fear of making costly mistakes. This article shines a light on the essential aspects of excess contributions, including the implications of exceeding annual limits and the potential penalties that can arise from such missteps.
With contribution limits set to change in 2025, it’s more important than ever for individuals and families to grasp these regulations. We understand that financial planning can be daunting, but we’re here to help you avoid pitfalls and secure your family’s future. From corrective actions to common misconceptions, this comprehensive guide equips you with the knowledge needed to optimize your retirement planning.
Together, we can navigate this journey, ensuring that you make informed decisions that resonate with your family’s values and priorities. Let’s explore how understanding these regulations can lead to a financially sound future for you and your loved ones.
Define Excess Roth IRA Contributions
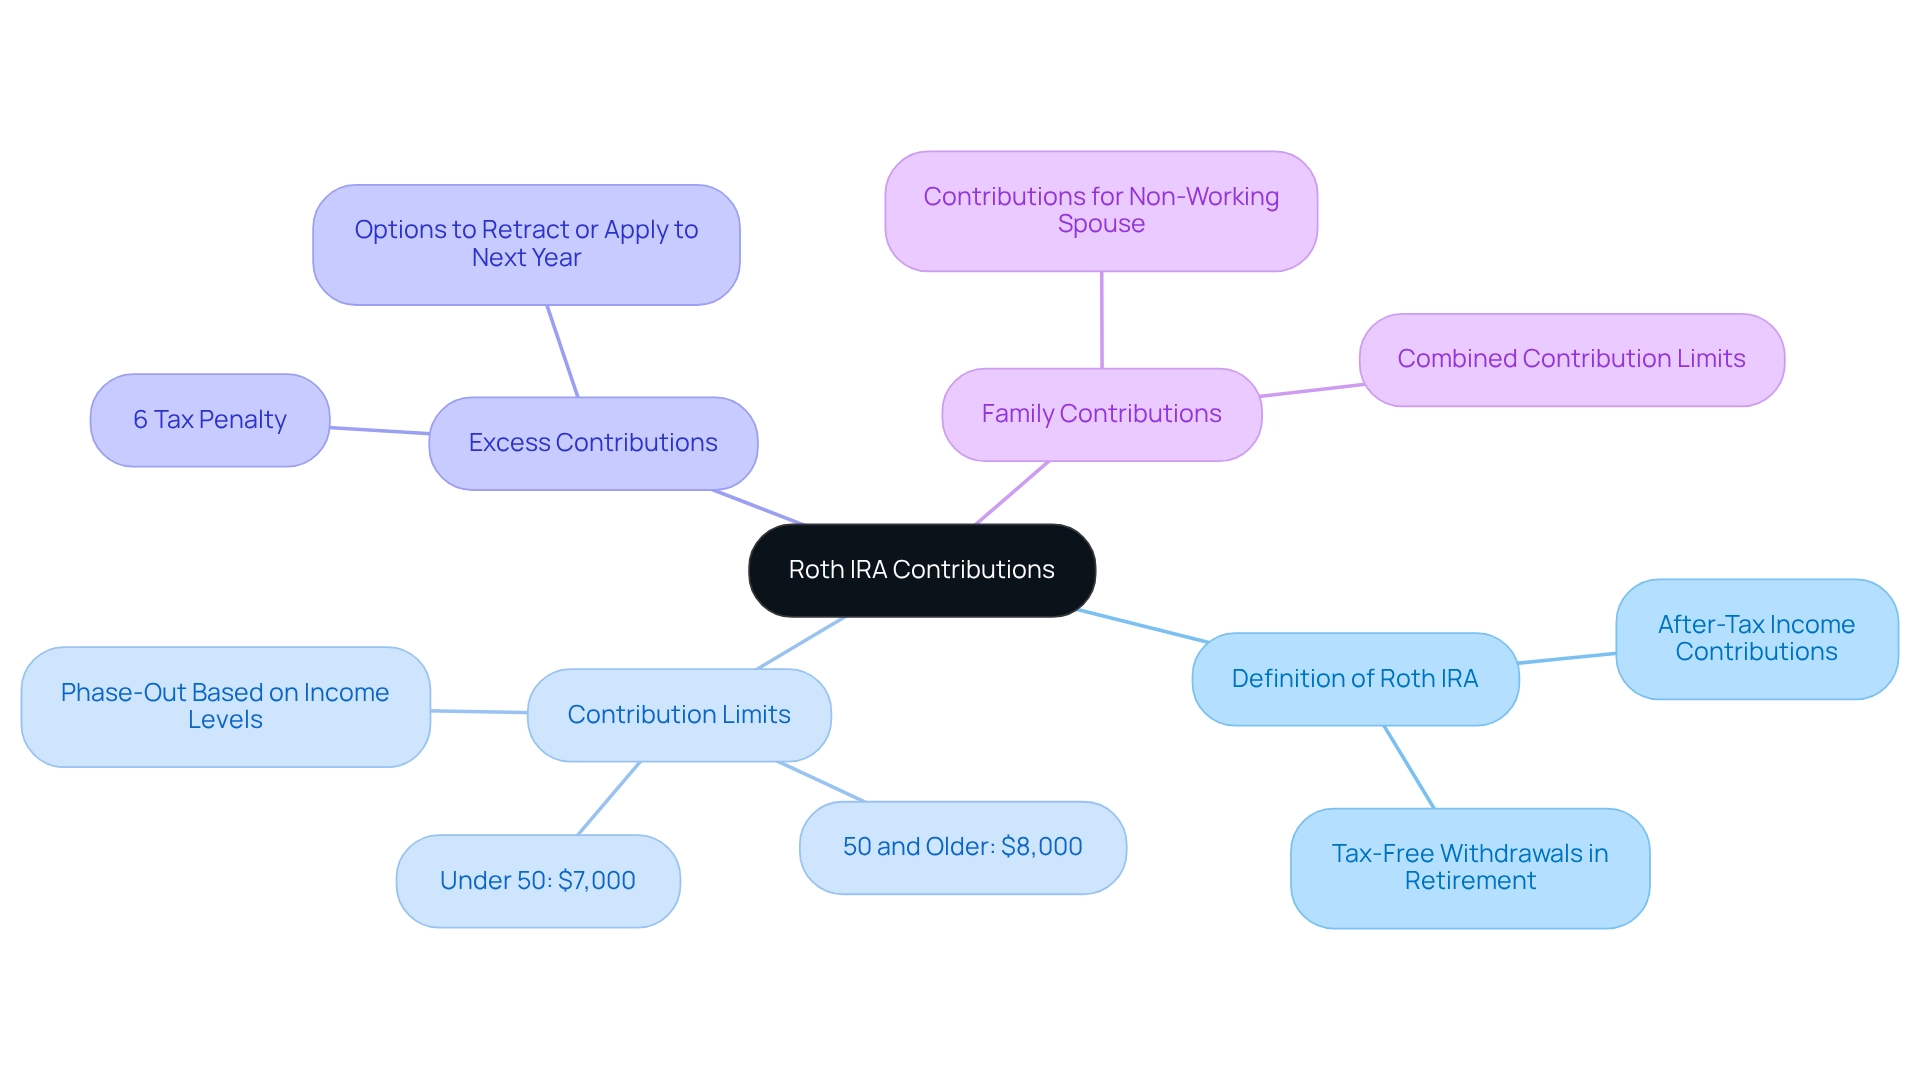
A Roth IRA (Individual Retirement Account) is a type of retirement savings account that allows individuals to contribute after-tax income. This means that the funds you deposit have already been taxed. The primary benefit of a Roth IRA is that qualified withdrawals during retirement are tax-free, as long as certain conditions are met. For the tax year 2025, the maximum contribution limit for a Roth IRA is $7,000 for individuals under 50, and $8,000 for those aged 50 and older, which includes catch-up contributions. It’s important to note that these contribution limits may phase out depending on income levels, which can affect eligibility for higher earners.
These thresholds are crucial for anyone planning their retirement savings. It is important to understand what happens if you exceed the Roth IRA contribution limit, as this can lead to penalties and tax implications. Specifically, what happens if you exceed Roth IRA contribution limit is that the IRS imposes a 6% tax penalty on the excess amount for each year it remains in the account. To help avoid this risk, individuals can either retract the excess contributions before filing their tax return or apply them toward the following year’s limit.
Additionally, families should be aware that they can contribute to an IRA for a non-working spouse, but the total combined contribution cannot exceed their joint taxable income or double the annual IRA maximum, whichever is lower. This highlights the importance of being mindful of contribution limits, especially for young families looking to secure their financial future.
At Bright Advisers, we’re here for you. We provide tailored wealth management solutions and work to minimize fund fees, making it easier for families to navigate retirement planning and achieve financial security. We offer educational resources to empower families to understand their options and make informed decisions about their retirement savings. Together, we can navigate this journey toward a brighter financial future.
Explore Consequences of Exceeding Contribution Limits
If you want to know what happens if you exceed the Roth IRA contribution limit, it can lead to a 6% excise tax on any excess contributions for each year it remains uncorrected. It’s crucial to understand that this tax on surplus payments cannot exceed 6% of the total value of all IRAs at the end of the tax year. This penalty can accumulate over time, resulting in significant financial consequences if not addressed promptly.
Imagine if you contributed $8,000 instead of the allowed $7,000. You would face a $60 penalty for that tax year. Moreover, if the surplus payment isn’t corrected, it could lead to further tax implications, including possible income tax on any profits generated from those excess funds, highlighting what happens if you exceed the Roth IRA contribution limit. Consider this: individuals often wonder what happens if you exceed the Roth IRA contribution limit, as they may face not just the excise tax but also challenges in their overall tax situations. This highlights the importance of being diligent with your contributions. Thankfully, there are options available. You can withdraw excess payments before filing your tax return or apply them toward the next year’s limit, which may help ease some penalties.
Additionally, you can recharacterize surplus deposits by transferring them from a Roth IRA to a traditional IRA, providing another avenue for correction. As we approach 2025, it’s essential to be aware that the IRS is enforcing these penalties more stringently. Therefore, it’s vital for account holders to monitor their deposits closely to avoid these costly penalties and ensure their retirement savings remain secure. Remember, we’re here for you, guiding you through these financial decisions for your family’s future.

Corrective Actions for Excess Contributions
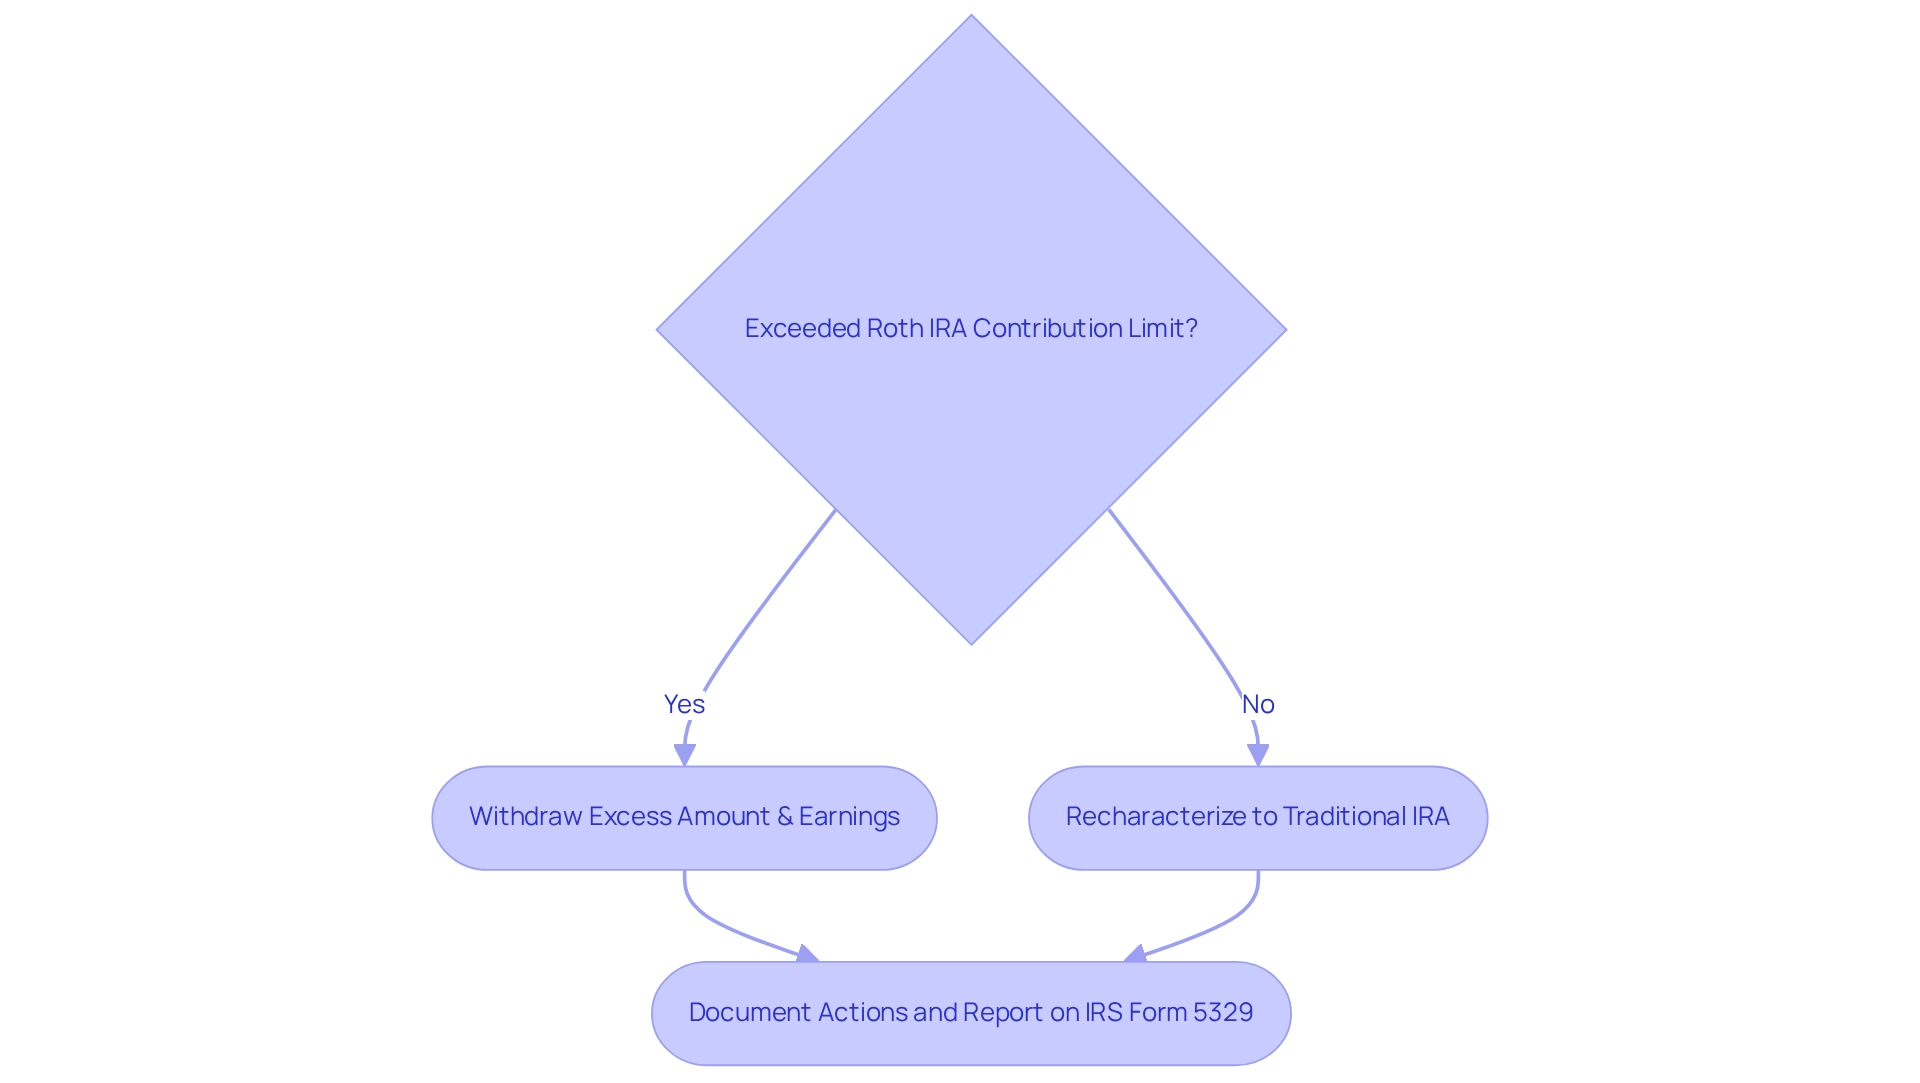
If you’ve found yourself making excessive payments to a Roth IRA, you may be curious about what happens if you exceed the Roth IRA contribution limit, but know that you’re not alone, and there are options available to help you. One of the simplest paths is to withdraw the excess amount along with any earnings generated before the tax filing deadline, including extensions. This proactive step can help you avoid the 6% penalty that can weigh heavily on your finances.
Imagine realizing what happens if you exceed the Roth IRA contribution limit. According to Bankrate, a trusted resource for financial guidance for over four decades, acting quickly can minimize penalties and keep your retirement savings on track. Alternatively, if you meet the eligibility requirements, you might consider recharacterizing the excess deposit by transferring it to a traditional IRA.
It’s crucial to document these corrective actions properly and report them on IRS Form 5329 to prevent future complications. As Jeff Witz, CFP, wisely points out, “Some people do not catch their error for years. This can be an expensive mistake, but you will always have the option of taking the money out and correcting the error.” Taking timely corrective measures can empower you to manage your retirement accounts effectively and minimize tax liabilities.
Consider a situation where someone added to their Roth IRA while having an income too high to be eligible for deposits. This highlights what happens if you exceed the Roth IRA contribution limit, emphasizing the importance of being vigilant in monitoring contributions and the need for timely corrective actions. Remember, you’re not alone in this journey; together, we can navigate these financial challenges and ensure a brighter future for your family.
Impact on Future Contributions and Tax Planning
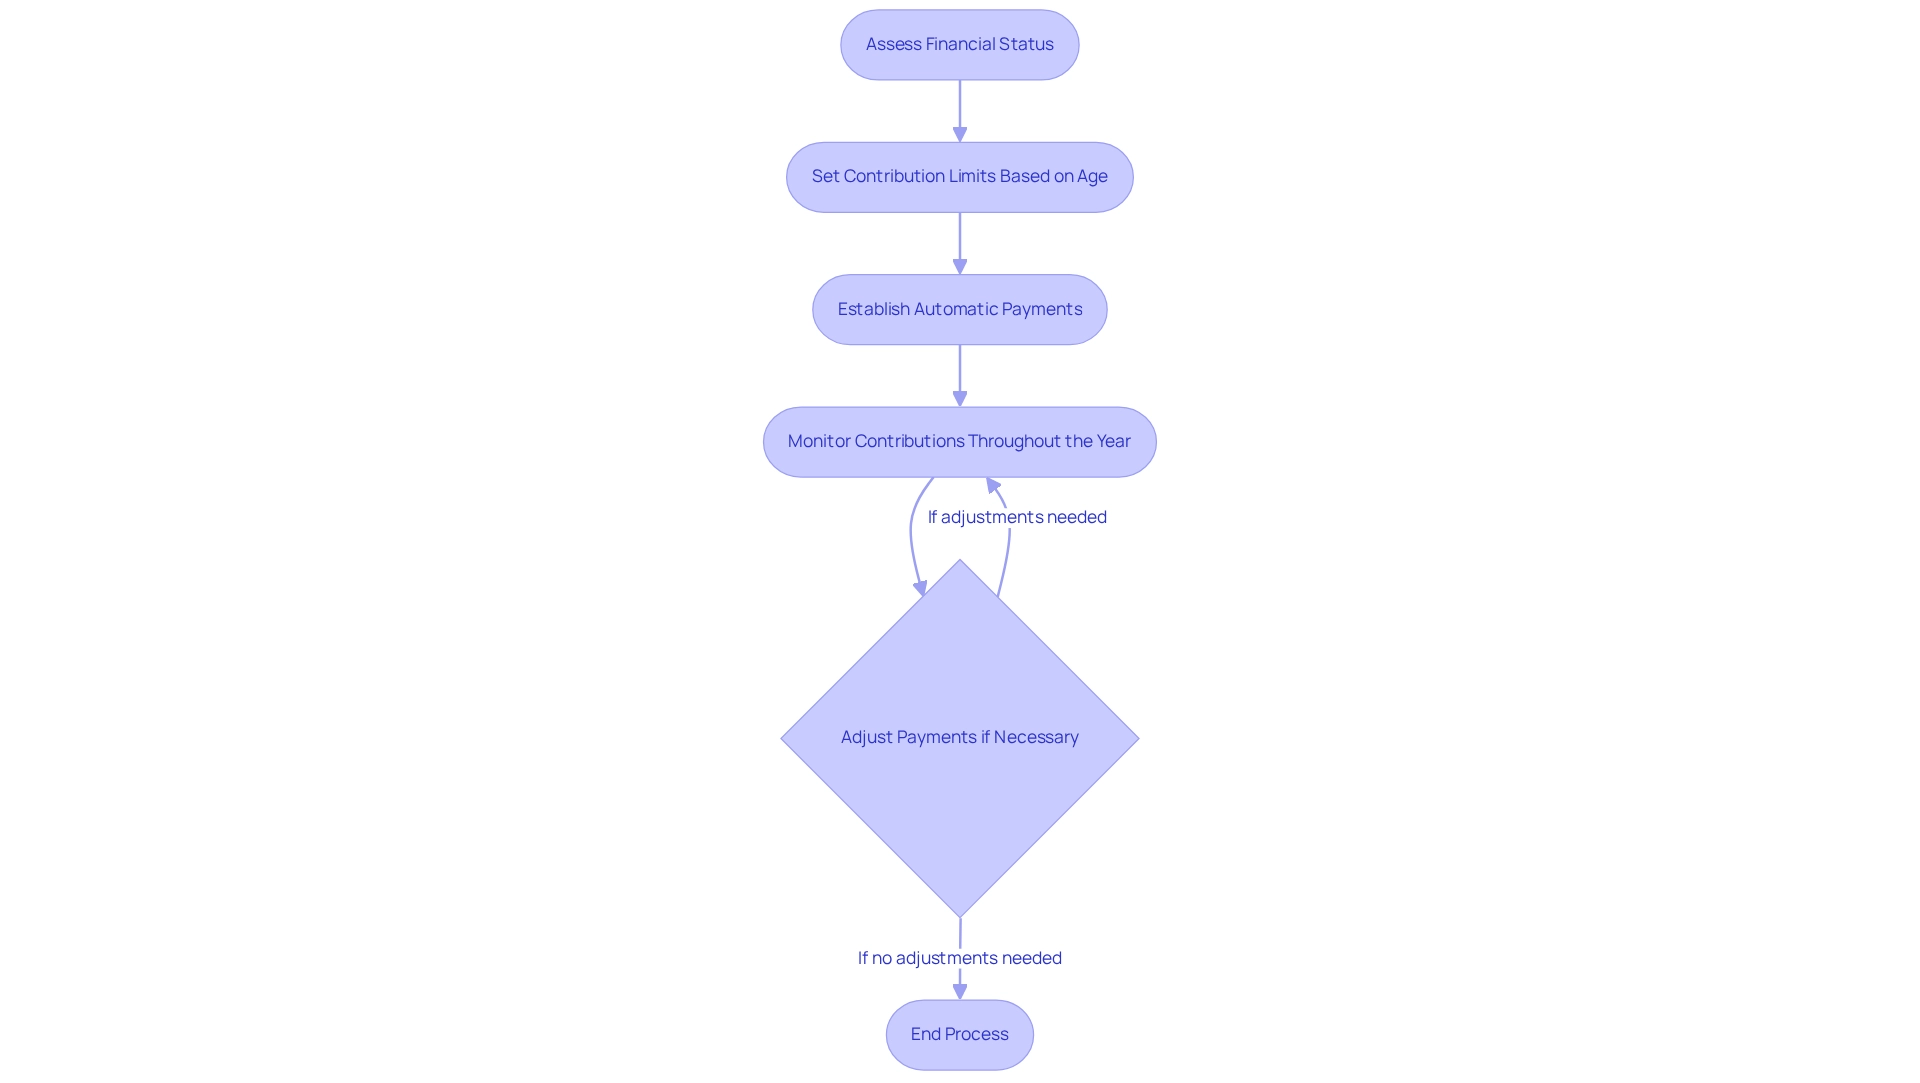
Preventing additional deposits to a Roth IRA requires thoughtful planning and ongoing attention. Imagine setting up automatic payments that align perfectly with the annual limits—this strategy ensures that your contributions remain within the acceptable thresholds. For 2025, individuals aged 50 and older can contribute a maximum of $8,000. It’s essential to establish your payments accordingly to stay on track.
It’s important to frequently assess your income and financial status, especially if you anticipate changes that could impact your eligibility for full support. By staying proactive, you can avoid any surprises down the road. Seeking advice from a financial consultant or utilizing financial planning resources can provide valuable insights into your contribution limits and clarify what happens if you exceed the Roth IRA contribution limit, helping you implement necessary adjustments throughout the year. Remember, together, we can navigate this journey toward a secure financial future for your family.
Common Misconceptions About Roth IRA Contributions
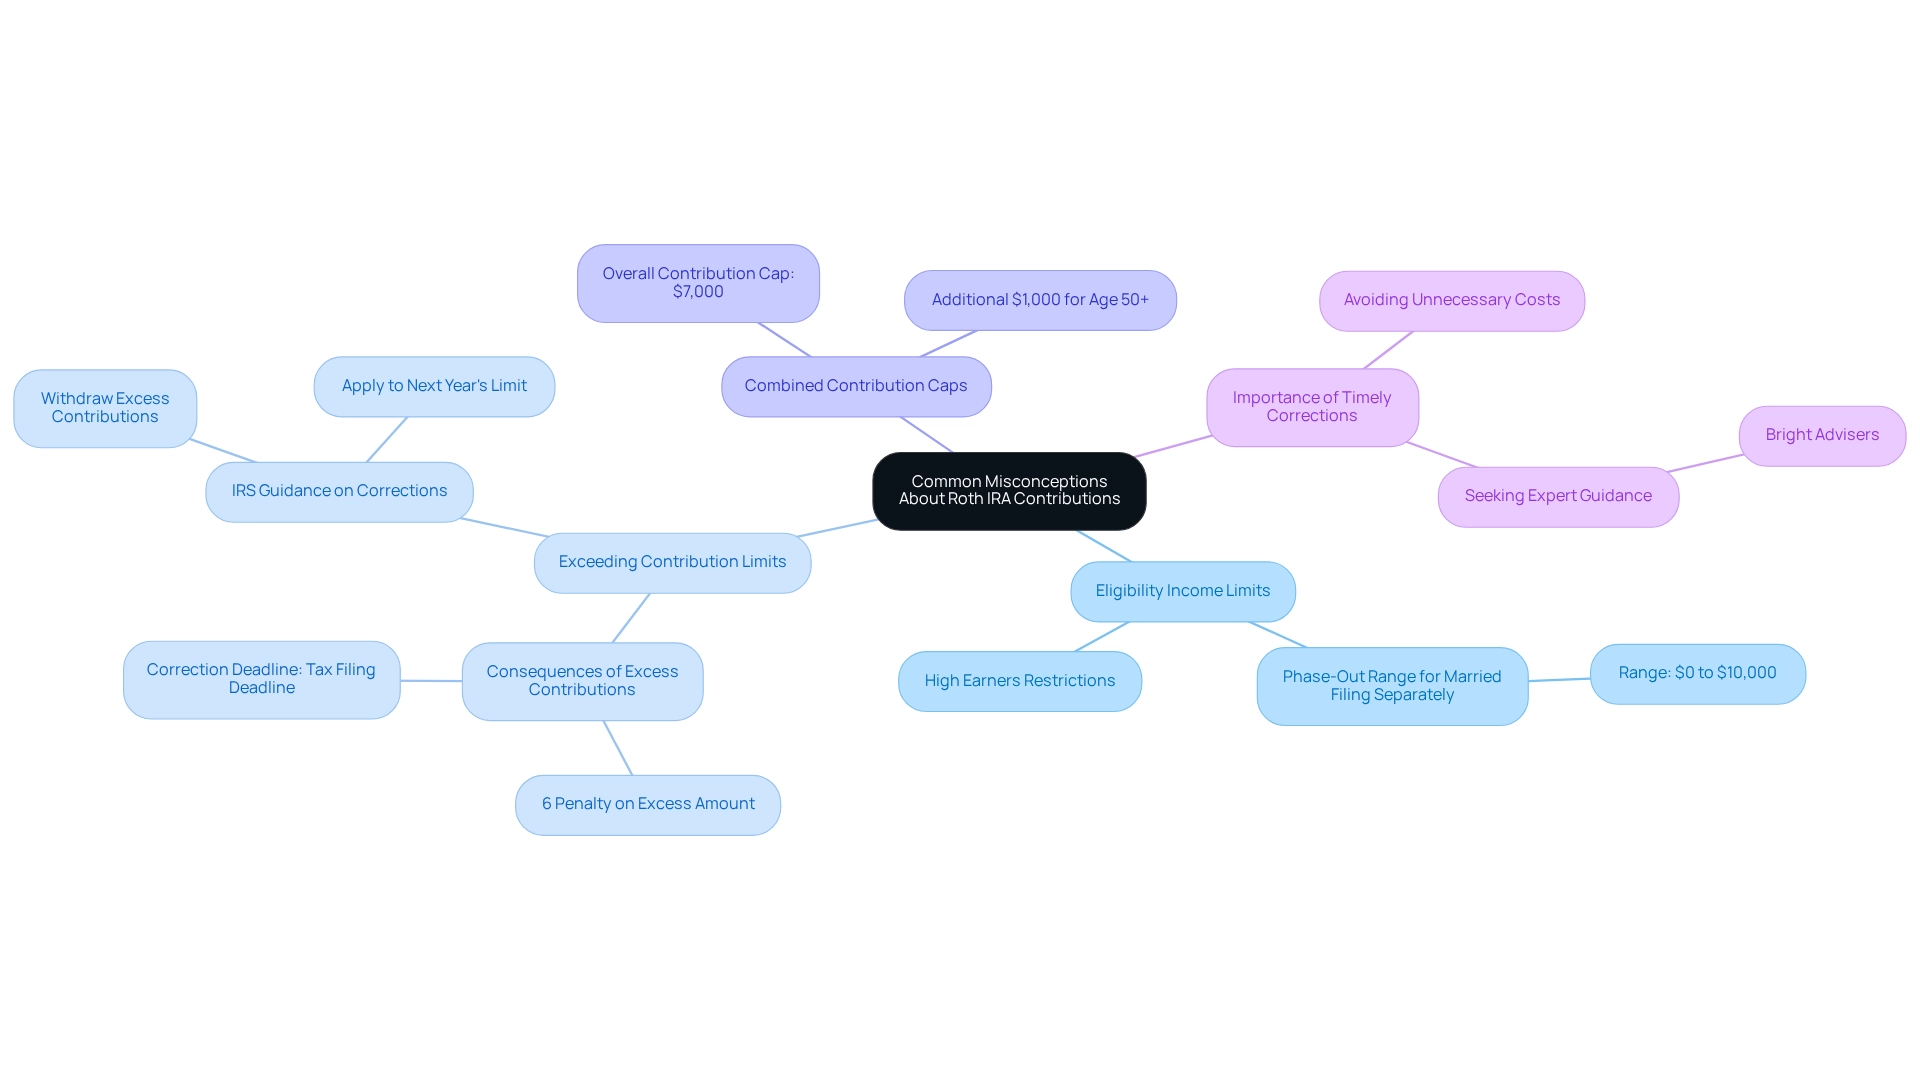
Misunderstandings regarding Roth IRA deposits can lead to costly mistakes for families. It’s a common misconception that anyone can contribute to a Roth IRA, no matter their income. In reality, specific income limits phase out eligibility, particularly for high earners. For 2025, the phase-out range for married individuals filing separately is $0 to $10,000, which significantly restricts contributions for those in this category.
Another frequent misunderstanding is about what happens if you exceed Roth IRA contribution limit, as individuals may mistakenly believe they can withdraw excess contributions without any consequences. While it’s possible to correct surplus payments, failing to do so before the tax filing deadline can lead to the consequences of what happens if you exceed Roth IRA contribution limit, including a 6% penalty on the excess amount if it remains in the account. The Internal Revenue Service states, “If you accidentally contributed too much to your Roth IRA or contributed when you were ineligible, you have until your tax filing deadline (extensions included) to correct the issue.” This emphasizes the importance of acting promptly to avoid unnecessary costs.
Moreover, many people mistakenly think they can contribute to both a Roth IRA and a traditional IRA without considering the total combined limits. Understanding that the overall contribution cap for both accounts is $7,000 for 2025 (or $8,000 if you’re age 50 or older) is crucial to avoid exceeding allowable thresholds, which can complicate financial planning.
For young families, grasping these nuances is vital for effective financial management. Imagine a couple, Jay and Emma, who initially believed they could contribute to both accounts without restrictions. After consulting with Bright Advisers, they learned about the joint funding limits and adjusted their strategy accordingly, steering clear of potential penalties.
Families should be aware of what happens if you exceed Roth IRA contribution limit, along with the implications of income limits on Roth IRA eligibility and the possible penalties associated with excess contributions. By staying informed and seeking guidance from experts like Bright Advisers, they can make informed decisions that align with their long-term financial goals. Bright Advisers offers tailored wealth management solutions to help families navigate these complexities, empowering them to achieve financial security and freedom through personalized planning and tax optimization. Together, we can navigate this journey—reach out to Bright Advisers today to ensure your financial strategies are aligned with your goals.
Conclusion
Understanding the intricacies of Roth IRA contributions is essential for effective retirement planning. Imagine navigating your financial future with confidence, knowing you’re making the best choices for your family. This article delves into key aspects such as the definition of excess contributions, the consequences of exceeding limits, corrective actions available, and common misconceptions that can lead to costly mistakes. With contribution limits set to change in 2025, it’s important for individuals and families to stay vigilant in monitoring their contributions to avoid incurring penalties that could significantly impact their financial future.
Timely corrective actions, such as withdrawing excess contributions or recharacterizing them, can help mitigate penalties and ensure that your retirement savings remain intact. It’s crucial to stay informed about income limits and the implications they carry, especially for high earners. By adopting strategies like automatic contributions and regularly reviewing your financial circumstances, you can optimize your retirement planning and steer clear of complications associated with excess contributions.
In conclusion, navigating the rules surrounding Roth IRA contributions is vital for anyone looking to secure their financial future. By understanding the regulations, recognizing potential pitfalls, and taking proactive measures, you can effectively manage your retirement savings. Together, we can navigate this journey. Empowering yourself with knowledge and seeking guidance from financial experts can pave the way for informed decisions that resonate with your family values, ultimately leading to a more secure and prosperous retirement.
Frequently Asked Questions
What is a Roth IRA?
A Roth IRA (Individual Retirement Account) is a retirement savings account that allows you to invest after-tax income. This means the funds come from money that has already been taxed, and qualified withdrawals during retirement are tax-free, provided certain conditions are met.
What are the contribution limits for a Roth IRA in 2025?
For the tax year 2025, you can contribute up to $7,000 if you’re under 50 years old, and $8,000 if you’re 50 or older, which allows for catch-up savings.
How do income levels affect Roth IRA contribution limits?
Contribution limits for a Roth IRA can phase out based on income levels, which may affect eligibility for higher earners. It’s important to understand these thresholds for effective retirement planning.
What happens if I exceed the Roth IRA contribution limit?
If you exceed the Roth IRA contribution limit, the IRS imposes a 6% tax penalty on the excess amount for each year it remains in the account. To avoid this penalty, you should withdraw any excess amounts before filing your tax return or apply them toward next year’s limit.
Can I contribute to a Roth IRA for a non-working spouse?
Yes, you can contribute to an IRA for a non-working spouse, but the total combined contribution cannot exceed your joint taxable income or twice the annual IRA limit, whichever is lower.
Why is it important to stay informed about Roth IRA funding limits?
Staying informed about funding limits is crucial, especially for young families eager to secure their financial future, as it helps in effective retirement planning and avoiding penalties.
List of Sources
- Define Excess Roth IRA Contributions
- Roth IRA income and contribution limits for 2025 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)
- 2023 – 2024 Roth IRA Contribution Limits (https://schwab.com/ira/roth-ira/contribution-limits)
- Roth IRA Income & Contribution Limits for 2025 – NerdWallet (https://nerdwallet.com/article/investing/roth-ira-contribution-limits)
- Roth IRA contribution and income limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/roth-ira-contribution-limits)
- It’s Official: The 2025 Roth IRA Contribution Limits Are Here (https://nasdaq.com/articles/its-official-2025-roth-ira-contribution-limits-are-here)
- Explore Consequences of Exceeding Contribution Limits
- Retirement topics – IRA contribution limits | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-ira-contribution-limits)
- Roth IRA income and contribution limits for 2025 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)
- What Happens If You Exceed the Roth IRA Income Limit? (https://smartasset.com/retirement/what-happens-if-you-exceed-roth-ira-income-limit)
- How to Deal with Excess IRA Contributions | MissionSquare (https://missionsq.org/products-and-services/iras/excess-ira-contributions.html)
- IRA Excess Contribution When Expats Claim The FEIE (https://onlinetaxman.com/ira-excess-contributions-when-using-feie)
- Money Matters: Removing excess Roth IRA contributions (https://urologytimes.com/view/money-matters-removing-excess-roth-ira-contributions)
- Corrective Actions for Excess Contributions
- What To Do If You Contributed Too Much To Your IRA Last Year | Bankrate (https://bankrate.com/retirement/excess-ira-contributions)
- I made an excess contribution to my Roth IRA; how do I fix it? (https://urologytimes.com/view/i-made-excess-contribution-my-roth-ira-how-do-i-fix-it)
- Money Matters: Removing excess Roth IRA contributions (https://urologytimes.com/view/money-matters-removing-excess-roth-ira-contributions)
- Roth IRA Contribution Limits for 2025: Your Guide to Retirement Savings – What You Need to Learn (https://m.arktimes.com/roth-ira-contribution-limits-for-2025-your-guide-to-retirement-savings)
- Correcting excess contributions to IRAs (https://thetaxadviser.com/issues/2020/apr/correcting-excess-contributions-iras)
- Excess IRA Contributions | Rules & Options | Fidelity Investments (https://fidelity.com/retirement-ira/excess-ira-contributions)
- How to Calculate (and Fix) Excess IRA Contributions (https://investopedia.com/articles/retirement/04/042804.asp)
- Impact on Future Contributions and Tax Planning
- 2023 – 2024 Roth IRA Contribution Limits (https://schwab.com/ira/roth-ira/contribution-limits)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Correcting excess contributions to IRAs (https://thetaxadviser.com/issues/2020/apr/correcting-excess-contributions-iras)
- What To Do If You Contributed Too Much To Your IRA Last Year | Bankrate (https://bankrate.com/retirement/excess-ira-contributions)
- Common Misconceptions About Roth IRA Contributions
- IRS Unveils Increased 2025 IRA Contribution Limits (https://theentrustgroup.com/blog/ira-contribution-limits)
- Roth IRA income and contribution limits for 2025 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)
- Roth IRA income limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/roth-ira-income-limits)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading