

Key Highlights:
- For tax year 2026, contribution limits are $7,500 for individuals under 50 and $8,600 for those aged 50 and older, applicable to both Roth and traditional IRAs.
- Excess contributions to a Roth IRA incur a 6% tax penalty on the surplus for each year it remains uncorrected.
- To avoid penalties, individuals can withdraw surplus contributions and earnings before filing taxes or apply excess contributions to the following year’s limit.
- Over-contributing can lead to unexpected tax liabilities, especially if earnings on excess contributions are not promptly withdrawn.
- Keeping detailed records of contributions, using tax planning software, and consulting financial advisors can help manage contributions effectively.
- Roth IRA withdrawals are tax-free in retirement, while traditional IRA withdrawals are subject to ordinary income tax, complicating long-term tax planning.
- Early withdrawals from a Roth IRA before age 59½ may incur a 10% federal penalty on contributions and earnings.
Introduction
Navigating the world of retirement savings can feel overwhelming, especially for parents who want to ensure their family’s financial future. Imagine the peace of mind that comes with knowing you’re making the right choices for your loved ones.
With Roth IRA contribution limits set at $7,500 for those under 50 and $8,600 for older contributors in 2026, it’s crucial to stay informed. Exceeding these limits can lead to penalties, including a 6% excise tax on any surplus amounts. This can quickly add up, putting a strain on your financial plans.
It’s important to understand how to avoid these pitfalls while maximizing your retirement savings. Picture a future where your family is secure, and you can focus on what truly matters – creating memories together. By taking the time to learn about these complexities, you can navigate them with confidence.
We’re here for you, ready to support you on this journey. Together, we can explore the best strategies to ensure your family’s financial well-being. Let’s make the most of your retirement savings, so you can enjoy peace of mind today and in the years to come.
Define Over-Contribution to Roth IRAs
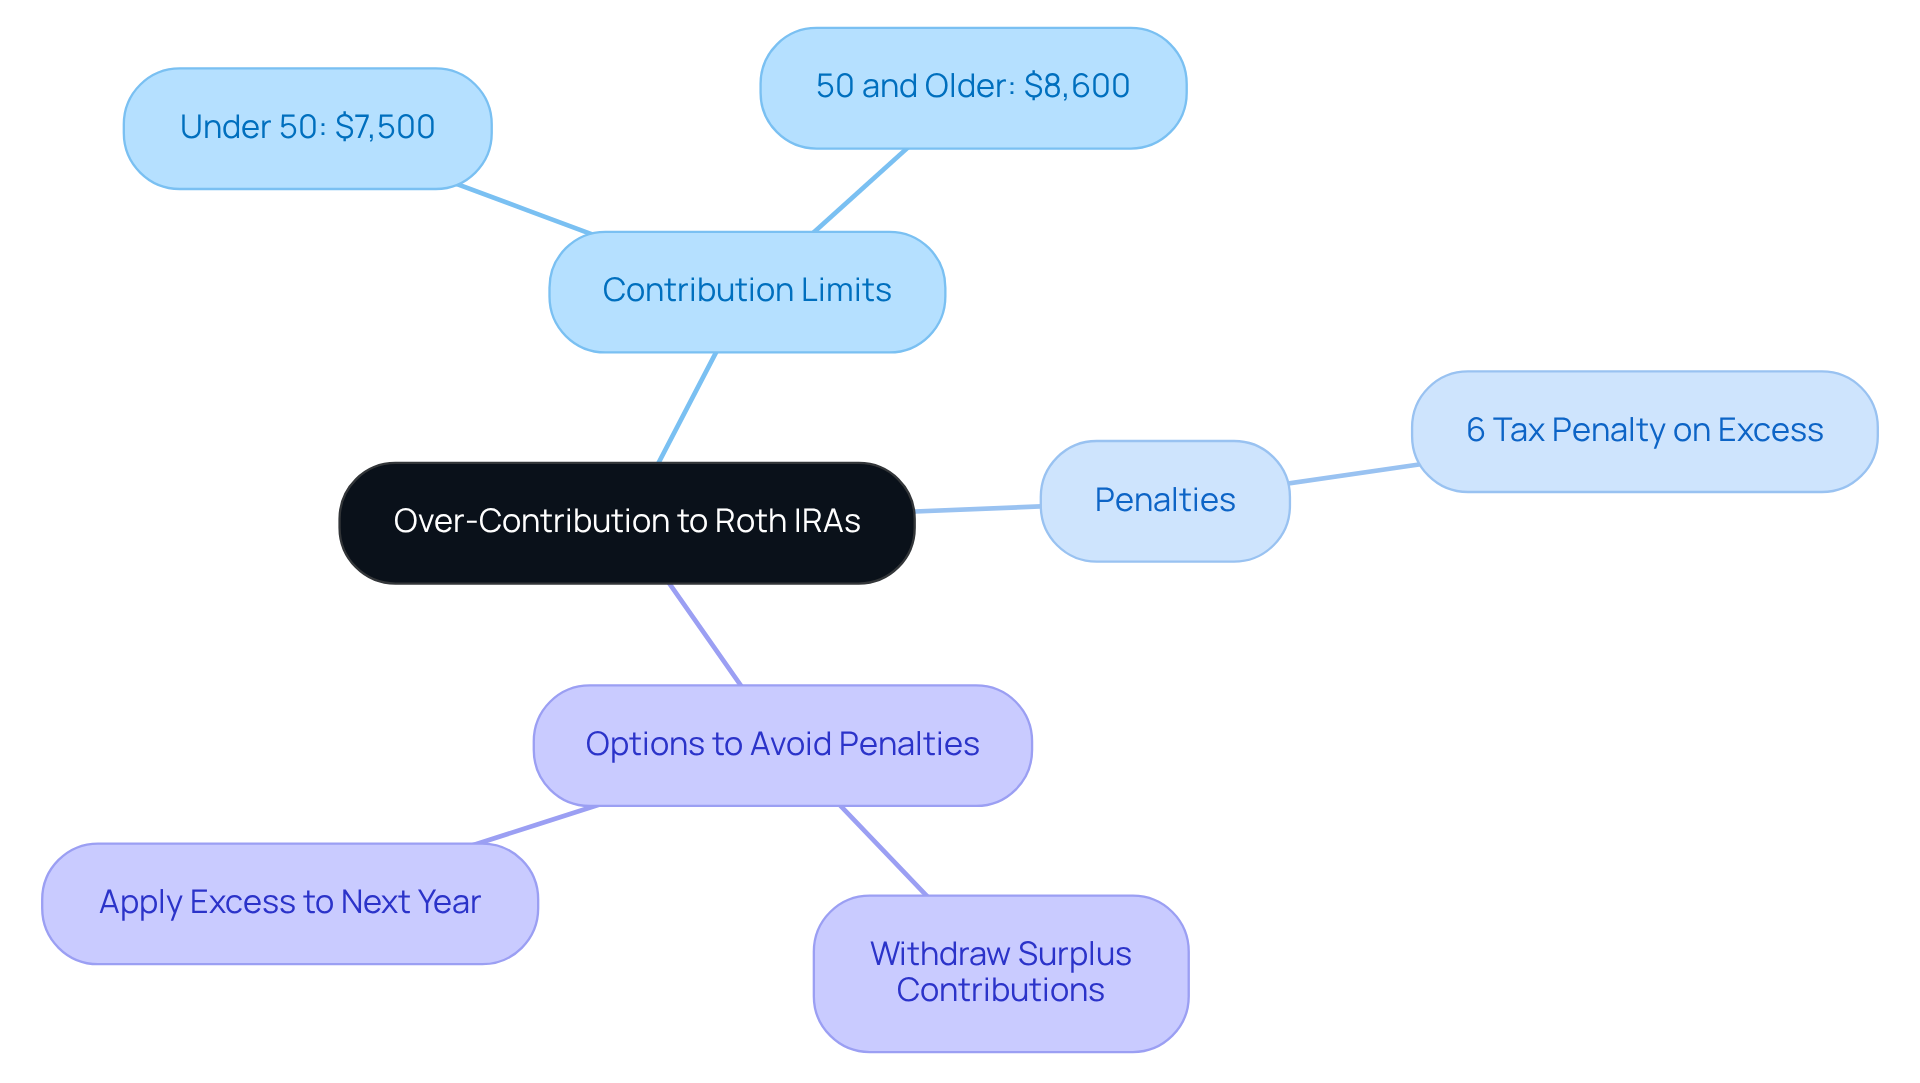
Are you aware of what happens if you over contribute to Roth IRA? It’s a concern that many parents face, especially when trying to save for their family’s future. For the tax year 2026, the IRS has set the contribution limits at $7,500 for individuals under 50 and $8,600 for those aged 50 and older. This total includes contributions to both Roth and traditional IRAs.
Imagine what happens if you over contribute to Roth IRA by accidentally exceeding these limits. If you want to know what happens if you over contribute to Roth IRA, the excess amount is classified as an overage, which could lead to a 6% tax penalty on that surplus for every year it remains in your account. That’s a hefty price to pay when you’re trying to secure your family’s financial future!
To avoid these penalties, it’s crucial to understand your options. You can:
- Withdraw any surplus contributions and their earnings before filing your tax return
- Apply the excess toward the following year’s limit
This way, you can keep your retirement savings on track without unnecessary penalties.
Understanding these guidelines is vital for parents like you, who are striving to optimize retirement savings while ensuring a secure future for your loved ones. Remember, we’re here for you, guiding you through these financial decisions to help you navigate this journey together.
Explore Consequences of Over-Contribution
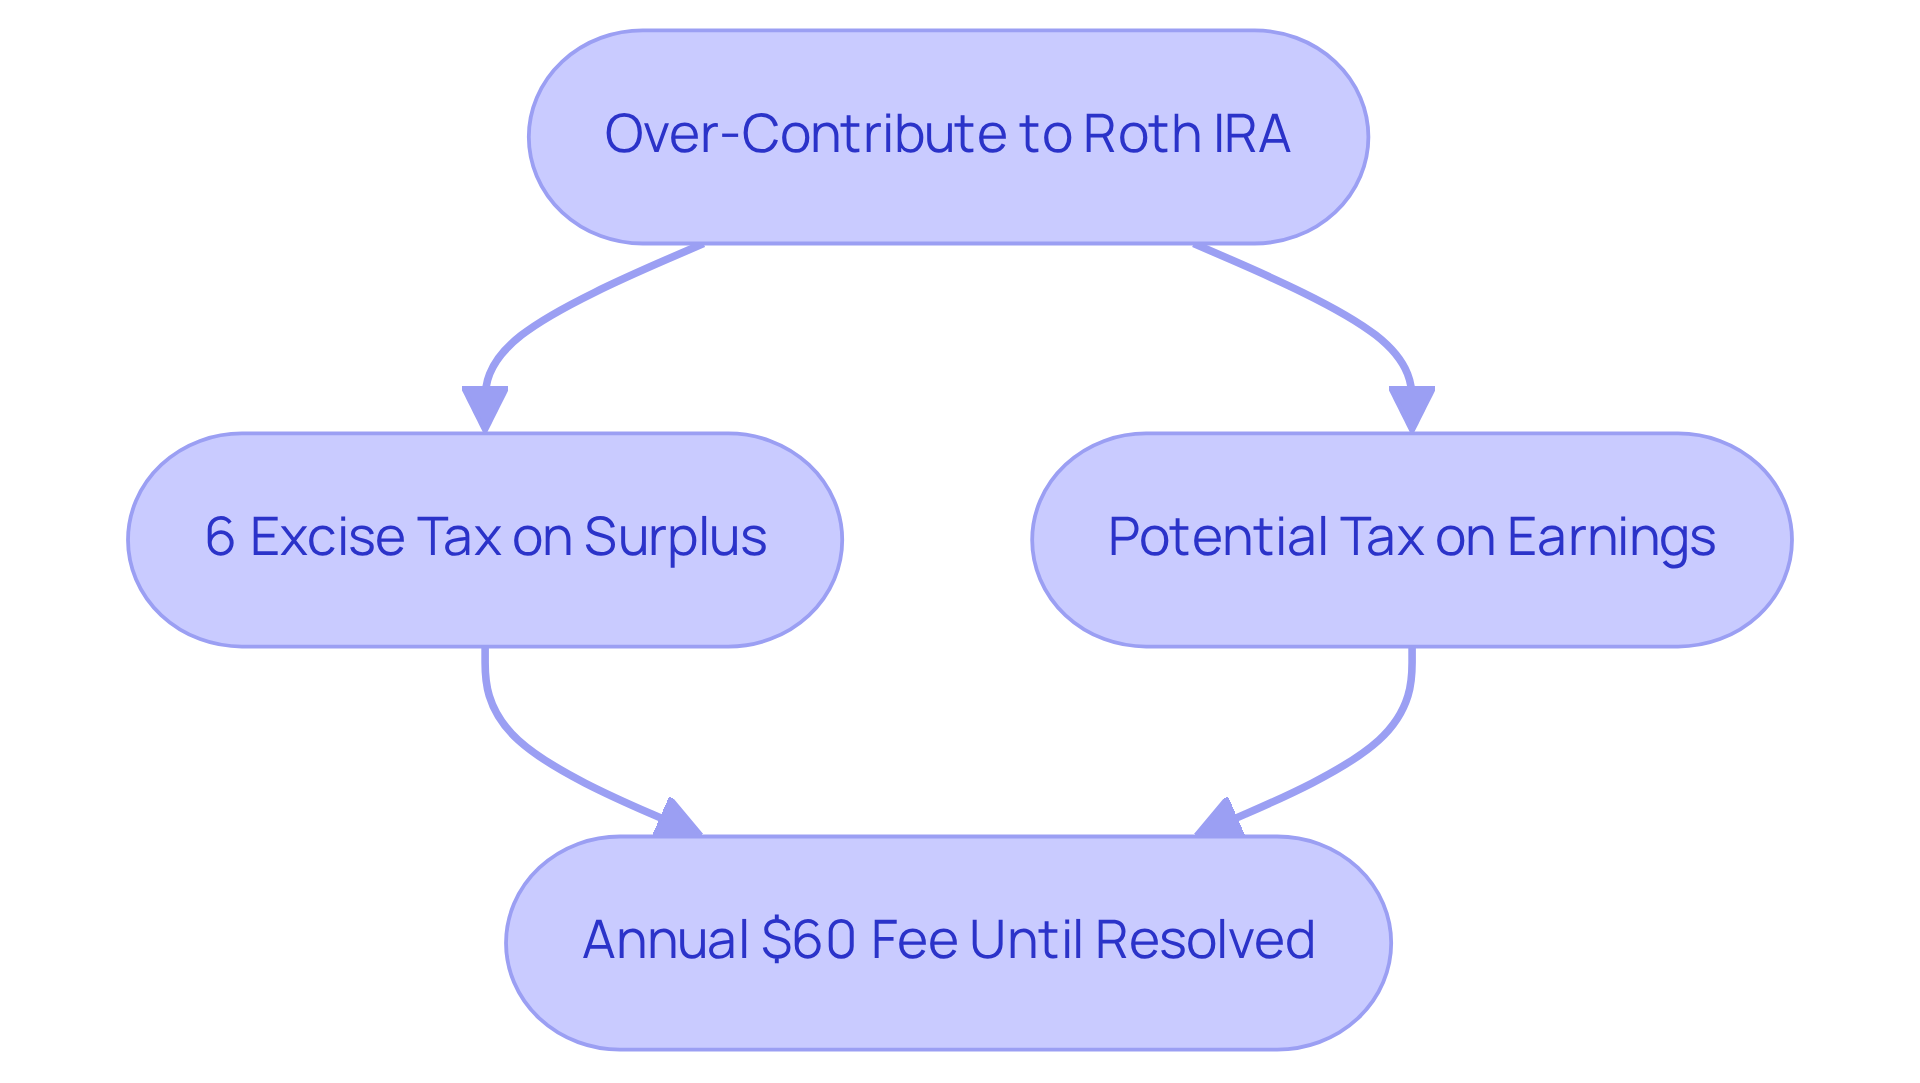
It is important to understand what happens if you over contribute to a Roth IRA, as this can lead to some unexpected challenges, and we want to help you navigate them with ease. Imagine what happens if you over contribute to a Roth IRA by mistakenly contributing $1,000 beyond the limit. This situation could lead to a on that surplus amount each year it remains uncorrected in your account, highlighting what happens if you over contribute to a Roth IRA. That’s a $60 fee each year until you resolve the issue.
It’s important to understand what happens if you over contribute to a Roth IRA, since any earnings from those extra contributions may also incur taxes if not withdrawn promptly. This could lead to unexpected tax liabilities, adding to your stress. We know how much you care about your family’s financial future, and this scenario underscores the importance of keeping a close eye on your contributions and taking timely corrective actions.
By understanding what happens if you over contribute to a Roth IRA, you can avoid unnecessary financial burdens and ensure your retirement savings remain intact. Together, we can navigate this journey and keep your family’s goals on track.
Identify Strategies to Prevent Over-Contribution
Navigating the world of Roth IRAs can feel overwhelming, especially for young parents trying to secure their family’s financial future. To help you avoid over-contributing, it’s important to understand [what happens if you over contribute to Roth IRA](https://ogletree.com/insights-resources/blog-posts/irs-issues-roth-catch-up-contribution-rules-for-highly-paid-participants), and there are several caring strategies you can adopt that align with your financial goals.
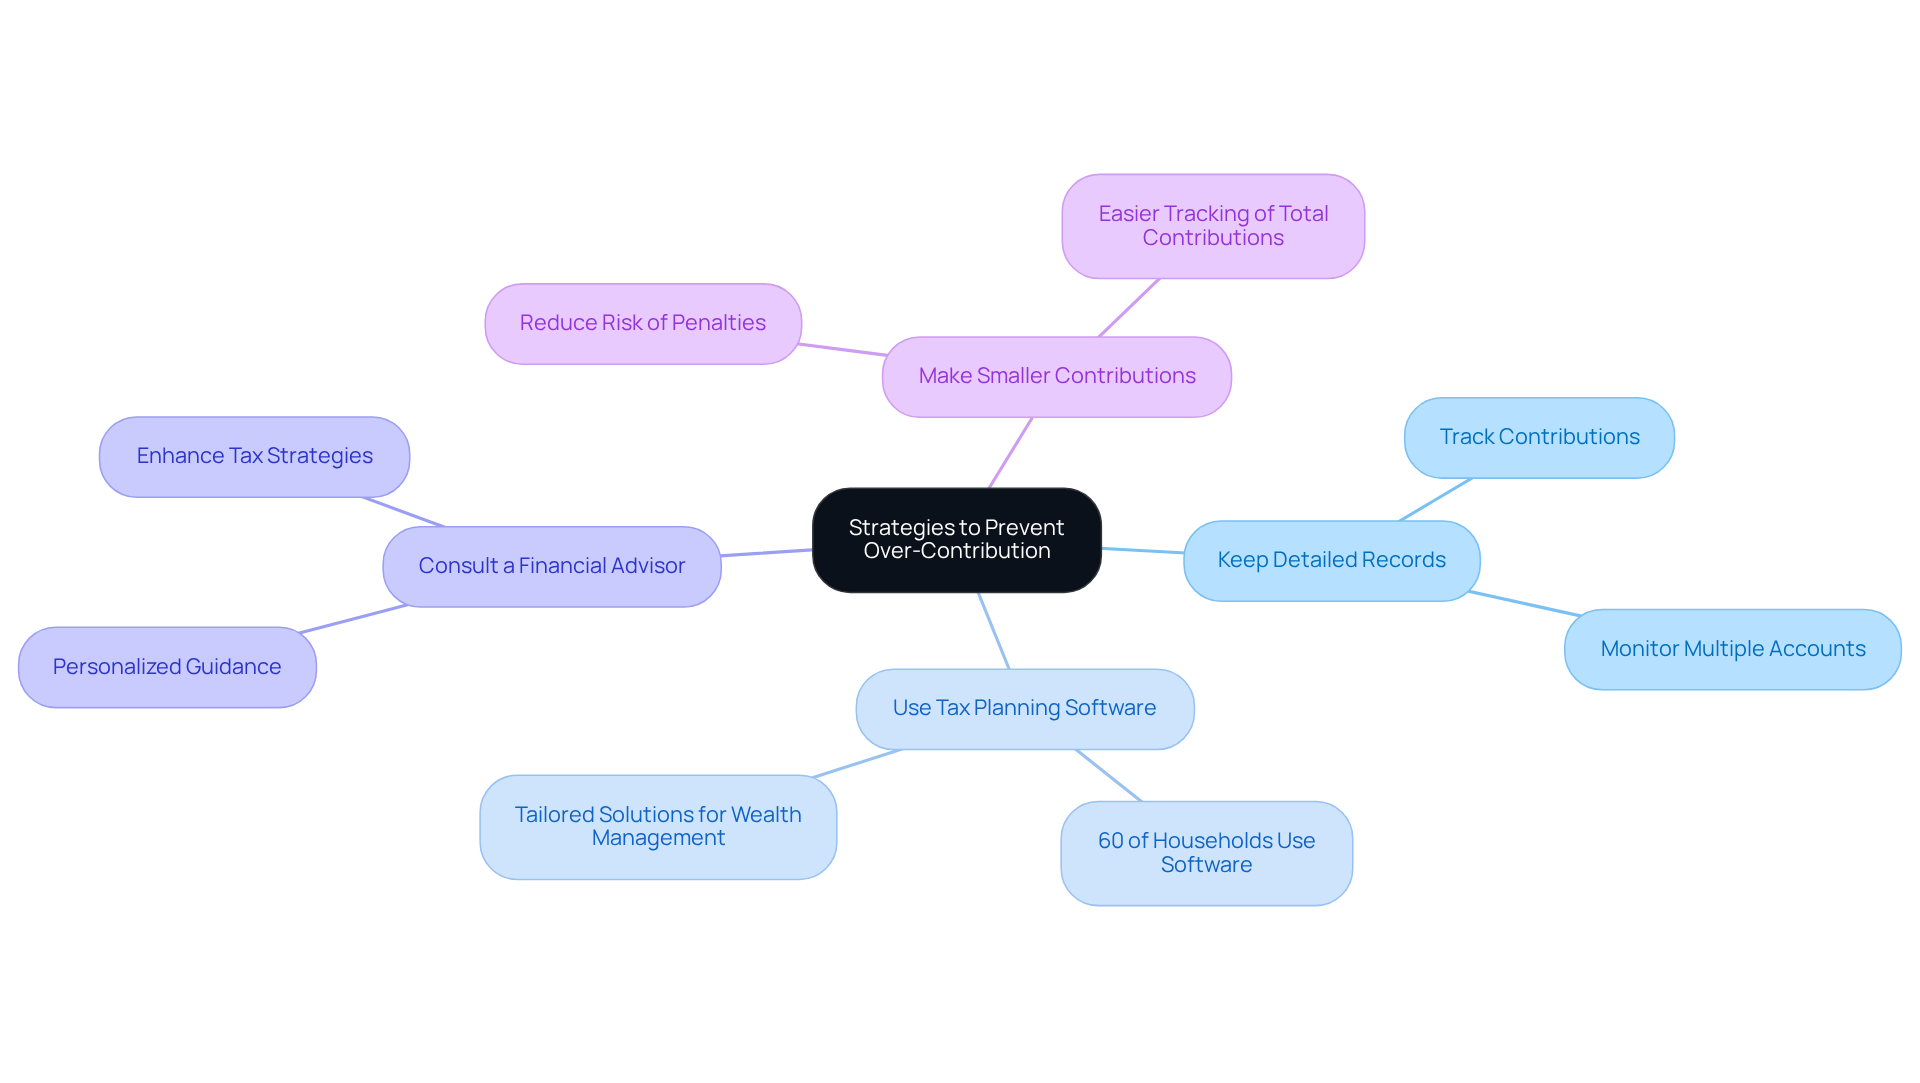
First, keeping a detailed record of your contributions throughout the year is crucial, particularly if you manage multiple accounts. While automatic payments can simplify your finances, it’s crucial to regularly check these amounts to understand what happens if you over contribute to Roth IRA and to ensure you don’t exceed the contribution limits. Imagine if you could simplify this process while still staying on track!
Interestingly, studies show that around 60% of households are now using tax planning software for IRA management. This growing trend highlights how many families are seeking tailored solutions to manage their wealth effectively. Consulting with a financial advisor, like those at Bright Advisers, can provide you with personalized guidance to help you stay within limits and enhance your tax strategies.
Additionally, consider making smaller contributions instead of one large payment. This approach not only helps you keep better track of your total contributions but also clarifies what happens if you over contribute to Roth IRA, thereby . As Jack and Diane wisely pointed out, “Following strategy one is like giving a $600k tip to the government!”
By embracing these strategies, you can confidently navigate the complexities of Roth IRA deposits. Remember, you’re not alone in this journey. Together, we can safeguard your financial future and empower your long-term aspirations.
Compare Over-Contribution Effects on Roth vs. Traditional IRAs
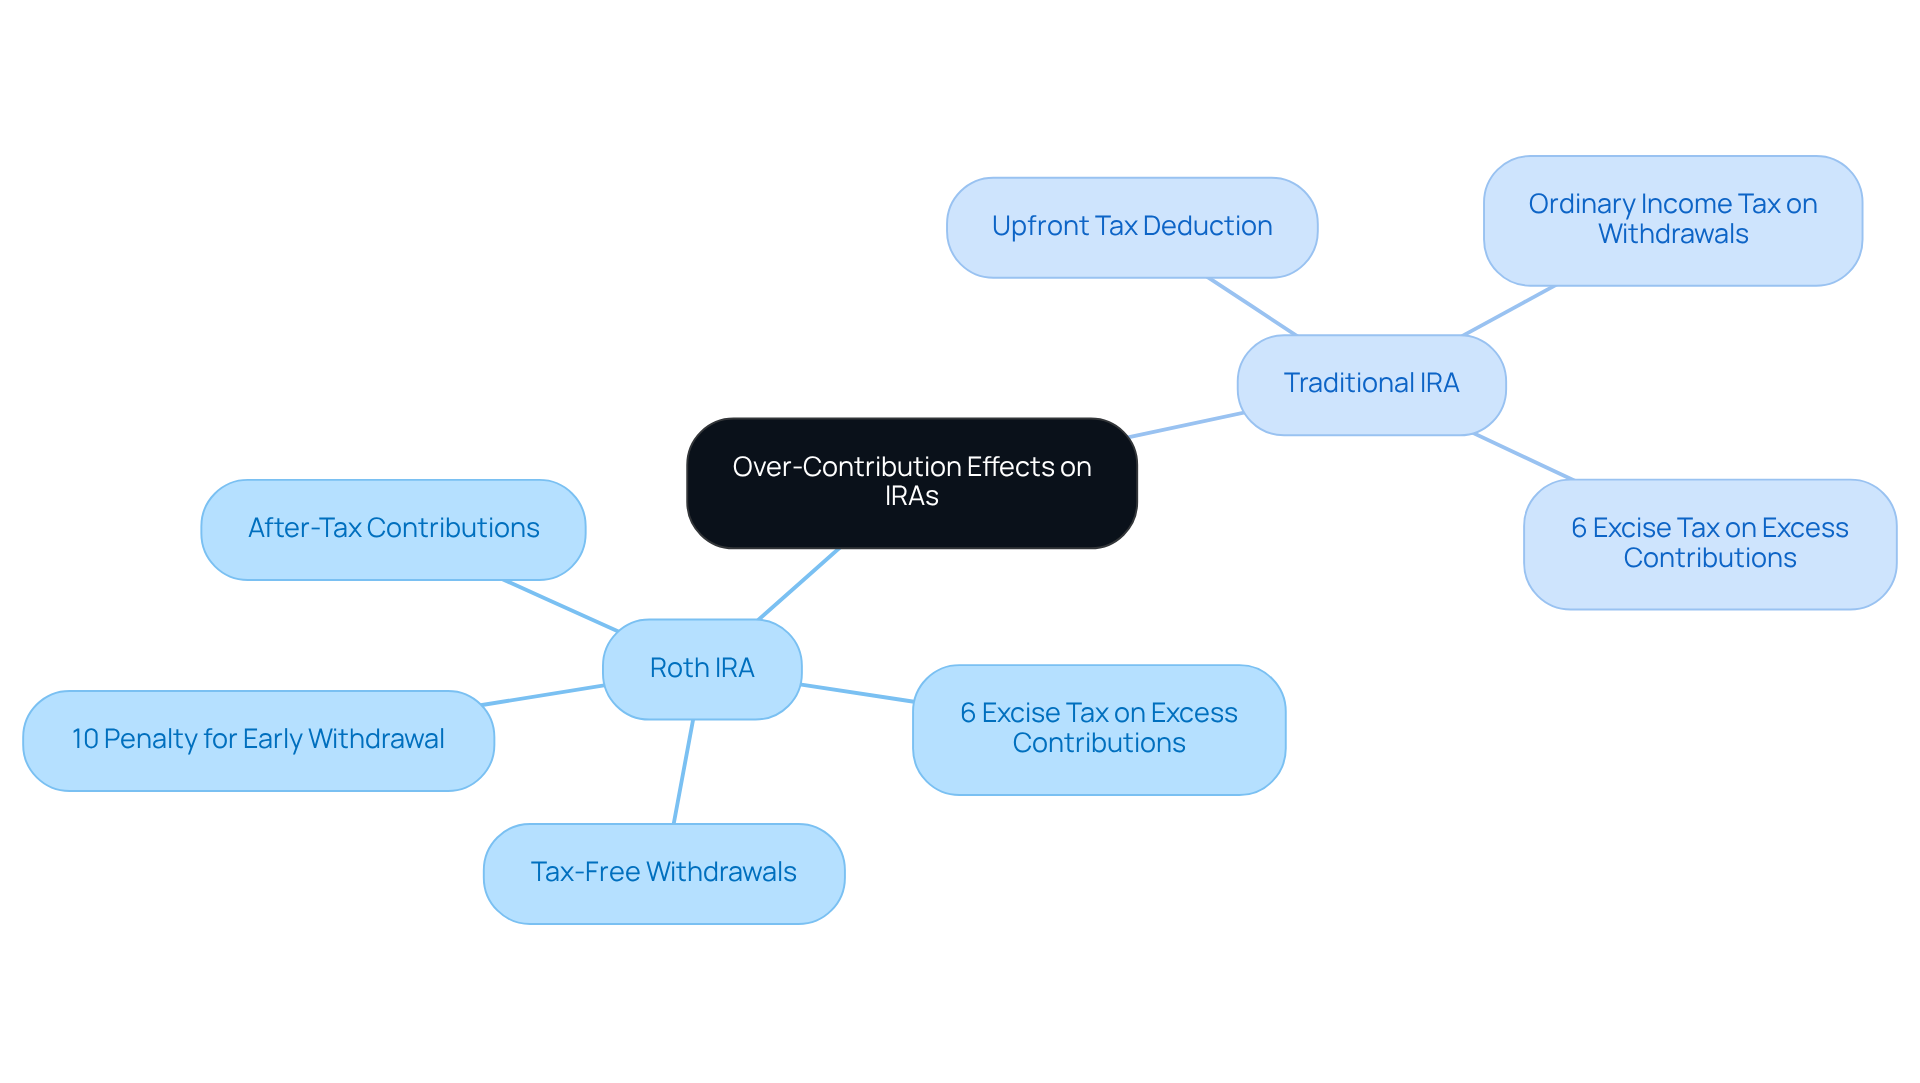
Navigating the world of IRAs can feel overwhelming, especially for young parents. Did you know what happens if you over contribute to Roth IRA, as excess payments to both Roth IRAs and traditional IRAs incur a 6% excise tax on the surplus amount? While this might sound daunting, understanding the can empower you to make better financial choices for your family.
Roth IRA contributions are made with after-tax dollars, which means that when it comes time to withdraw funds, those qualified withdrawals are tax-free. This can be a game-changer for families who anticipate being in higher tax brackets during retirement. Imagine the peace of mind knowing that your hard-earned savings can grow without the burden of future taxes.
On the other hand, traditional IRA contributions might offer an upfront tax deduction, but it’s crucial to remember that withdrawals are subject to ordinary income tax. This can complicate long-term tax planning, especially for parents who want to ensure their family’s financial security.
For parents, the stakes are even higher when it comes to understanding what happens if you over contribute to a Roth IRA. If you withdraw funds before age 59½, you could face a 10% federal penalty on both contributions and earnings. This adds another layer of complexity to your retirement planning. It’s important to understand these nuances so you can navigate your savings strategy with confidence.
As you consider your retirement savings, remember that you’re not alone. We’re here for you, ready to support you in making informed decisions that align with your family’s financial goals. Together, we can navigate this journey and ensure a secure future for your loved ones.
Conclusion
Understanding the implications of over-contributing to a Roth IRA is crucial for parents who want to secure their family’s financial future. Imagine facing penalties for exceeding IRS contribution limits – like a 6% tax on the excess amount each year it stays in the account. By being aware of these consequences, you can take steps to manage your contributions effectively and avoid unnecessary financial burdens.
This article highlights several key strategies to help you prevent over-contribution:
- Keeping detailed records of your contributions
- Utilizing tax planning software
- Making smaller contributions throughout the year
By implementing these practices, you can maintain control over your IRA contributions and ensure you stay within the designated limits. Plus, understanding the differences between Roth and traditional IRAs can provide valuable insights into long-term tax planning and withdrawal strategies.
Ultimately, the importance of being informed about Roth IRA contribution limits cannot be overstated. Taking the time to understand the rules and consequences allows you to navigate your retirement savings with confidence. This knowledge not only protects you against costly penalties but also empowers your family to make informed decisions that align with your financial goals. Together, we can embrace these strategies and pave the way for a secure and prosperous future for your loved ones.
Frequently Asked Questions
What is an over-contribution to a Roth IRA?
An over-contribution to a Roth IRA occurs when an individual contributes more than the IRS-set limits for that tax year. For 2026, the limits are $7,500 for individuals under 50 and $8,600 for those aged 50 and older.
What are the consequences of over-contributing to a Roth IRA?
If you over-contribute to a Roth IRA, the excess amount is classified as an overage, which could result in a 6% tax penalty on that surplus for every year it remains in your account.
How can I avoid penalties for over-contributing to a Roth IRA?
To avoid penalties, you can either withdraw any surplus contributions and their earnings before filing your tax return or apply the excess toward the following year’s contribution limit.
Why is it important to understand Roth IRA contribution limits?
Understanding Roth IRA contribution limits is vital for optimizing retirement savings and avoiding unnecessary penalties, especially for parents trying to secure their family’s financial future.
List of Sources
- Define Over-Contribution to Roth IRAs
- Roth IRA income and contribution limits for 2026 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)
- Understanding the 2026 Roth and TSP changes: What federal employees need to know now (https://federalnewsnetwork.com/federal-insights/2025/12/understanding-the-2026-roth-and-tsp-changes-what-federal-employees-need-to-know-now)
- 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500)
- IRS reveals updated retirement contribution limits for 2026 (https://foxbusiness.com/economy/irs-reveals-updated-retirement-contribution-limits-2026)
- Explore Consequences of Over-Contribution
- IRA Excess Contribution Case Involves Battle Over Taxes. (https://calt.iastate.edu/annotation/ira-excess-contribution-case-involves-battle-over-taxes)
- What to Do About Excess Contributions to a Roth IRA | SoFi (https://sofi.com/learn/content/excess-roth-ira-contribution)
- Tax Court Affirms Excise Tax On Family’s Roth IRA Payments – Law360 (https://law360.com/articles/1018700/tax-court-affirms-excise-tax-on-family-s-roth-ira-payments)
- Identify Strategies to Prevent Over-Contribution
- IRS Issues Roth Catch-Up Contribution Rules for Highly Paid Participants (https://ogletree.com/insights-resources/blog-posts/irs-issues-roth-catch-up-contribution-rules-for-highly-paid-participants)
- Roth Conversions in Retirement (A Case Study) — Oakleigh Wealth Services (https://oakleighwealth.com/articles/roth-conversions-case)
- Compare Over-Contribution Effects on Roth vs. Traditional IRAs
- Excess Roth IRA Contributions – Are They Worth the Risk? – IRA Financial (https://irafinancial.com/blog/excess-roth-ira-contributions)
- Roth IRA vs. Traditional IRA: Rules & Tax Benefits | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira)
- Roth Conversions in Retirement (A Case Study) — Oakleigh Wealth Services (https://oakleighwealth.com/articles/roth-conversions-case)
- The Key Differences Between Traditional and Roth IRAs You Need to Know – Abeles and Hoffman, St. Louis CPAs & Business Advisors AHCPA (https://ahcpa.com/the-key-differences-between-traditional-and-roth-iras-you-need-to-know)
- Roth IRA vs. Traditional IRA: Key Differences, Benefits & When To Choose Each (https://merceradvisors.com/insights/retirement/roth-ira-vs-traditional-ira-key-differences-benefits-when-to-choose-each)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading