

Key Highlights
- Vested shares are stock options that employees own after meeting specific conditions, such as tenure at the company.
- Employees typically lose unvested shares if they leave before fully vesting, which can lead to significant financial losses.
- Understanding the vesting schedule is crucial; for example, a four-year schedule may allow 25% of shares to vest each year.
- Upon resignation, vested shares remain with the employee, but they must exercise options within a specified post-termination exercise period (PTEP), usually 90 days.
- In Q4 2023, only 23% of startup employees exercised their stock options before expiration, indicating a risk of losing benefits.
- Financial planning is essential, as nearly 50,000 workers forfeited over $1.8 billion in stock incentives in 2022 due to lack of awareness.
- Tax implications vary by state; for instance, California has a capital gains tax rate of up to 13.3%, while Texas has no state income tax.
- Timing the sale of vested shares can affect tax liabilities, with long-term holdings potentially qualifying for lower capital gains tax rates.
- Families should consider strategies like tax-loss harvesting and diversifying investments to manage their vested shares effectively.
Introduction
Imagine facing a career change and wondering what will happen to your hard-earned vested shares – it’s a concern many professionals share. Vested shares are an important part of your compensation, but the rules can feel complicated and confusing. As you think about your family’s financial future, it’s important to consider what happens to these valuable assets when you decide to move on. In this article, we’ll explore the ins and outs of vested shares, helping you understand what to do with your hard-earned equity when you leave a job.
Define Vested Shares: Understanding Their Role in Employment
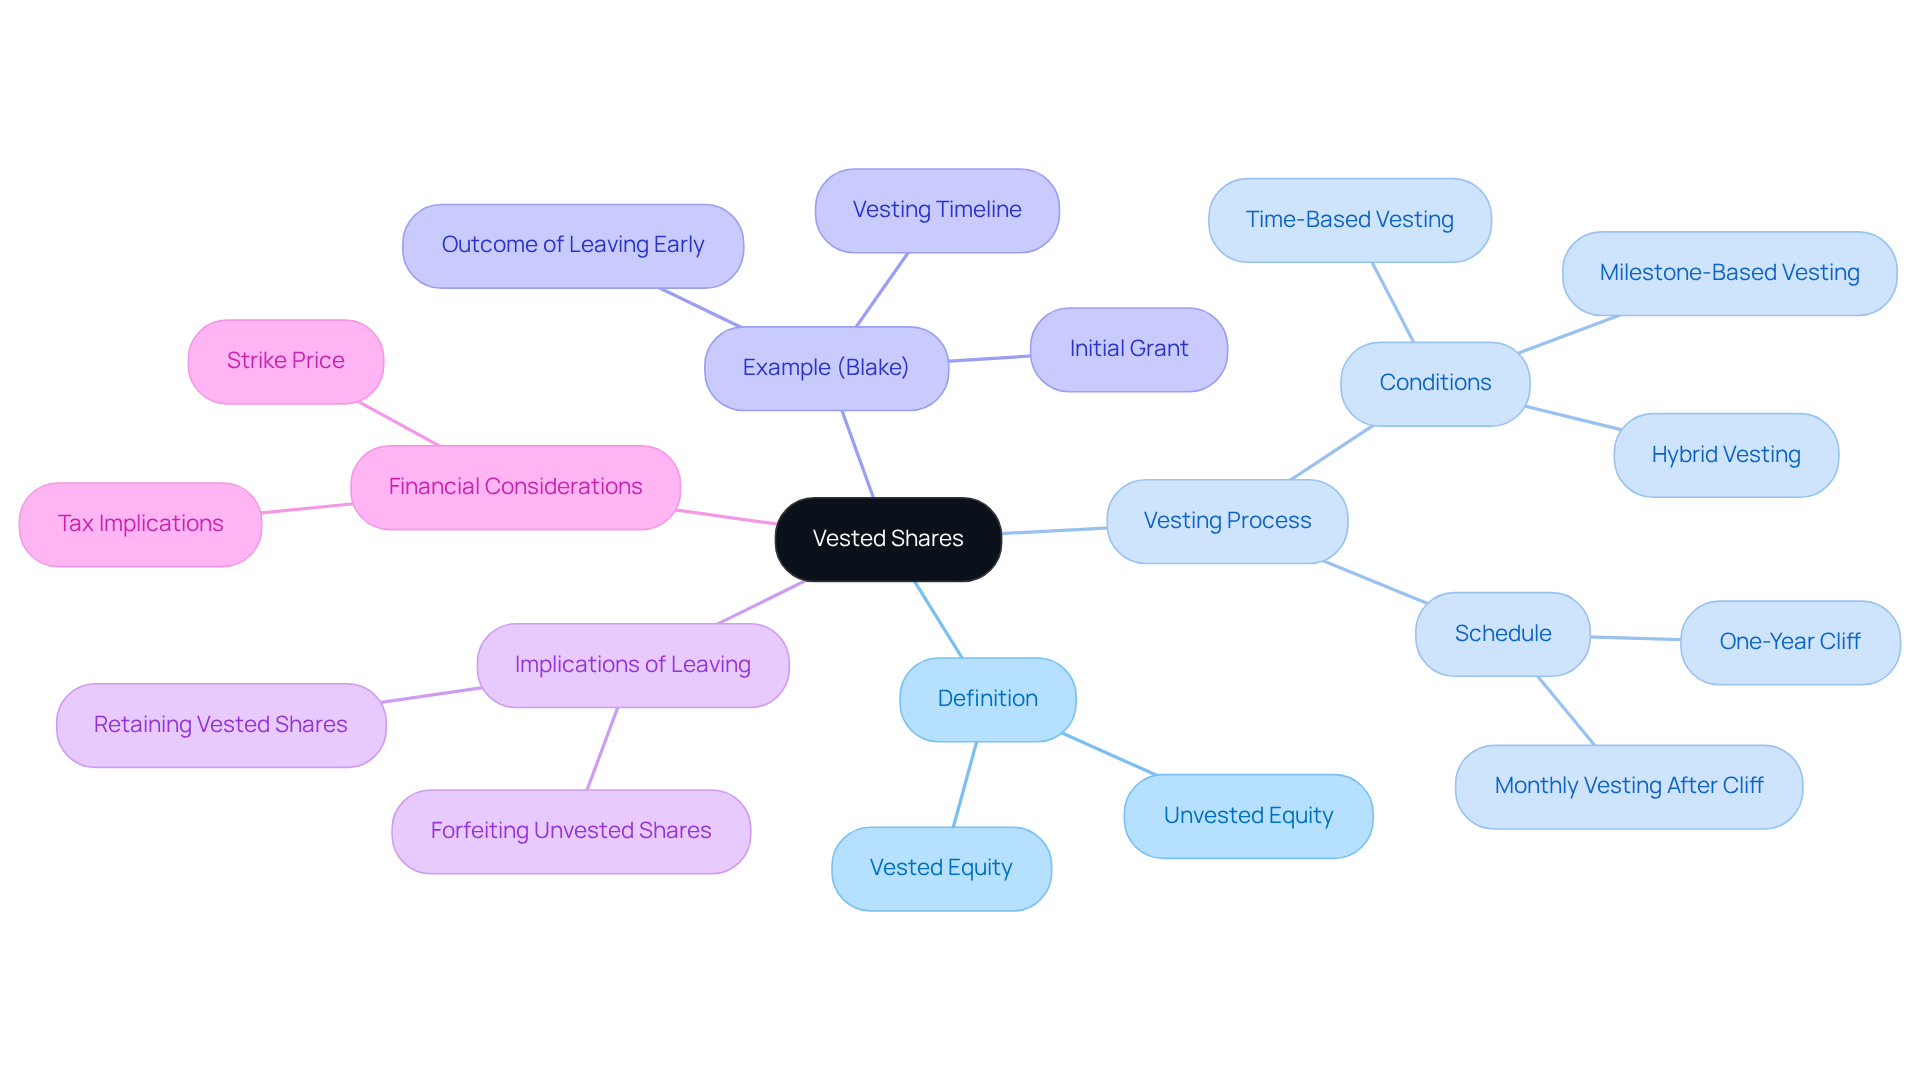
Have you ever wondered what happens to your stock options if you decide to leave your job? Vested equity is the part of your stock options that you actually own after meeting certain conditions, like how long you’ve worked at your job. Once these assets vest, they become yours to sell or transfer. This process is designed to encourage you to stay with the company for a while, often laid out in a legally binding vesting schedule. For instance, you might receive stock grants that become available over four years, with 25% of the units accessible each year.
Imagine the uncertainty of leaving a job without fully understanding what happens to vested shares when you quit. Let’s say you’re like Blake, who is granted 192 units with a four-year vesting schedule and a one-year cliff. She won’t own any equity until she completes one year of service. After that, she’ll get 48 units (1/4 of her total) and continue to receive the rest monthly until she’s fully vested. If Blake leaves before she’s fully vested, she’ll lose all unvested equity, which leads to the question of what happens to vested shares when you quit, as those shares go back to the company for future employees. This setup helps you feel more connected to your company’s journey, making your hard work feel even more rewarding. Plus, the strike price for stocks is based on the fair market value at the time of the grant, which is crucial for understanding the financial implications of exercising stock options.
In conclusion, understanding your equity can empower you to make informed career decisions that align with your family’s financial goals. By grasping the nuances of allocated equity, you can make choices that not only benefit your career but also support your family’s future.
Explore Outcomes for Vested Shares Upon Quitting
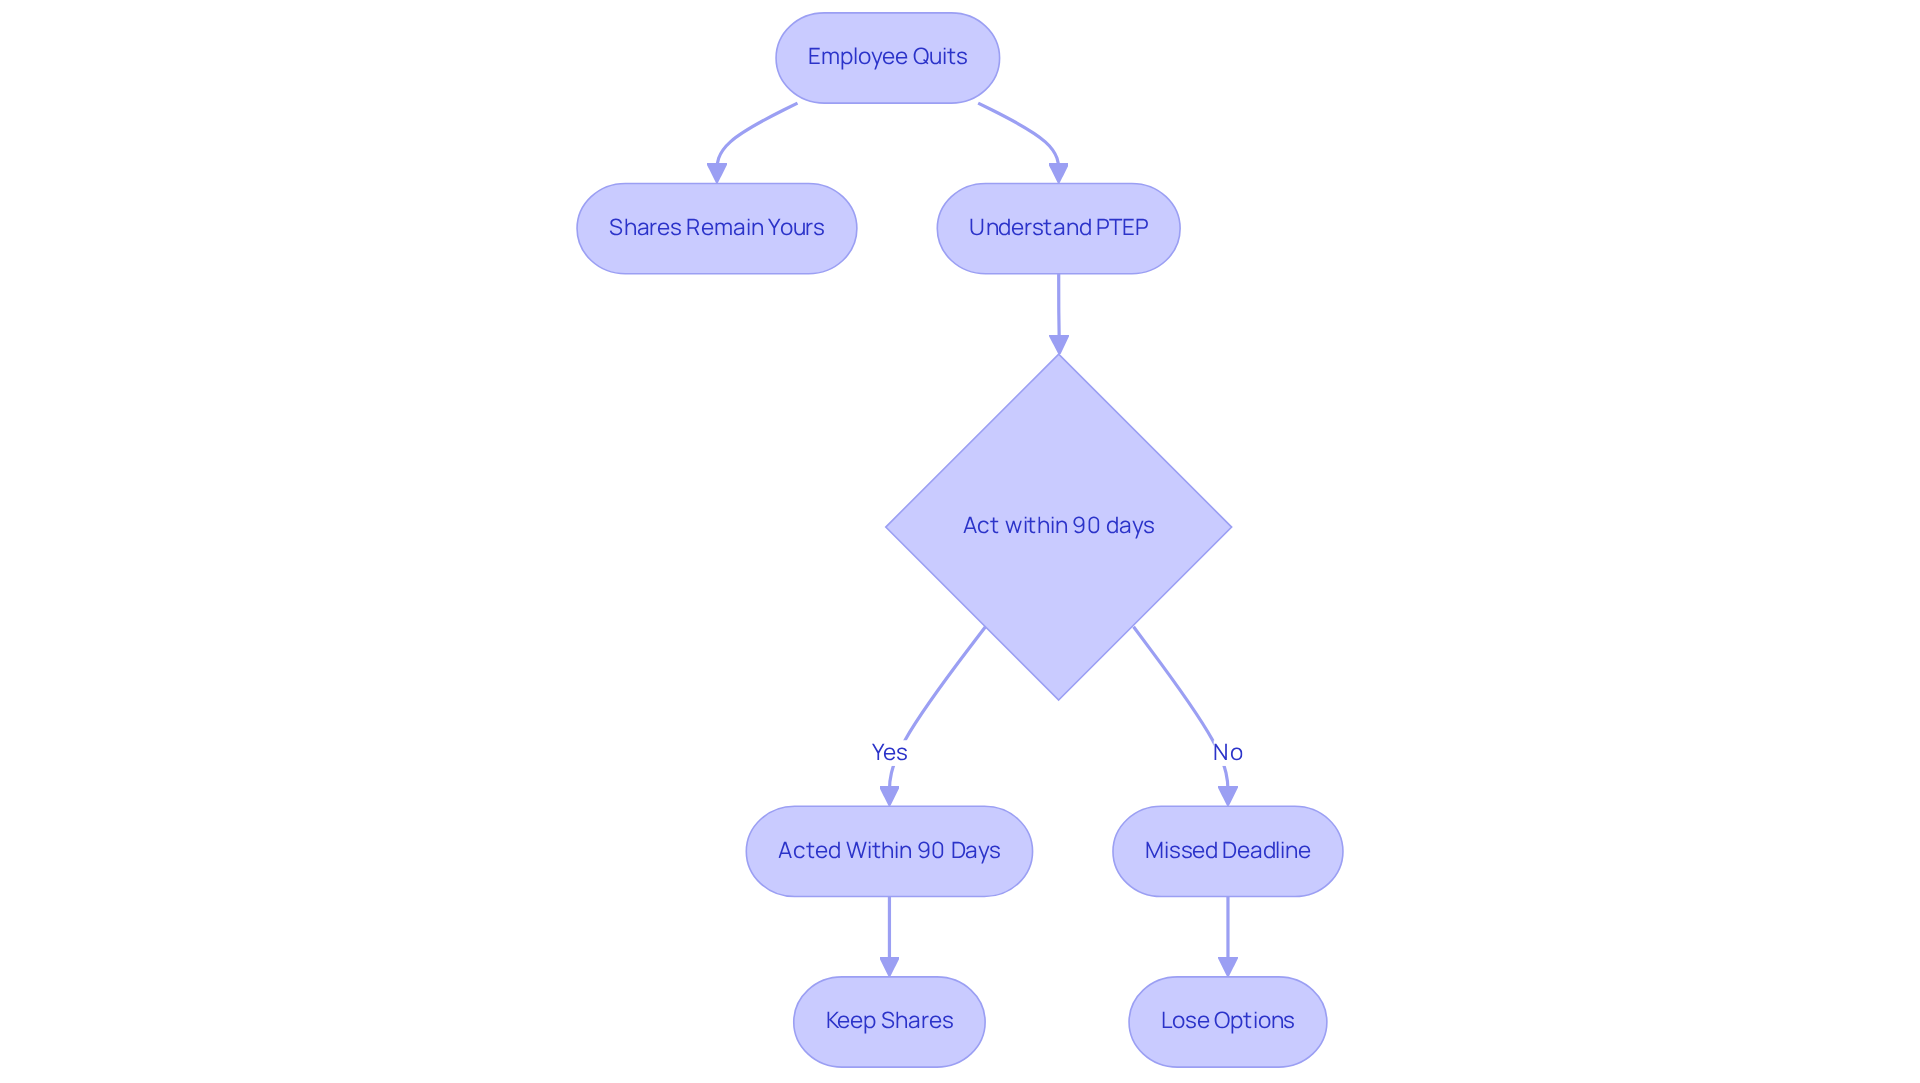
Imagine facing a job change and wondering what will happen to your hard-earned equity – it’s a common concern for many families today. When a worker resigns, it is important to understand what happens to vested shares when you quit, as the outcome often hinges on the company’s rules and the type of compensation involved. Generally, when considering what happens to vested shares when you quit, they remain yours, allowing you to keep ownership. But it’s important for families to know about specific conditions, like the post-termination exercise period (PTEP) for stock grants, which usually means they need to act within 90 days after leaving their job. If they miss this window, they risk losing those valuable options. In fact, in Q4 2023, only 23% of startup employees utilized their acquired rights before expiration, highlighting the potential loss of benefits. Understanding what happens to vested shares when you quit can ease worries and help families plan better during job changes.
Case studies show just how crucial it is to be aware of vesting schedules and what happens to vested shares when you quit. Many employees struggle to use their granted rights due to financial constraints. Options like negotiating a sign-on bonus or asking for an extension of the PTEP can make a difference during separation. In 2022, nearly 50,000 workers gave up fully acquired stock incentives, resulting in a staggering loss of over $1.8 billion in potential value. This underscores the importance of thoroughly reviewing equity documents and seeking guidance from financial experts to navigate these options effectively.
By understanding the ins and outs of vested equity, families can feel more secure in their financial future, especially when navigating job changes.
Differentiate Between Vested and Unvested Shares
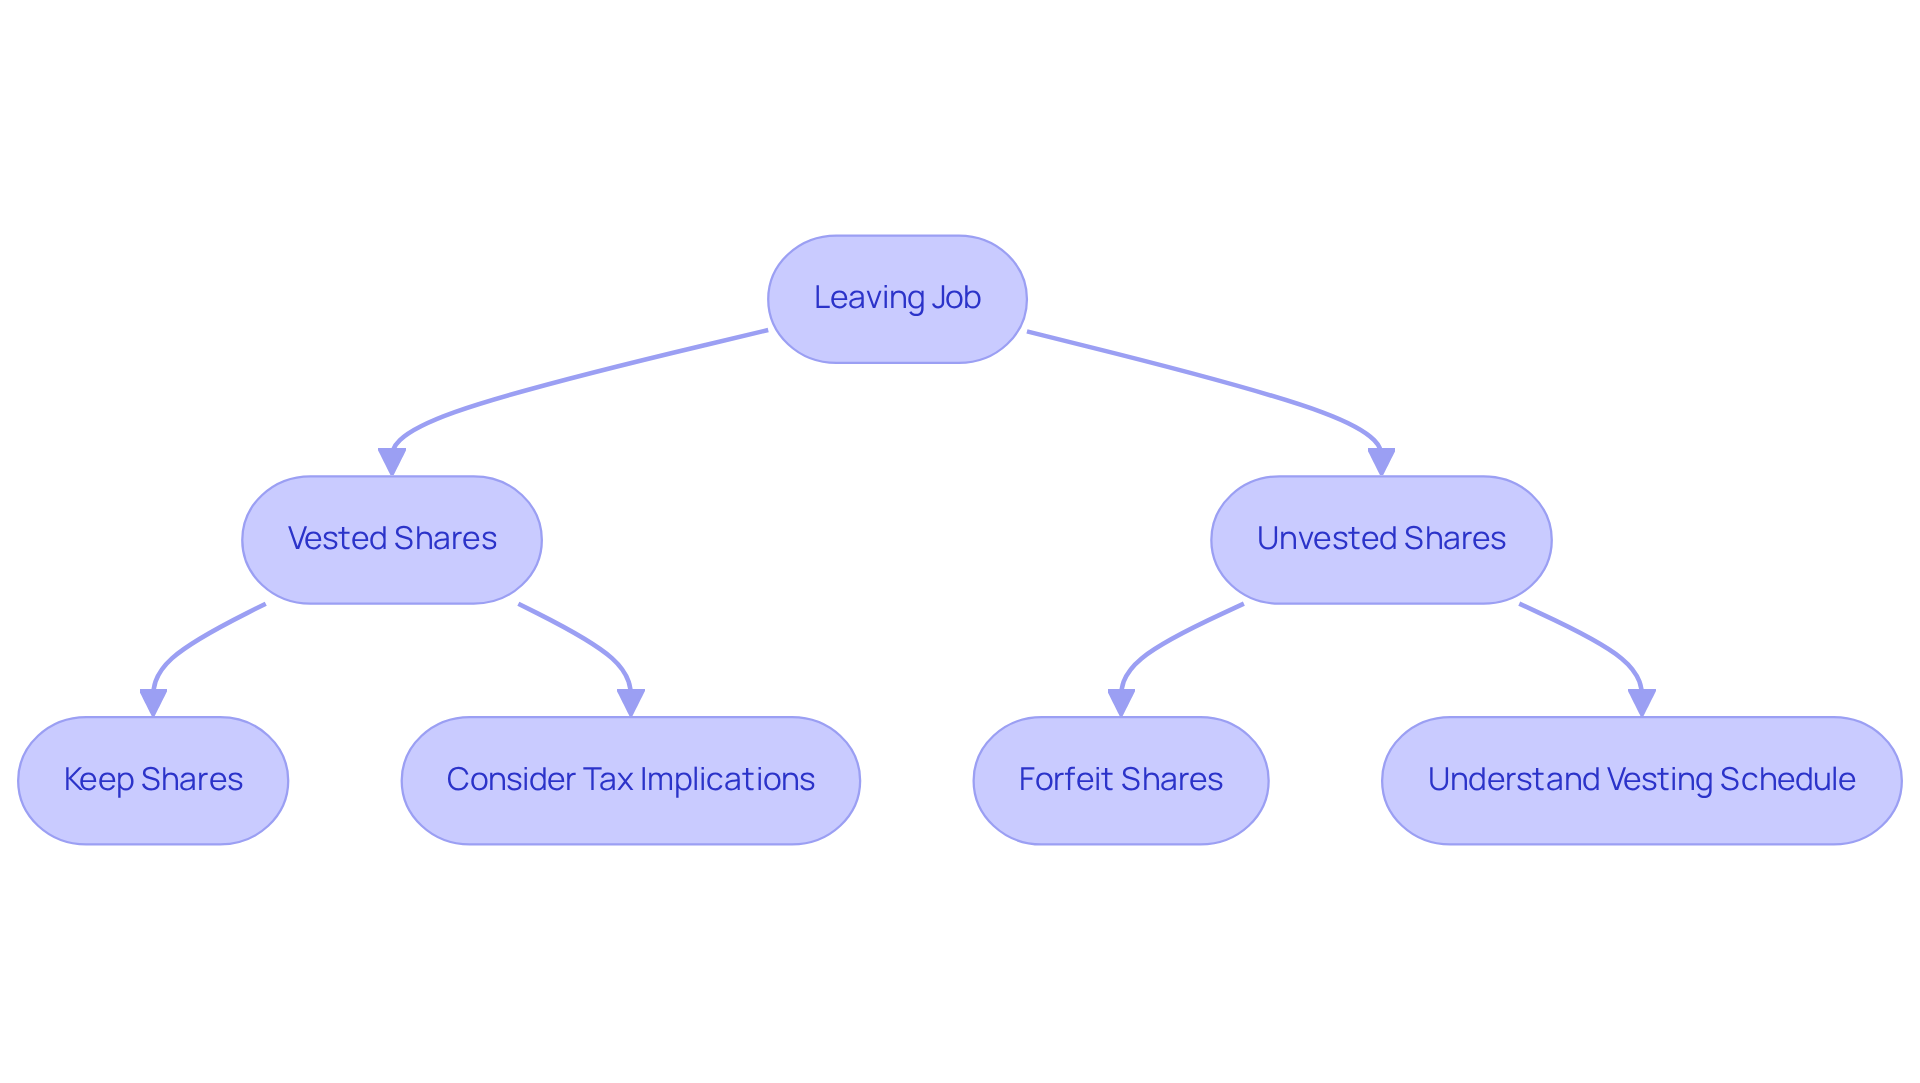
Imagine working hard for years, only to discover what happens to vested shares when you quit your job, which could mean losing valuable equity. Vested units are the ones you’ve earned, while unvested units depend on how long you’ve worked or your performance. If you leave before your equity vests, you might be concerned about what happens to vested shares when you quit, as you could lose those unvested equities. For instance, if you’re awarded 1,000 units with a four-year acquisition timeline and leave after two years, you may keep only the 500 units that have vested, leading to the question of what happens to vested shares when you quit regarding the remaining 500. It’s important to remember what happens to vested shares when you quit, as leaving before your assets are allocated could mean losing those equities, which can be a tough pill to swallow.
Financial specialists emphasize that understanding the difference between allocated and unallocated equities is crucial for effective financial planning. If you possess 1,000 Restricted Stock Units (RSUs) that convert into actual assets upon vesting, it is important to know what happens to vested shares when you quit, as you will lose any unvested RSUs if you leave the organization prematurely. Data shows that workers generally forfeit unearned stocks upon termination, which leads to the question of what happens to vested shares when you quit, as many firms allow only a 90-day period to exercise acquired rights after departure. Understanding what happens to vested shares when you quit can help you avoid unexpected losses that could impact your family’s future.
Consider the implications of these distinctions. One employee exercised their acquired stock options before leaving the company to maintain favorable tax treatment, while another faced significant tax liabilities due to unexercised options that expired after their departure. These examples highlight the necessity of understanding equity compensation and what happens to vested shares when you quit, especially regarding its impact on financial outcomes during employment transitions. Understanding these nuances can empower you to make informed decisions that protect your family’s financial future.
Assess Financial Implications and Options for Vested Shares
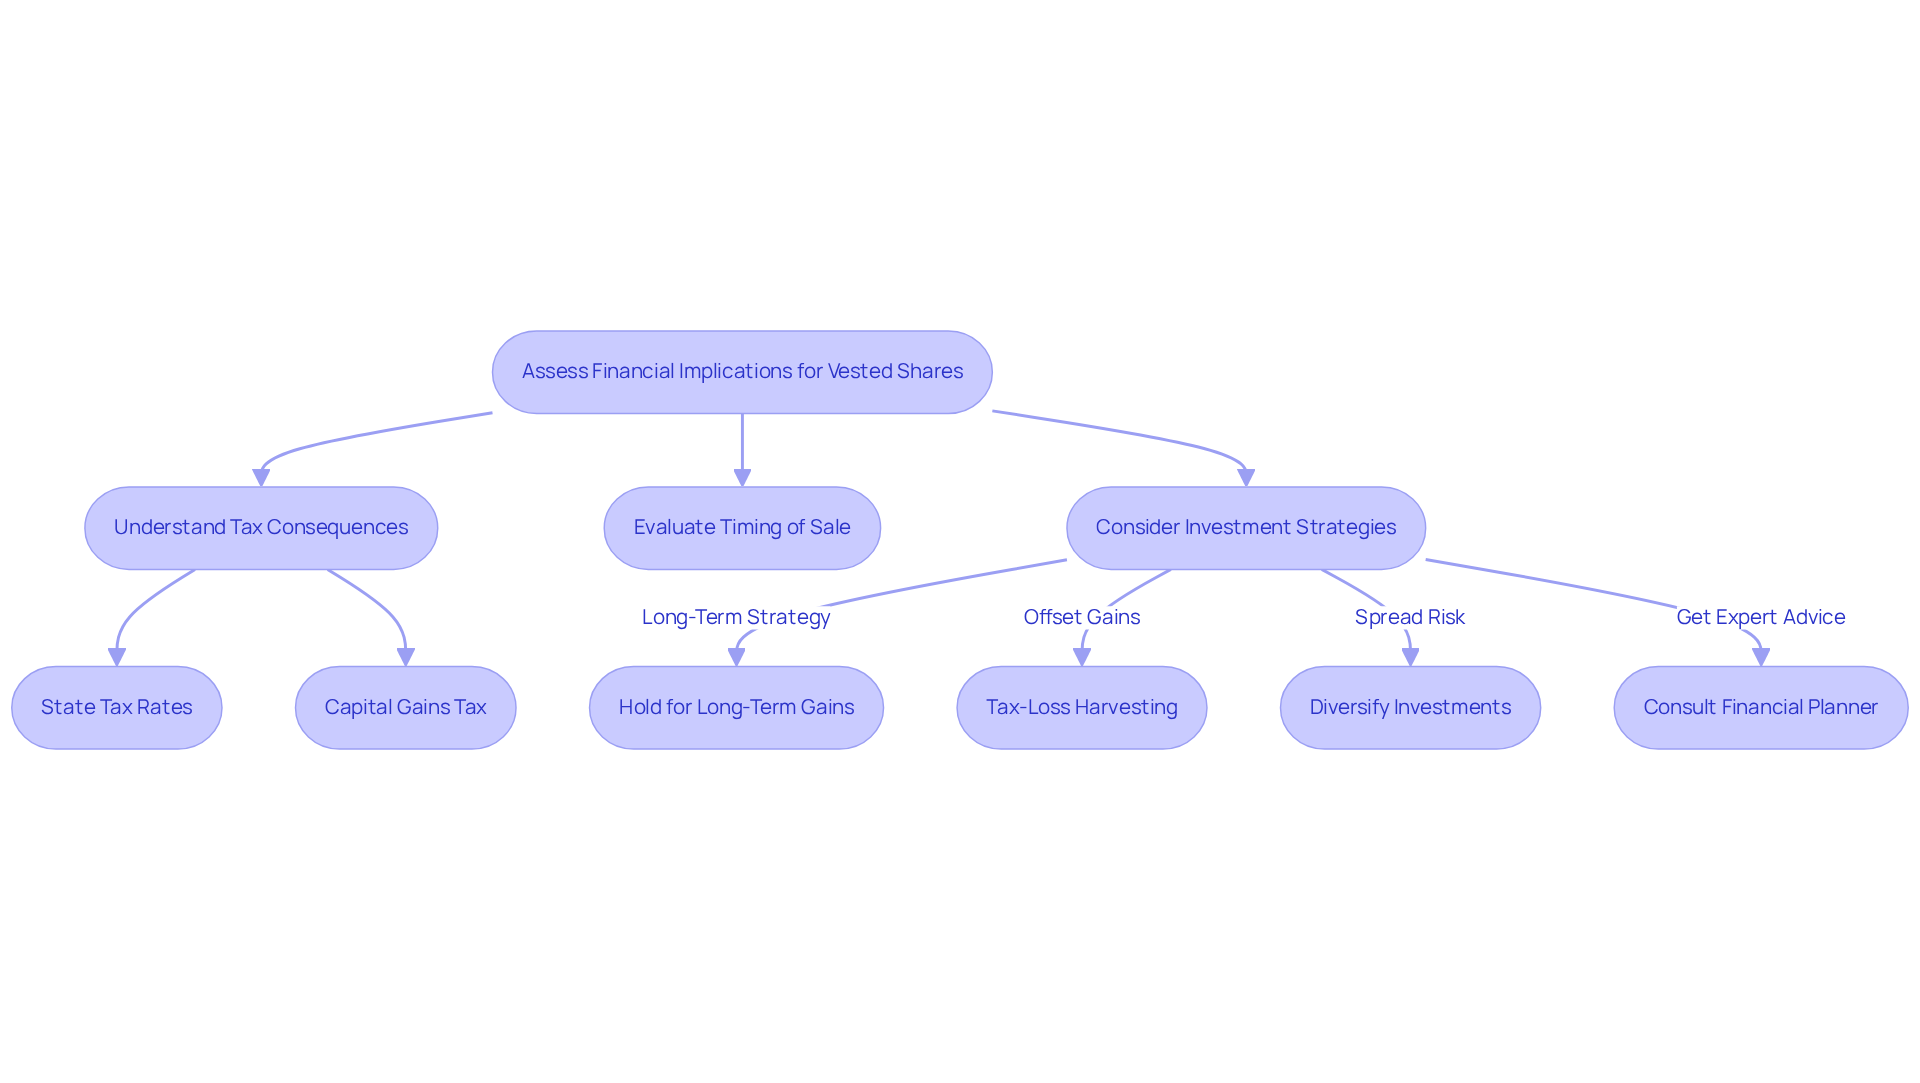
Imagine feeling overwhelmed by the complexities of selling your stocks and the potential tax consequences that come with it. The financial consequences of selling your stocks can be daunting, especially when it comes to taxes and how it fits into your family’s investment strategy. When you sell your vested stocks, it’s important to know that any profits could be taxed differently depending on where you live. For example, in California, you might face a capital gains tax rate as high as 13.3%, while in Texas, there’s no state income tax at all. This makes it essential to think about how your state’s tax laws affect your decision to sell your stocks.
It’s also important to consider when you sell, as the timing can impact how much tax you’ll owe. For instance, if you hold onto your investments for more than a year, you could qualify for lower long-term capital gains tax rates, which can be anywhere from 0% to 20% based on your income. This approach can really help lower the taxes you owe when you sell, as many investors have found that holding their assets longer leads to better tax rates.
Families like yours should think about how to manage these assets effectively. You might decide to hold onto them for future growth or consider diversifying your investments to spread out the risk. Working with a financial planner can give you helpful insights into these choices, making sure they fit with your family’s long-term financial goals. For instance, tax-loss harvesting – selling investments that aren’t performing well to offset gains – can be a smart way to lower your taxable income and capital gains tax bill.
Ultimately, grasping the tax implications and financial strategies tied to your vested shares is vital for families like yours, especially as you look to secure a bright future for your children.
Conclusion
Imagine the uncertainty of leaving a job and wondering what happens to your hard-earned shares. Vested shares are an important part of your compensation. Understanding how to manage them can truly impact your family’s financial future. When you leave a job, your vested shares usually stay with you. However, there are important conditions to meet, like the post-termination exercise period, to keep these valuable assets.
Throughout this article, we’ve explored the differences between vested and unvested shares, the significance of understanding vesting schedules, and the financial implications of selling vested shares. We’ve shared stories of individuals who faced losses because they didn’t act within the right timeframes, highlighting the importance of careful planning and seeking advice from financial experts. Additionally, we discussed how state tax laws can influence the sale of vested shares, showing how geographical differences can affect your financial outcomes.
When you know what happens to your vested shares after leaving a job, it helps you and your family make smart choices for your financial future. By understanding the nuances of equity compensation and the related tax implications, you can navigate job changes with confidence. Taking proactive steps, like consulting with a fiduciary advisor such as Bright Advisers, ensures that you make wise wealth decisions that protect your family’s assets for generations to come. By taking these steps, you can ensure your family’s financial future remains bright and secure, no matter where life takes you.
Frequently Asked Questions
What are vested shares?
Vested shares are the portion of stock options that you own after meeting specific conditions, such as the duration of your employment. Once these shares vest, they become yours to sell or transfer.
How does the vesting process work?
The vesting process is typically outlined in a legally binding vesting schedule. For example, you might receive stock grants that become available over a period of four years, with a certain percentage, like 25%, becoming accessible each year.
What happens to vested shares if I leave my job?
If you leave your job, you retain ownership of your vested shares, but you will lose any unvested equity, which will revert back to the company for future employees.
Can you provide an example of a vesting schedule?
Yes, for instance, if an employee named Blake is granted 192 units with a four-year vesting schedule and a one-year cliff, she will not own any equity until she completes one year of service. After that, she will receive 48 units (1/4 of her total) and continue to receive the remaining units monthly until fully vested.
What is the significance of the strike price for stock options?
The strike price for stocks is based on the fair market value at the time of the grant. Understanding this price is crucial for evaluating the financial implications of exercising stock options.
How can understanding vested shares impact my career decisions?
By understanding your equity and the vesting process, you can make informed career decisions that align with your family’s financial goals, ensuring that your choices benefit both your career and your family’s future.
List of Sources
- Define Vested Shares: Understanding Their Role in Employment
- What Are Vested Shares and How Do They Benefit Employees? | LegalVision UK (https://legalvision.co.uk/startups/vested-shares-explained)
- Stock Vesting Explained (https://jpmorganworkplacesolutions.com/insights/what-does-vesting-shares-mean)
- Vesting Explained: Schedules, Cliffs, Acceleration, and Types (https://carta.com/learn/equity/stock-options/vesting)
- Explore Outcomes for Vested Shares Upon Quitting
- What Happens to Stock Options if You Quit? | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/what-happens-to-stock-options-if-i-leave-the-company)
- The Post-Termination Exercise Period (PTEP) for Options Explained (https://carta.com/learn/equity/leaving-company/post-termination-exercise-period)
- What Happens to Vested Stock & Equity When You Leave (https://carta.com/learn/equity/leaving-company)
- What happens to my equity when I leave a company? (https://qapita.com/blog/equity-compensation-when-you-leave-a-company)
- Should you exercise your vested stock options after leaving your company? — Secfi (https://secfi.com/learn/what-to-do-with-stock-options-when-leaving)
- Differentiate Between Vested and Unvested Shares
- Unvested Stock Explained: Understanding Vested and Unvested Shares (https://summitry.com/blog/unvested-stock-explained)
- What Happens to My Equity Compensation If I Leave the Company? (https://schwab.com/learn/story/what-happens-to-equity-compensation-if-i-leave)
- What happens to my equity when I leave a company? (https://qapita.com/blog/equity-compensation-when-you-leave-a-company)
- What Happens to Stock Options and RSUs When You Leave a Company? (https://navalign.com/stock-options-rsus-leaving-company)
- Assess Financial Implications and Options for Vested Shares
- 2026 Capital Gains Tax Rates by State (https://nasinvestmentsolutions.com/1031-exchange-information/tax-rates-by-state)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- State Capital Gains Tax Rates for 2026: How Much Investors Pay This Year (https://kiplinger.com/taxes/state-capital-gains-tax-rates)
- State-by-State Capital Gains Tax Rates for 2026 (https://theentrustgroup.com/blog/state-capital-gains-tax)
- How High are Capital Gains Tax Rates in Your State? (https://taxfoundation.org/data/all/state/how-high-are-capital-gains-tax-rates-your-state)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading