

Key Highlights
- High-income families face complex tax obligations that can be managed with effective tax strategies.
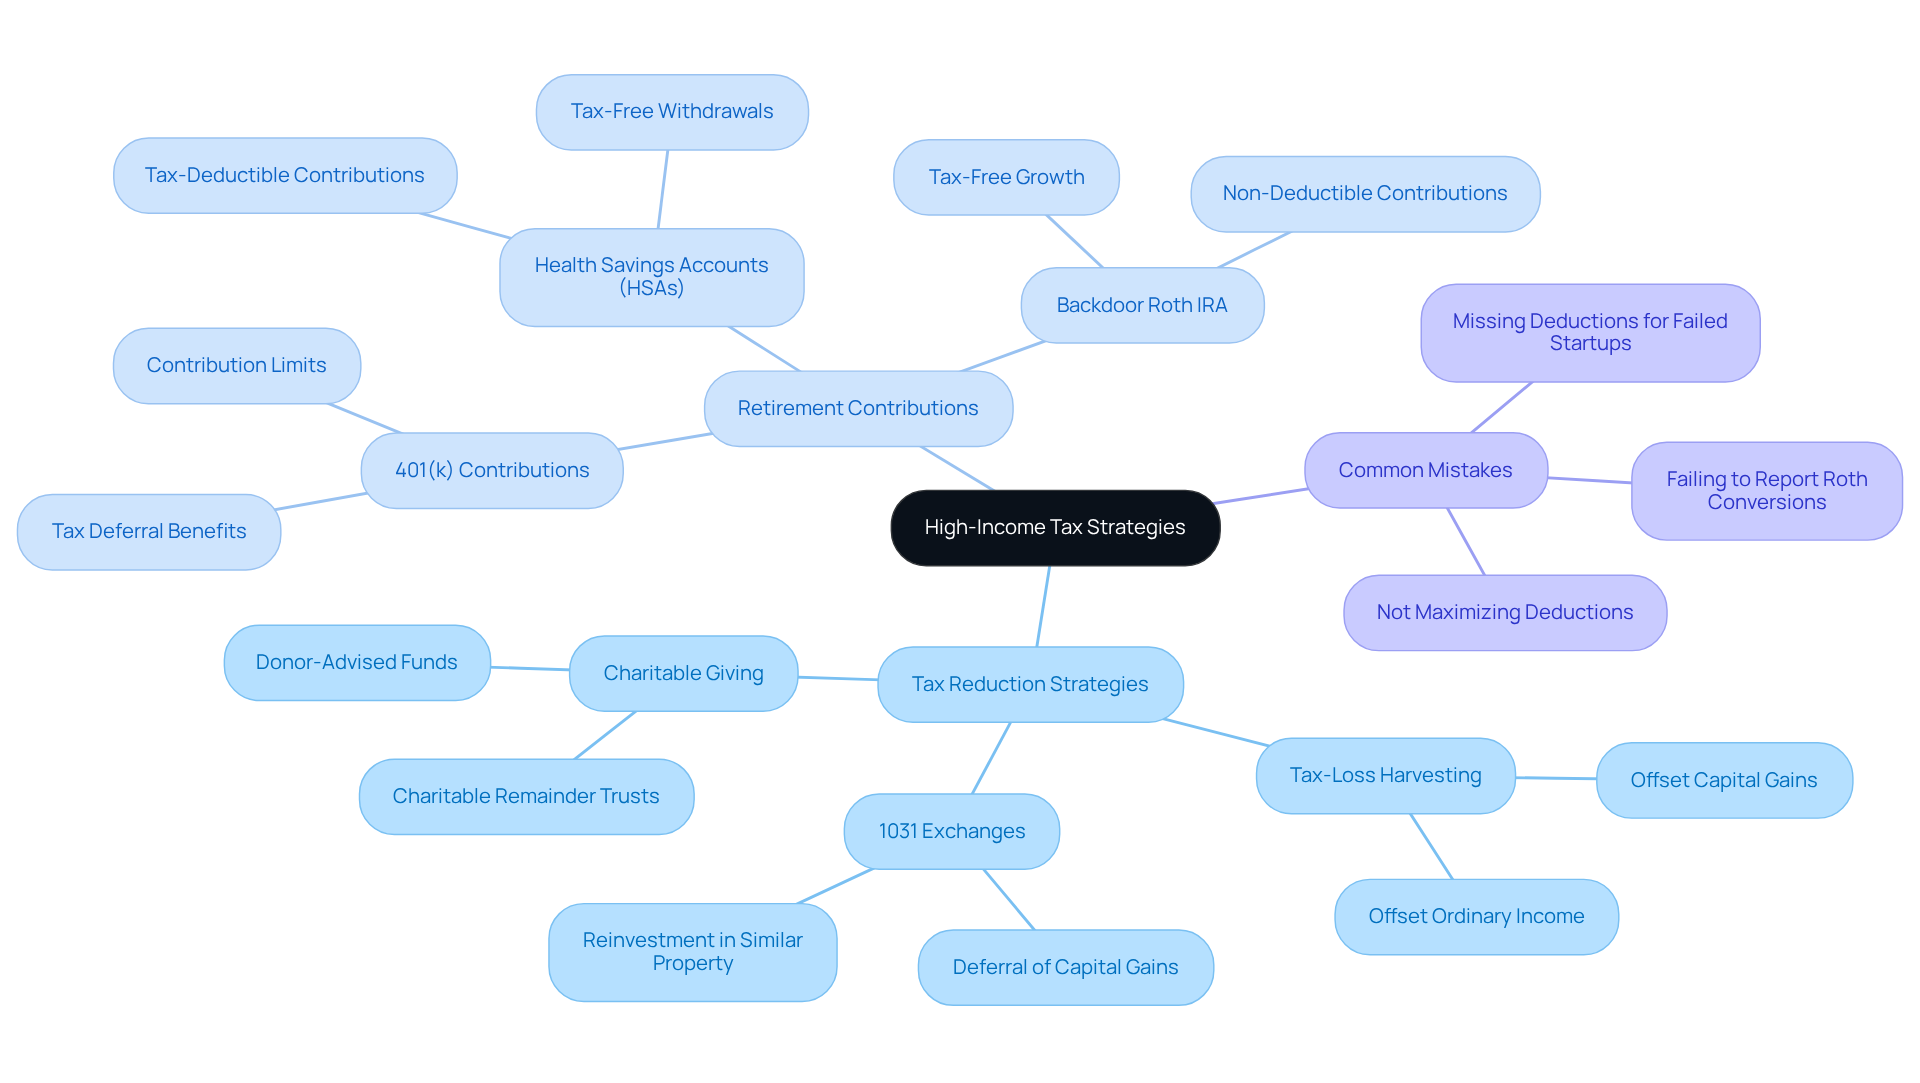
- Contributing up to $24,500 pre-tax to retirement accounts like 401(k)s can significantly reduce taxable earnings.
- Tax-loss harvesting allows families to offset capital gains by selling underperforming assets, reducing overall tax burden.
- Common tax planning mistakes include failing to report Roth conversions and missing deductions for failed startups.
- California’s tax rates require careful planning, especially with lower standard deductions for single filers in 2026.
- Historical context shows that tax rates have fluctuated significantly, impacting high-income earners’ strategies over time.
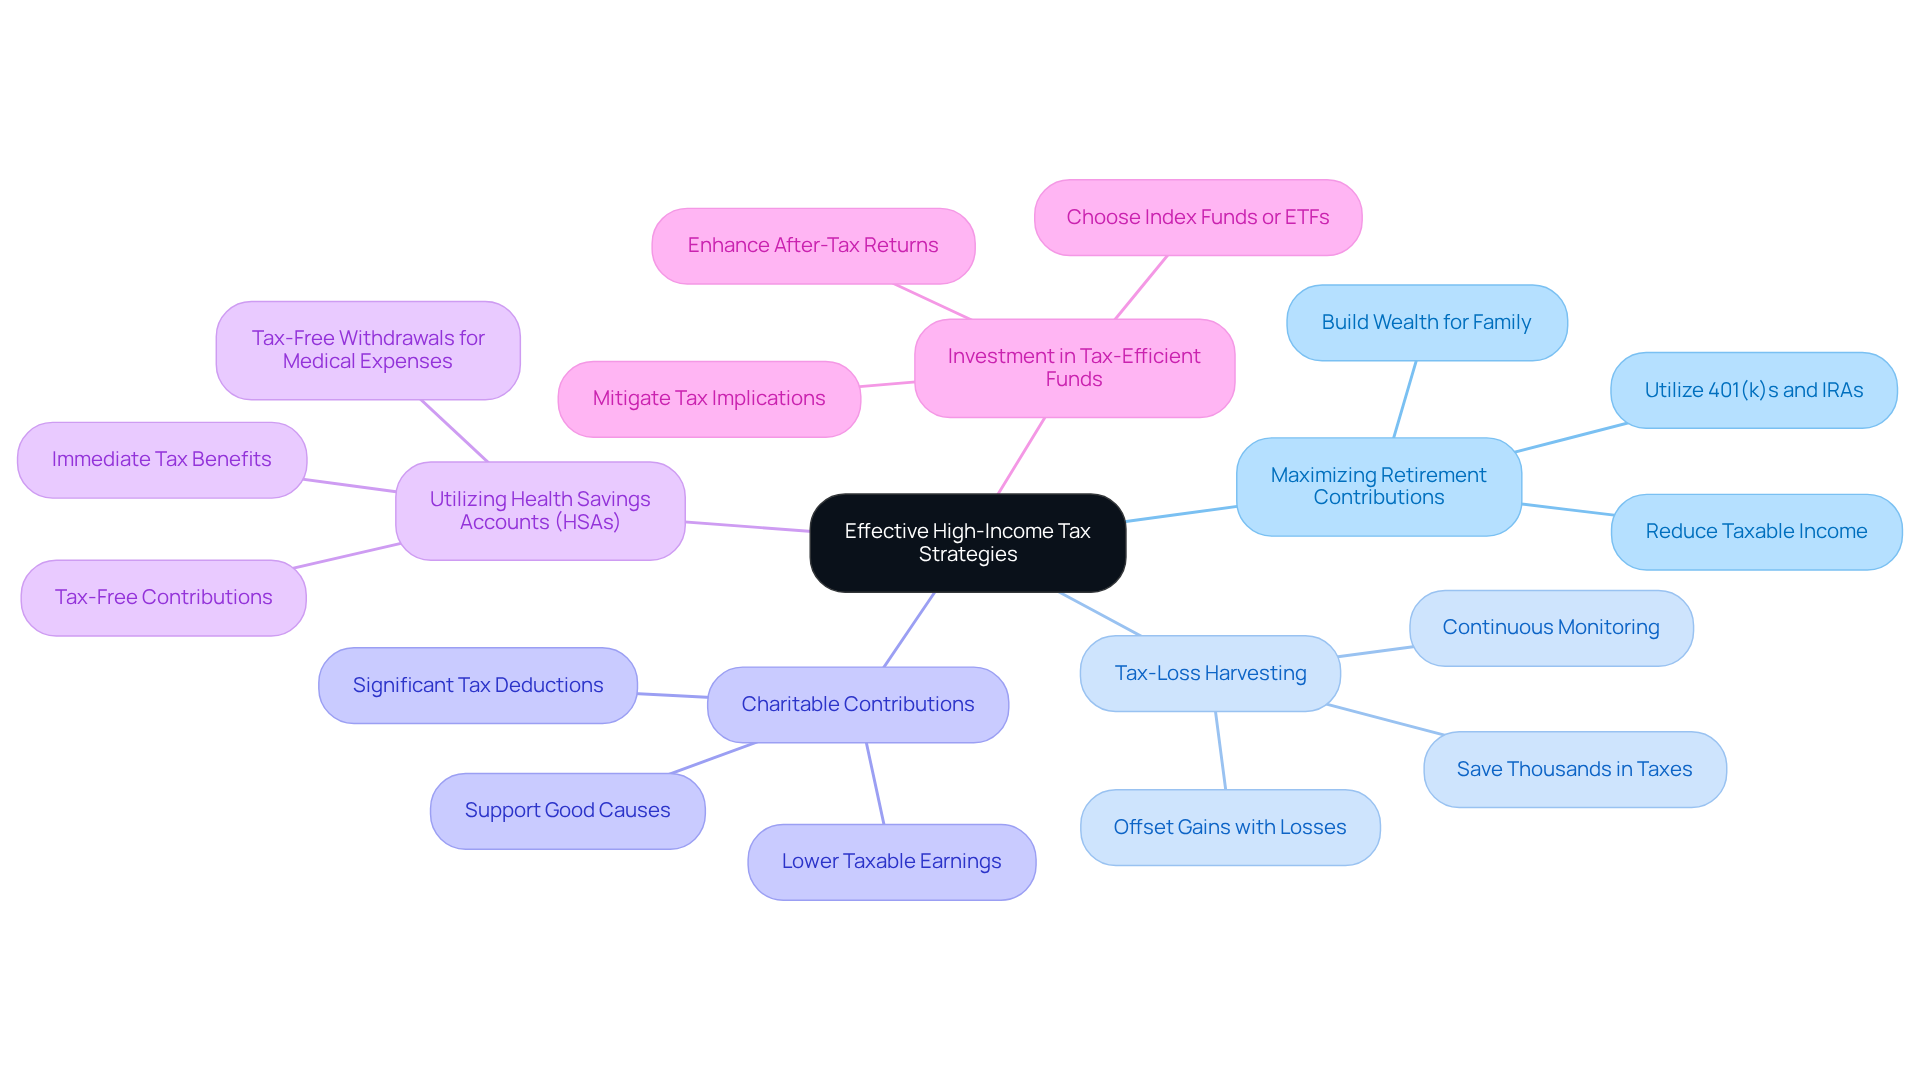
- Key components of effective tax strategies include maximising retirement contributions, tax-loss harvesting, charitable contributions, utilising Health Savings Accounts (HSAs), and investing in tax-efficient funds.
- Bright Advisers assists families in navigating tax complexities to enhance financial security and peace of mind.
Introduction
It’s easy to feel lost when it comes to taxes, especially for families with higher incomes. Knowing how to manage your taxes can make a big difference for your family’s future. As we look ahead to changes in tax laws coming in 2026, it’s important to think about how these might affect your family. So, how can your family feel secure and make the most of your finances during these changes?
Defining High-Income Tax Strategies
Imagine feeling overwhelmed by tax obligations while trying to secure your family’s future. High-earning families often face complex tax obligations that can feel daunting without a high income tax strategy for high income earners. But there are effective high income tax strategies for high income earners that can help you keep more of your hard-earned money, ensuring your family’s financial well-being.
For households with young kids, these strategies are essential. They not only lower taxable amounts but also help safeguard wealth for future generations. By applying these approaches, you can utilize a high income tax strategy for high income earners to retain a larger portion of your income, which can be reinvested or saved for important needs like education or retirement.
For example, did you know that in 2026, high-earning individuals can contribute up to $24,500 pre-tax to retirement accounts like 401(k)s? This can significantly reduce your taxable earnings. Additionally, employing a high income tax strategy for high income earners, such as tax-loss harvesting, allows families to offset capital gains by selling underperforming assets, which can greatly lessen your overall tax burden. The IRS even permits offsetting up to $3,000 in ordinary income annually through this method, making it a powerful tool for families.
Take Emily and Mark, for instance. They felt the weight of their financial responsibilities until they discovered how to maximize their deductions and save significantly. Partnering with Bright Advisers, they navigated their financial complexities and created a plan that focused on reducing debt, managing cash flow, and preparing for retirement. This not only optimized their financial well-being but also gave them the freedom to choose their career paths based on their desired work-life balance.
Awareness of common tax planning mistakes, like failing to report Roth conversions or missing deductions for failed startups, can further enhance your tax efficiency. When families take charge of their tax planning year-round, they not only simplify their financial lives but also pave the way for a secure future filled with possibilities. With potential tax reductions set to end in 2026, now is the time to act. By taking proactive steps now, you can ensure a brighter financial future for your family, filled with opportunities and peace of mind.
Context and Importance of High-Income Tax Strategies
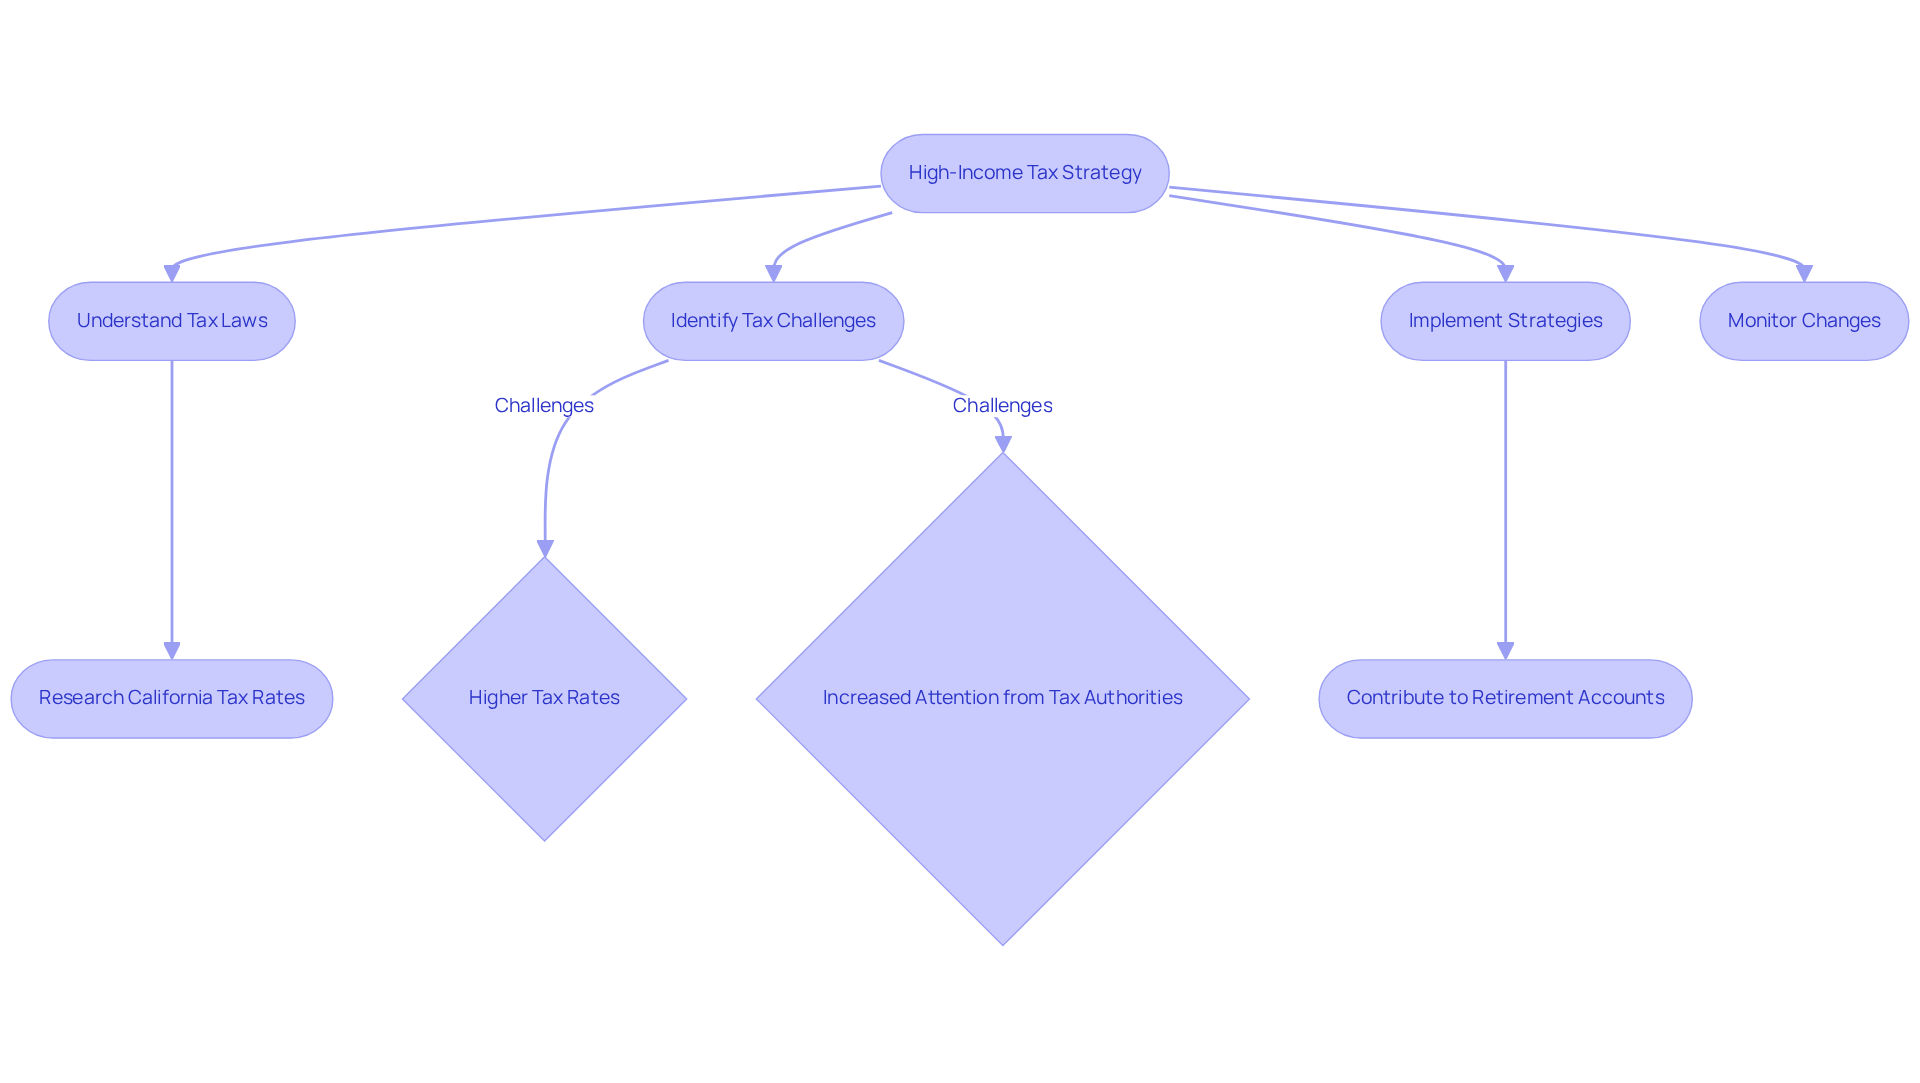
Imagine the worry of navigating complex tax laws while trying to provide for your family. It can feel overwhelming, can’t it? Many families with higher incomes face unique tax challenges, which can be mitigated by implementing a high income tax strategy for high income earners, addressing issues like higher tax rates and increased attention from tax authorities. As tax laws change, it’s important for families to find ways to manage their tax responsibilities effectively. In California, where tax rates can be quite high, families need to be especially careful with their tax planning. For 2026, California’s standard deduction for single filers is much lower than the federal one, which can affect how much tax you owe.
Finding ways to reduce your taxable income, like contributing more to retirement accounts, can really help your family financially. For instance, a family earning $80,000 in California might pay around $3,348 in taxes, which is about 4.2% of their income. By managing their investments wisely, families can save on taxes now and build wealth for the future. Taking these steps can help families feel more secure about their financial future, even with the challenges posed by a high income tax strategy for high income earners.
Allison and Brian worked with Bright Advisers to improve their tax situation, save for their kids’ education, and even plan for an earlier retirement. Their story shows how having the right support can lead to financial security and peace of mind.
Historical Development of High-Income Tax Strategies
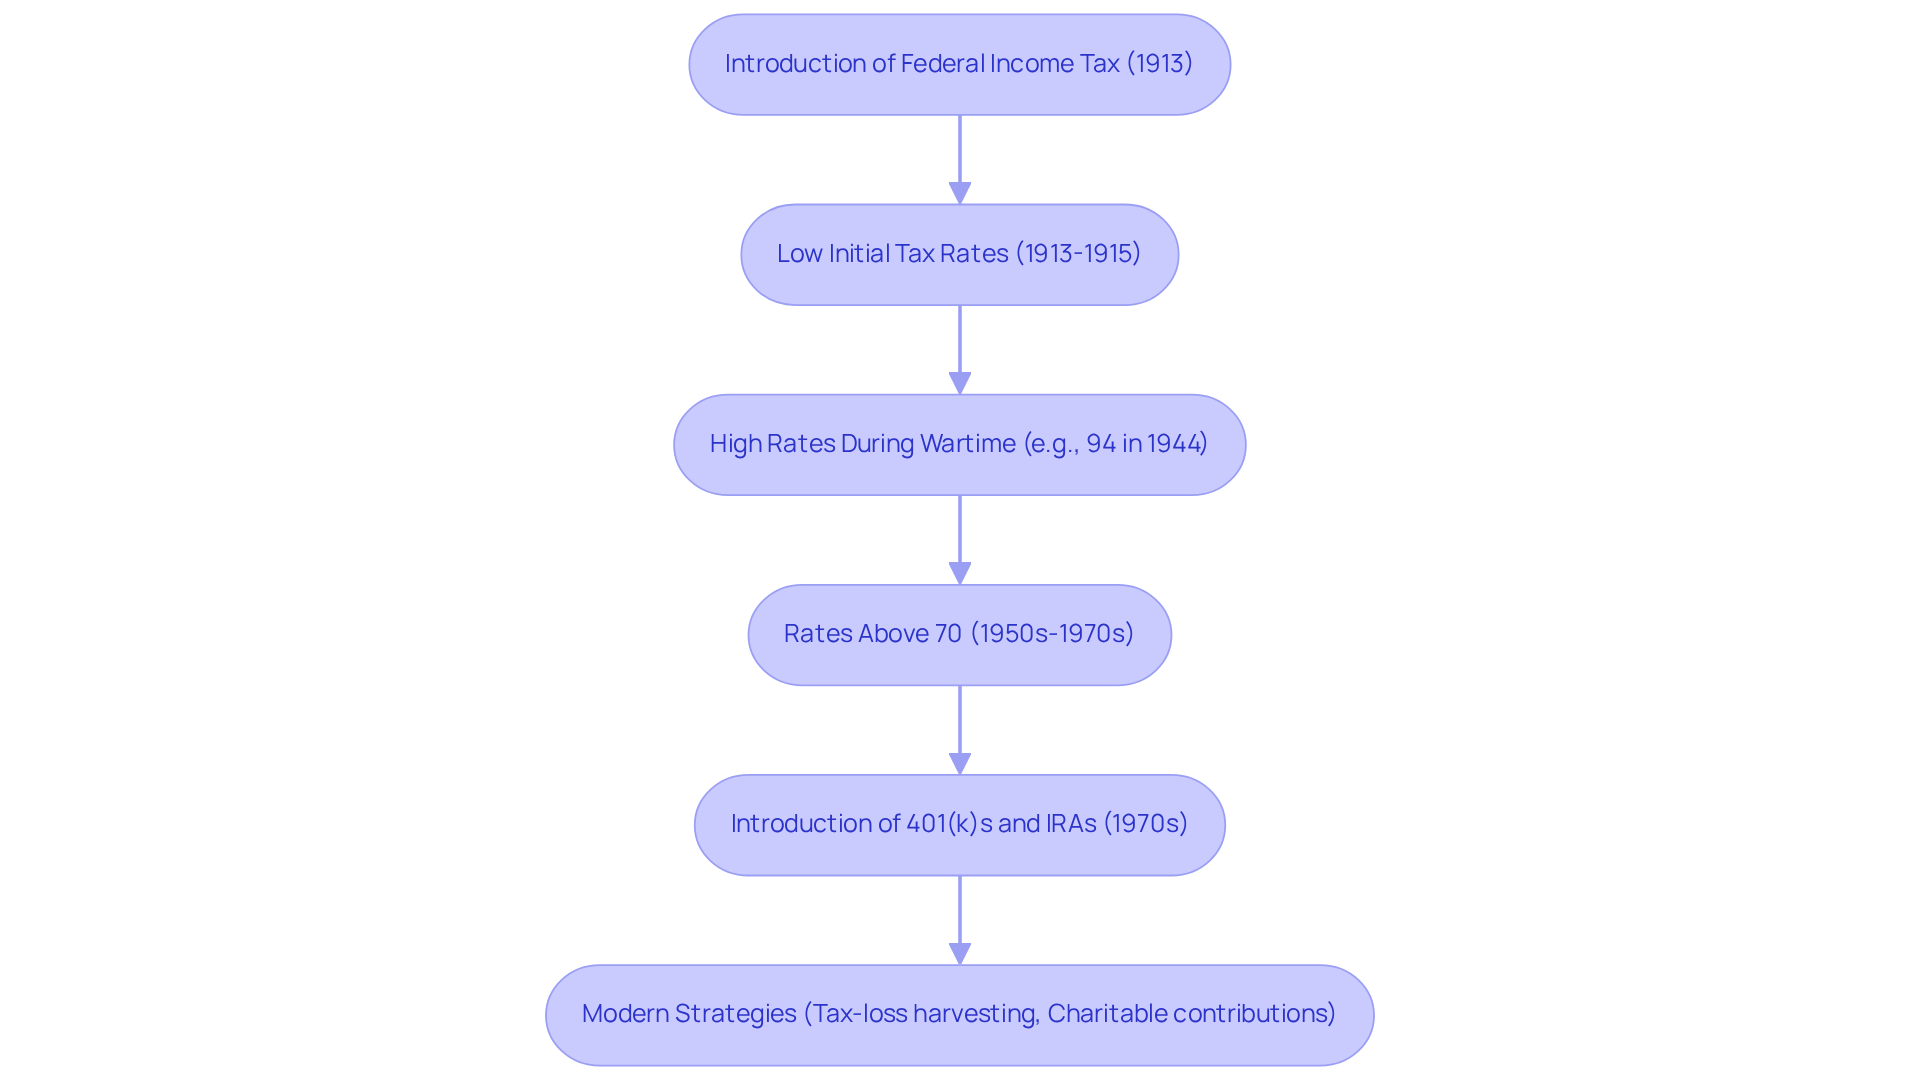
Imagine navigating a maze of tax laws while trying to secure your family’s financial future. The evolution of the high income tax strategy for high income earners in the United States began with the introduction of the federal income tax in 1913, following the ratification of the 16th Amendment. At first, tax rates were low. But as the government needed funds for various initiatives, especially during wartime, those rates climbed significantly. For instance, the highest federal tax rate reached 94 percent in 1944 on taxable earnings exceeding $200,000, which is roughly equivalent to about $2.5 million today. This high rate was part of a broader trend where top rates remained above 70 percent from the 1950s to the 1970s.
As tax rates varied, high-income earners adjusted their approaches in line with a high income tax strategy for high income earners. The introduction of tax-deferred accounts like 401(k)s and IRAs in the 1970s marked a significant shift, providing new avenues for tax savings. More recently, methods such as tax-loss harvesting and charitable contributions have gained traction as a high income tax strategy for high income earners, enabling them to navigate complex tax codes while enhancing their after-tax income.
Understanding this history is important for families like yours, as it highlights the need for proactive tax planning in a constantly changing environment. Imagine feeling overwhelmed by the ever-changing tax laws and wondering how to keep your family’s finances secure. The ability to adjust to evolving tax regulations and rates can greatly influence your financial results. If you don’t stay informed, you might miss out on savings that could really help your family thrive. Together, we can navigate this journey and ensure your family’s financial future is bright.
Key Components of Effective High-Income Tax Strategies
Imagine feeling confident about your family’s financial future, knowing you’re making the most of every dollar you earn. An effective high income tax strategy for high income earners encompasses several key components that can help you navigate this journey with ease.
-
Maximizing Retirement Contributions: As a high-income earner, you can feel empowered by fully utilizing tax-advantaged retirement accounts, like 401(k)s and IRAs. These accounts not only help reduce your taxable income but also play a crucial role in building wealth for your family. In 2024, around 62% of Americans reported owning stock, highlighting how important these accounts are for financial growth.
-
Tax-Loss Harvesting: Imagine selling an investment at a loss to balance out gains from another. This simple strategy can save you thousands in taxes! Many families feel overwhelmed by tax strategies and miss out on potential savings simply because they don’t know where to start. By understanding this approach, you can take control of your tax obligations.
-
Charitable Contributions: Donating to qualified charities not only supports good causes but also provides significant tax deductions. This can be especially advantageous for high-income families like yours, as implementing a high income tax strategy for high income earners can help lower taxable earnings while making a positive impact in your community.
-
Utilizing Health Savings Accounts (HSAs): HSAs offer tax-free contributions, growth, and withdrawals for qualified medical expenses, making them a powerful tool for tax savings. When you contribute to HSAs, you can reduce your taxable income and enjoy immediate tax benefits, which is a win-win for your family.
-
Investment in Tax-Efficient Funds: Choosing investments that minimize tax implications, such as index funds or ETFs, can enhance your after-tax returns. Over the past 30 years, an average of 30% of stocks in the S&P 500 have finished the year with negative returns, emphasizing the need for tax-efficient investment strategies.
When you weave these strategies into your family’s financial planning, you can effectively manage your tax liabilities and enhance your overall financial health. Continuous monitoring and strategic adjustments can lead to significant long-term benefits, particularly when applying a high income tax strategy for high income earners. With the right strategies in place, you can create a brighter financial future for your family, one step at a time. Seeking professional assistance, like that offered by Bright Advisers, can help you optimize your wealth accumulation potential and address the financial challenges you face. We’re here for you, ready to support you on this journey.
Conclusion
Imagine the worry of not knowing if you’re making the best financial choices for your family. Navigating tax obligations can feel overwhelming, especially when you’re trying to secure your family’s financial future. When families learn about effective tax strategies, they can keep more of their hard-earned money, which is so important for their future. Taking these steps not only protects your family’s wealth but also helps you make choices that truly reflect your family’s dreams and values.
These strategies can ease the burden of taxes and support your family’s overall financial well-being. Take Emily and Mark, for example. By working with Bright Advisers, they found peace of mind and a clearer path to their financial goals. With tax laws changing all the time, it’s important for families to stay informed and take charge of their planning. Taking action today can open doors to a brighter financial future for your family, filled with hope and security.
Working with a caring fiduciary advisor like Bright Advisers can help you navigate these complexities, ensuring your family’s financial decisions are wise and beneficial for years to come. Together, we can navigate these complexities and build a secure financial future for your loved ones.
Frequently Asked Questions
What are high-income tax strategies for high-income earners?
High-income tax strategies are methods designed to help high-earning families reduce their taxable income and retain more of their earnings. These strategies can include maximizing retirement account contributions, tax-loss harvesting, and being aware of common tax planning mistakes.
Why are these tax strategies important for families with young kids?
These strategies are essential for families with young kids because they not only lower taxable amounts but also help safeguard wealth for future generations. This allows families to retain a larger portion of their income for important needs like education or retirement.
How much can high-earning individuals contribute to retirement accounts in 2026?
In 2026, high-earning individuals can contribute up to $24,500 pre-tax to retirement accounts like 401(k)s, which can significantly reduce their taxable earnings.
What is tax-loss harvesting and how does it benefit families?
Tax-loss harvesting is a strategy that allows families to offset capital gains by selling underperforming assets. This method can greatly lessen the overall tax burden, as the IRS permits offsetting up to $3,000 in ordinary income annually through this approach.
Can you provide an example of how families can benefit from these strategies?
For instance, Emily and Mark partnered with Bright Advisers to navigate their financial complexities. They learned to maximize their deductions, reduce debt, and manage cash flow, which optimized their financial well-being and allowed them to choose their career paths based on their desired work-life balance.
What common tax planning mistakes should families be aware of?
Families should be aware of mistakes such as failing to report Roth conversions or missing deductions for failed startups. Being mindful of these errors can enhance tax efficiency.
Why is it important to take charge of tax planning year-round?
Taking charge of tax planning year-round simplifies financial lives and paves the way for a secure future filled with possibilities. Proactive steps can lead to potential tax reductions, especially with changes set to occur in 2026.
What should families do to ensure a brighter financial future?
Families should act now by implementing effective tax strategies, maximizing deductions, and being proactive in their tax planning to secure a brighter financial future filled with opportunities and peace of mind.
List of Sources
- Defining High-Income Tax Strategies
- Top Tax Strategies for High-Income Earners (https://therealestatecpa.com/blog/top-tax-strategies-for-high-income-earners)
- 10 Tax Strategies for High-Income Earners to Reduce Taxable Income (https://milestonefinancialplanning.com/blog/10-tax-strategies-for-high-income-earners-to-reduce-taxable-income)
- Tax Planning for High Income Earners: Strategies to Preserve and Grow Wealth – Towerpoint Wealth (https://towerpointwealth.com/tax-planning-for-high-income-earners-strategies-to-preserve-and-grow-wealth)
- Beyond the Basics: Tax strategies for High Income Earners (https://modernfamilyfinance.com/beyond-the-basics-tax-strategies-for-high-income-earners)
- How to Reduce Taxable Income for High Earners in 2026 (https://lewis.cpa/blog/tax-strategies-for-high-income-earners-maximize-savings-and-financial-success)
- Context and Importance of High-Income Tax Strategies
- Summary of the Latest Federal Income Tax Data, Tax Year 2022 (https://taxfoundation.org/data/all/federal/latest-federal-income-tax-data-2025)
- Income Taxes (https://advocacy.calchamber.com/policy/issues/income-taxes)
- Who Pays? 7th Edition (https://itep.org/whopays-7th-edition)
- California Tax Brackets 2026: See Your Exact Tax Rate by Income (https://paycheckcalculatorcalifornia.com/california-tax-brackets-2026)
- California State Taxes: What You’ll Pay in 2026 (https://aarp.org/states/california/state-tax-guide)
- Historical Development of High-Income Tax Strategies
- LibGuides: Federal Tax Research: Tax Quotes (https://nyulaw.libguides.com/c.php?g=773839&p=7009928)
- History of Federal Income Tax Rates: 1913 – 2026 (https://bradfordtaxinstitute.com/Free_Resources/Federal-Income-Tax-Rates.aspx)
- Memorable Tax Quotes – Fishman, Larsen & Callister | Attorneys at Law (https://flclaw.net/memorable-tax-quotes)
- Historical Income Tax Rates (https://wolterskluwer.com/en/expert-insights/whole-ball-of-tax-historical-income-tax-rates)
- Key Components of Effective High-Income Tax Strategies
- Continuous tax-loss harvesting yields more potential for tax benefits (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/continuous-tax-loss-harvesting-yields-more-potential-for-tax-savings)
- Tax-Loss Harvesting Strategies: How They Work (https://am.gs.com/en-us/advisors/campaign/tax-loss-harvesting-strategies-how-they-work)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- What Percentage of Americans Have a Retirement Savings Account? (https://news.gallup.com/poll/691202/percentage-americans-retirement-savings-account.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading