

Overview
Taxable accounts serve as investment vehicles that allow families to navigate the complexities of taxation on interest, dividends, and capital gains. They provide flexibility and control, free from penalties for withdrawals or trading, which can be a comforting thought for many. Imagine having the freedom to manage your investments without the worry of immediate penalties. This article highlights the significance of these accounts for achieving both short-term and long-term financial goals, emphasizing features such as liquidity and strategic tax management.
It’s important to understand how these accounts can facilitate the transfer of wealth to your heirs, making them a valuable resource for effective family financial planning. By incorporating taxable accounts into your strategy, you can create a foundation that supports your family’s future. Together, we can navigate this journey toward financial security, ensuring that your family’s values and priorities are at the forefront of your planning efforts.
We’re here for you, ready to assist in making informed decisions that resonate with your family’s needs. With the right tools and guidance, you can embrace the opportunities that taxable accounts offer, enhancing your family’s financial well-being.
Key Highlights:
- Taxable accounts are investment vehicles subject to IRS tax regulations, where interest, dividends, and capital gains are taxed in the year realized.
- They offer flexibility and control, allowing deposits, trading, and withdrawals without penalties, making them suitable for both short-term and long-term goals.
- In 2025, an estimated 40% of investors are expected to utilize taxable brokerage services, highlighting their growing role in personal finance.
- Key benefits of taxable accounts include liquidity for unexpected expenses, strategic tax management, and the ability to transfer wealth to heirs without mandatory distributions.
- Different types of taxable accounts include brokerage accounts, savings accounts, CDs, money market funds, and taxable investment funds for children, each serving unique family financial objectives.
- Effective tax strategies for taxable accounts include tax-loss harvesting, holding investments long-term for lower tax rates, investing in tax-efficient funds, and planning withdrawals strategically.
- Understanding tax implications is crucial for families to make informed investment choices and enhance their overall financial strategies.
Introduction
In the intricate world of personal finance, taxable accounts emerge as versatile investment vehicles that empower families to take control of their financial futures. Imagine having the freedom to manage your investments without the constraints of penalties or required minimum distributions. These accounts are ideal for both short-term goals and long-term wealth accumulation.
As more families recognize their significance—projected to encompass 40% of investors by 2025—it’s important to understand the unique characteristics, types, and strategic implications of taxable accounts. Together, we can navigate financial challenges, optimize tax liabilities, and ultimately secure your family’s financial legacy.
Define Taxable Accounts: Key Characteristics and Functions
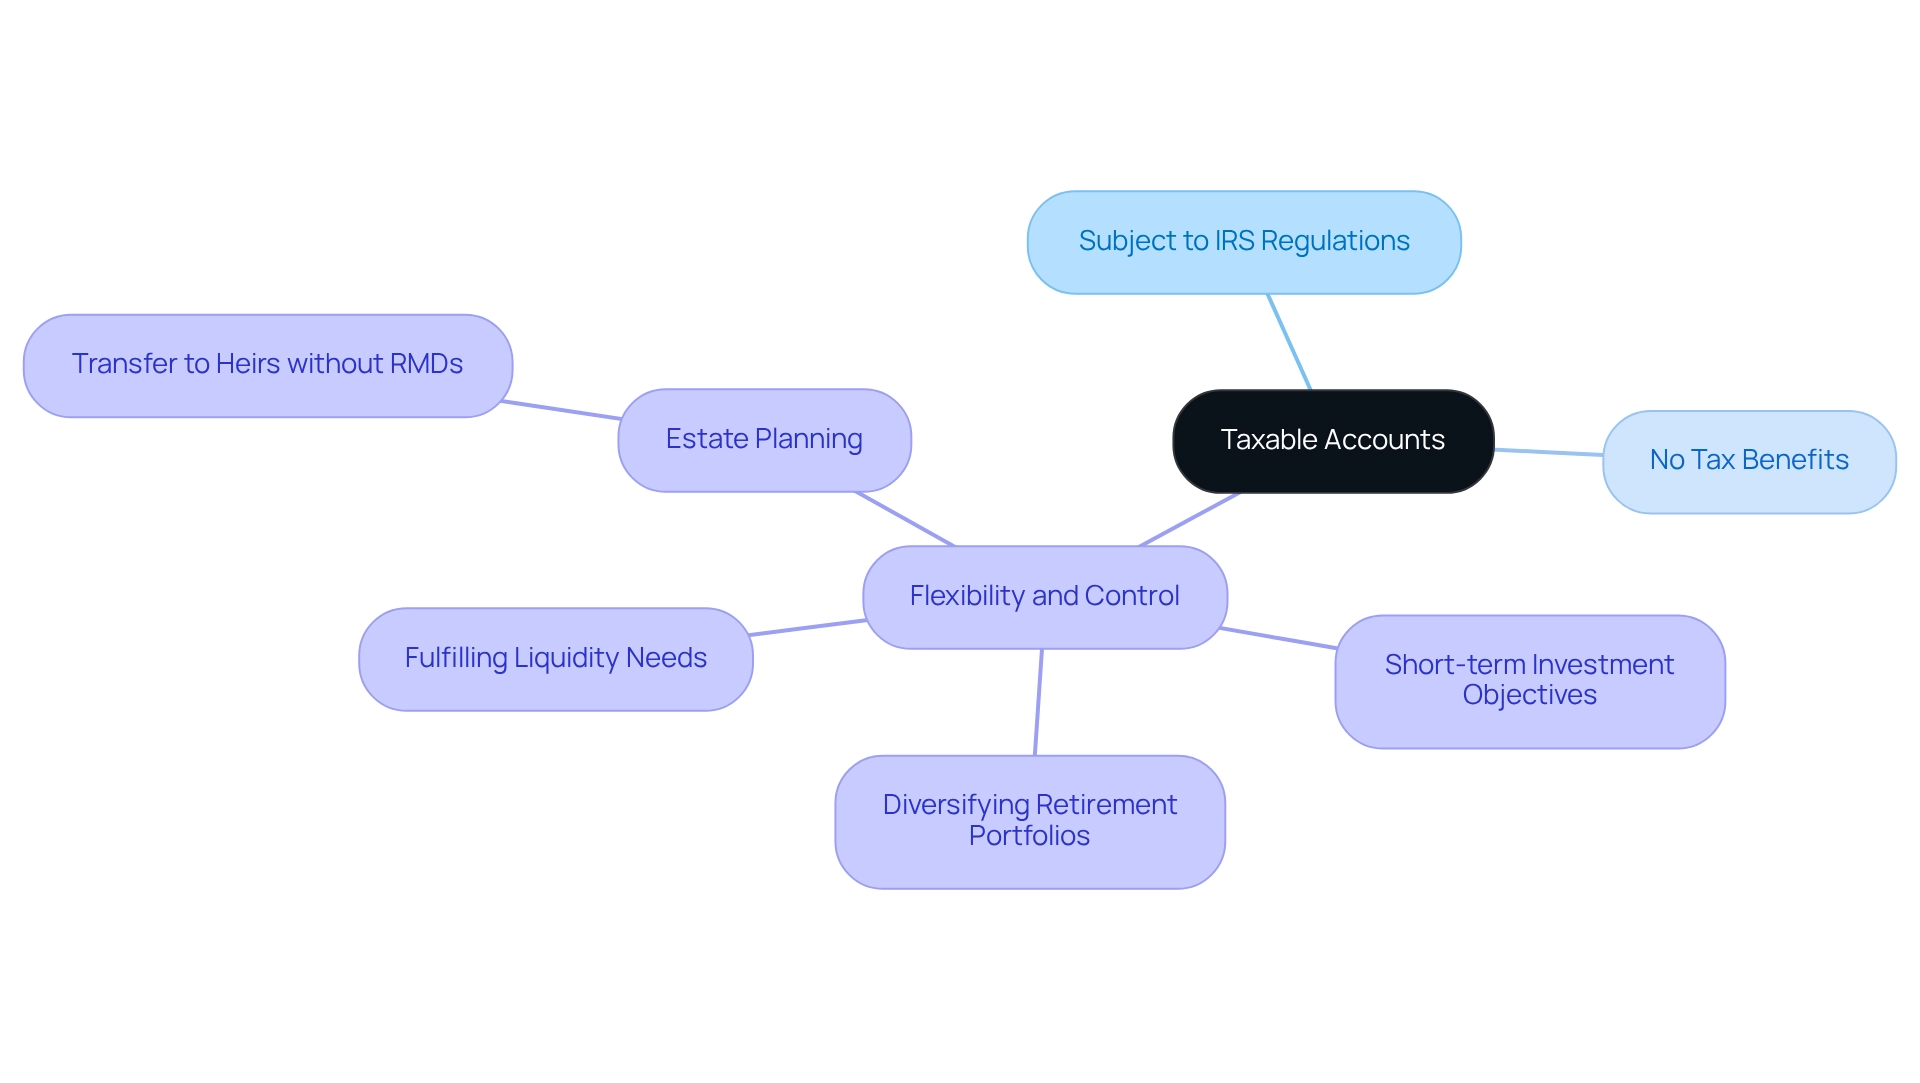
Navigating the world of investments can feel overwhelming, especially for young parents concerned about their family’s future. Understanding what is a taxable account involves recognizing that it is an investment vehicle subject to standard IRS tax regulations, meaning any interest, dividends, or capital gains earned are taxed in the year they are realized. Unlike tax-advantaged options like IRAs or 401(k)s, what is a taxable account does not provide specific tax benefits. However, they provide you with considerable flexibility and control over your resources. You can deposit funds, trade various securities, and withdraw money without penalties, making these options suitable for both short-term and long-term financial goals.
Imagine if you could take charge of your financial future. In 2025, approximately 40% of investors are expected to use taxable brokerage services, highlighting their growing importance in personal finance. These financial products are particularly beneficial for:
- Short-term investment objectives
- Diversifying retirement portfolios
- Fulfilling liquidity needs
- Planning for estates
They allow for strategic financial management without the restrictions typically associated with tax-advantaged options.
Key features of investment vehicles subject to taxes include the ability to transfer them to heirs without mandatory minimum distributions (RMDs), ensuring a smooth transfer of wealth. This aspect is vital for families aiming to establish and preserve multi-generational wealth. Additionally, understanding what is a taxable account provides the flexibility to access resources as needed, aligning with various financial strategies that are especially relevant for families managing their budgets.
At Bright Advisers, we understand the importance of incorporating tax optimization into your wealth management journey. Take, for example, Allison and Brian, a couple striving to enhance their economic potential. Through effective tax planning, they secured their children’s future by funding their education and positioned themselves to retire earlier. Their experience illustrates how thoughtful tax planning can alleviate financial stress and help families achieve their long-term aspirations.
Expert opinions emphasize that investment portfolios should be a cornerstone of your financial strategy. As Ben Graham wisely noted, “The individual investor should act consistently as an investor and not as a speculator,” highlighting the significance of a disciplined approach to investing. Furthermore, Templeton’s caution against ignoring past investment patterns serves as a reminder of the risks tied to complacency in your investment strategies. By leveraging the unique features of taxable portfolios, families can manage their investments effectively while keeping their long-term financial goals in focus.
Together, we can navigate this journey, ensuring your family’s financial future is secure and bright.
Contextualize Taxable Accounts: Importance in Wealth Management
Taxable portfolios play a vital role in wealth management, offering a flexible investment choice that enhances tax-advantaged options. Imagine being able to invest after-tax dollars—this is essential for achieving various family goals, like saving for your child’s education or building a retirement nest egg. In 2025, statistics indicate that many families are using investment funds specifically for education savings, underscoring their significance in long-term budgeting.
The availability of resources without penalties makes these funds particularly appealing for families who may face unexpected expenses. This liquidity empowers better financial management during critical life events. Moreover, investment portfolios provide strategic advantages in managing tax obligations. Families can control the timing of recognizing gains or losses, optimizing their overall tax situation and enhancing their wealth management strategies.
Consider the experiences of families who have maxed out their retirement contributions. They often turn to what is a taxable account to save effectively, ensuring they meet their retirement savings targets. This approach not only addresses immediate financial needs but also supports long-term wealth growth. Take Emily and Mark, a couple in their mid-thirties. By partnering with Bright Advisers, they received a comprehensive evaluation of their financial situation, which led to tailored strategies, including debt reduction and cash flow management. This holistic financial strategy involved utilizing what is a taxable account to achieve their goal of financial independence, allowing them to make work optional while planning for their children’s education, highlighting that understanding what is a taxable account is essential for reaching financial objectives. They serve as a crucial resource for families navigating the complexities of budgeting while raising children, enabling a more thorough approach to wealth management. Additionally, Bright Advisers’ commitment to minimizing fund fees enhances accessibility for families, reinforcing their mission to empower young families through effective money management. Together, we can navigate this journey towards financial security and peace of mind.
Explore Types of Taxable Accounts: Variations and Comparisons
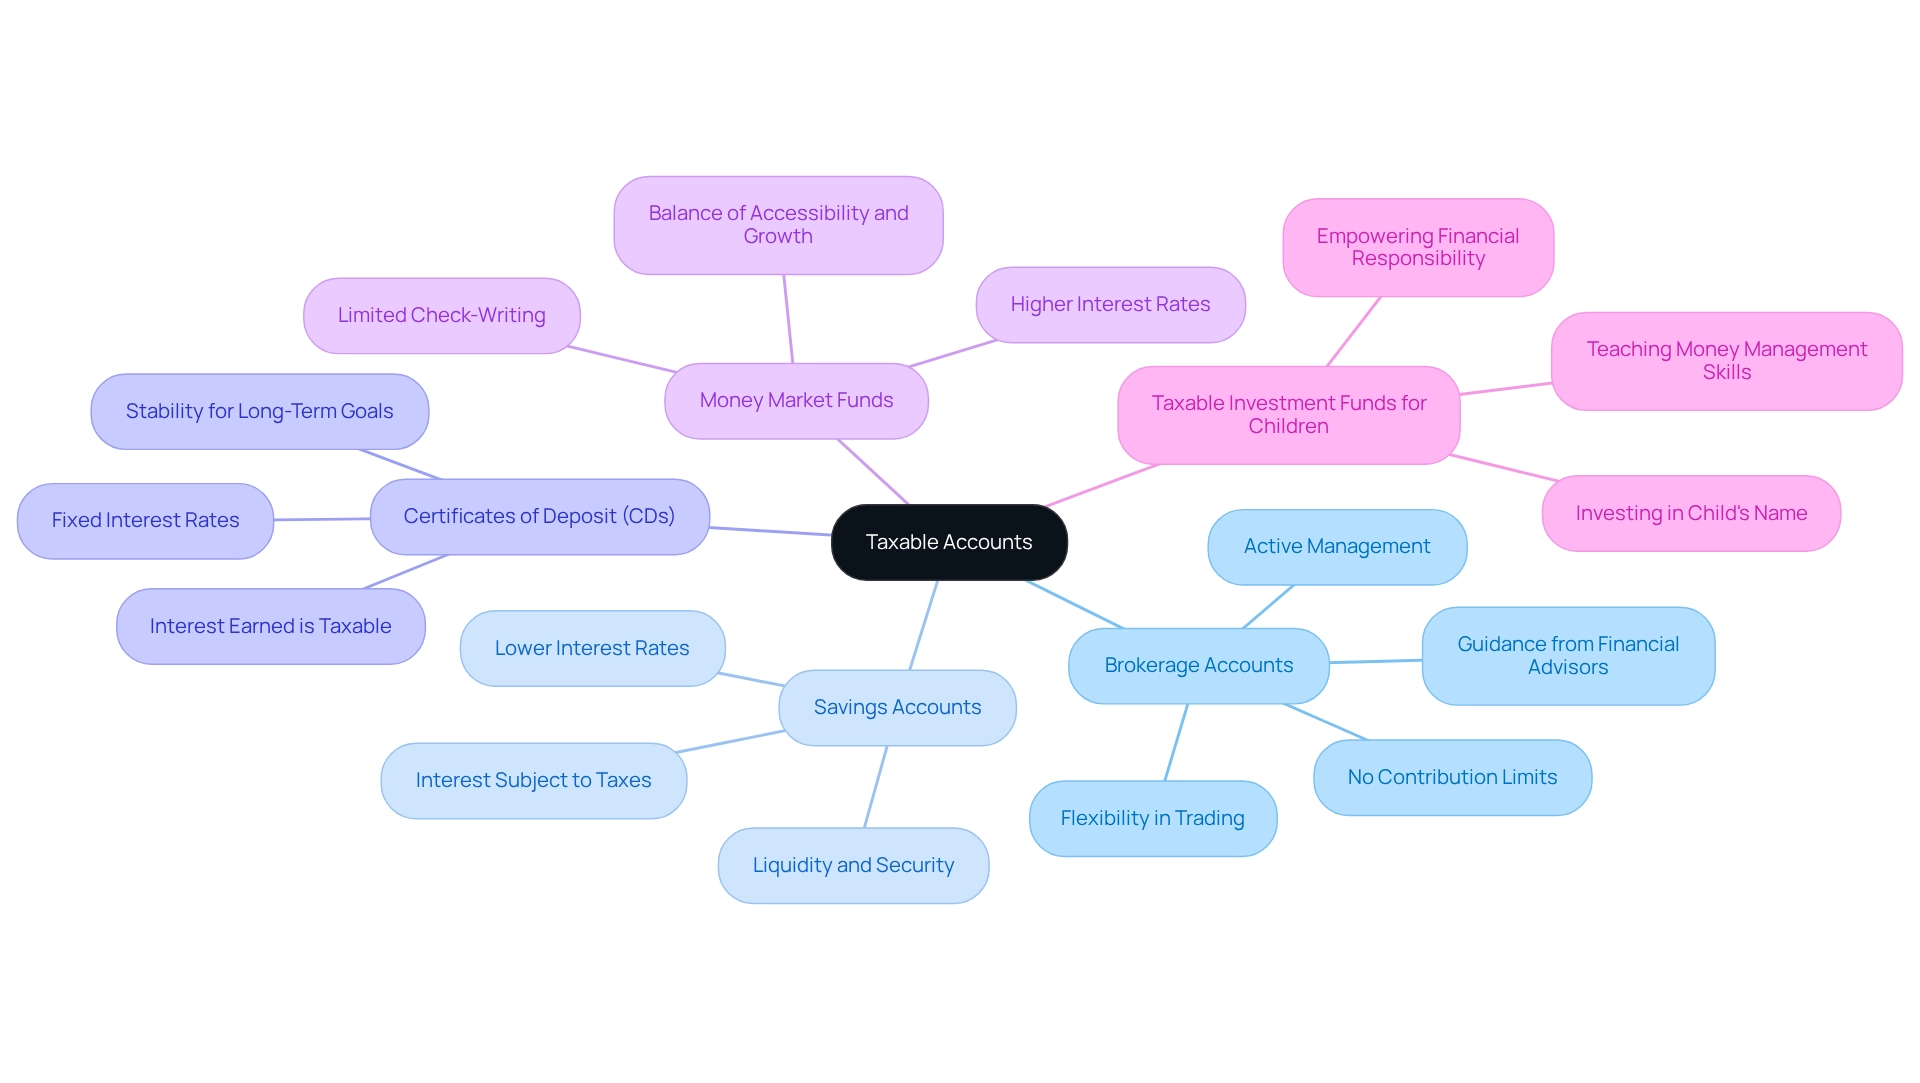
Taxable holdings come in various forms, each tailored to meet specific investment strategies and family objectives. Let’s explore some of the most common types:
-
Brokerage Accounts: These accounts provide the flexibility to buy and sell a wide range of securities—like stocks, bonds, and mutual funds—without contribution limits. They are ideal for families eager to actively manage their investments and enhance their financial potential. For instance, consider Jay and Emma, who successfully navigated their financial journey with the guidance of Bright Advisers. This firm offers personalized investment strategies to help clients maximize returns while keeping costs low through minimal fund fees.
-
Savings Accounts: While they typically offer lower interest rates, savings accounts serve as a safe haven for cash, allowing families to earn interest that is subject to taxes. These accounts are perfect for those prioritizing liquidity and security, ensuring that you can meet urgent financial needs while planning for the future.
-
Certificates of Deposit (CDs): These time deposits provide fixed interest rates over a specified term, making them a stable investment option. Though the interest earned is taxable, they are favored for their predictability, offering families peace of mind as they save for long-term goals.
-
Money Market Funds: Combining features of both savings and checking accounts, money market funds offer higher interest rates along with limited check-writing capabilities. This makes them a flexible choice for families seeking to balance accessibility with growth potential.
-
Taxable Investment Funds for Children: These funds can be established in a child’s name, allowing parents to invest for their future while teaching essential money management skills. This approach empowers young families to instill financial responsibility in their children from an early age.
To understand what is a taxable account, it’s important to note that each type of taxable financial arrangement presents unique benefits and challenges. For example, families may find brokerage services advantageous for long-term investment strategies. In fact, the average direct deposit refund in 2025 was $3,023, reflecting a growing trend in family investments, up 2.6% from 2024. Understanding what is a taxable account and the tax implications of financial instruments—such as capital gains, dividends, and interest—is crucial for making informed choices. A case study titled “Tax Implications of a Taxable Brokerage Investment” sheds light on how investments in a brokerage account are taxed, including the differences between short-term and long-term capital gains taxation. This knowledge helps families navigate their investment strategies effectively. As Warren Buffett wisely stated, “If anything, taxes for the lower and middle class and maybe even the upper middle class should even probably be cut further,” underscoring the importance of comprehending tax implications in relation to investment strategies. Ultimately, families should thoughtfully evaluate their financial goals, risk tolerance, and liquidity needs when selecting the most suitable investment option. Remember, we’re here for you—together, we can navigate this journey.
Analyze Tax Implications: Strategies for Effective Use of Taxable Accounts
To maximize the benefits of taxable accounts, families can embrace several effective tax strategies that truly make a difference:
- Tax-Loss Harvesting: Imagine selling underperforming investments to offset gains from profitable ones, which can lower your taxable income. This thoughtful approach can significantly ease your overall tax burden, allowing you to manage your capital gains more strategically. For instance, Jay and Emma, who were looking to reduce financial stress, found that tax-loss harvesting helped them navigate their economic landscape more effectively, ultimately leading to a more stable financial future.
- Holding Investments Long-Term: By holding onto investments for over a year, families can benefit from lower long-term capital gains tax rates. For 2025, these rates are generally more favorable, making this simple shift in strategy a pathway to substantial tax savings. Emily and Mark, for example, improved their financial situation by focusing on long-term investments, giving them the freedom to choose their career paths and achieve greater economic stability.
- Investing in Tax-Efficient Funds: Choosing index funds or tax-managed funds can help reduce tax liabilities, as these funds typically generate fewer taxable distributions. This option is especially beneficial for families looking to enhance their after-tax returns. Just like Allison and Brian, who optimized their financial potential through careful tax planning, you too can ensure your children’s future while enjoying more quality time together.
- Utilizing Tax-Deferred Accounts: Understanding what is a taxable account, as finding a balance between taxable accounts and tax-deferred accounts offers families greater flexibility in managing withdrawals and tax implications. This strategy allows for a more comprehensive approach to financial planning, ensuring that you can secure your children’s future while preparing for your retirement.
- Planning Withdrawals Strategically: Timing your withdrawals during years of reduced income can help minimize your overall tax obligations. This proactive approach ensures that you keep more of your hard-earned money, aligning with the goals of individuals like Jay and Emma, who strive to balance present responsibilities with long-term aspirations.
As Chad Chubb wisely notes, “While monetary planning for doctors is a long process that relies heavily on personal circumstances and preferences, we break it down into a simple five-step process to get you…” This highlights the importance of a structured approach to financial planning, especially when considering tax strategies.
By applying these thoughtful tactics, families can effectively enhance their investable accounts, aligning them with broader financial goals while managing tax consequences with care. The benefits of tax-loss harvesting, for example, can lead to a significant reduction in taxable capital gains, making it an essential part of a well-rounded investment strategy. Moreover, the insights from these relatable stories illustrate how understanding and planning for tax implications can empower families to manage their investment gains and optimize their financial strategies. Remember, together, we can navigate this journey toward a secure financial future.
Conclusion
Taxable accounts are truly a cornerstone of effective personal finance and wealth management, offering families the flexibility and accessibility needed to navigate their financial journeys. Imagine being able to manage your finances without the constraints often tied to tax-advantaged accounts. By understanding the different types of taxable accounts—like brokerage accounts and savings accounts—you can tailor your strategies to meet both your short-term needs and long-term aspirations.
It’s important to recognize the significance of strategic tax planning. Techniques such as tax-loss harvesting and a focus on long-term investments can help families minimize tax liabilities while maximizing investment returns. Consider the stories of individuals like Allison and Brian, who demonstrate how thoughtful financial management can enhance security and help achieve family goals.
As more families begin to see the value of taxable accounts—projected to encompass 40% of investors by 2025—integrating these accounts into comprehensive financial strategies becomes increasingly vital. By leveraging the advantages of taxable accounts and implementing effective tax strategies, you can build a solid financial foundation, ensuring a prosperous future for your family for generations to come. Remember, together, we can navigate this journey toward financial security.
Frequently Asked Questions
What is a taxable account?
A taxable account is an investment vehicle that is subject to standard IRS tax regulations, meaning any interest, dividends, or capital gains earned are taxed in the year they are realized.
How do taxable accounts differ from tax-advantaged options like IRAs or 401(k)s?
Unlike tax-advantaged options, taxable accounts do not provide specific tax benefits but offer considerable flexibility and control over resources, allowing for deposits, trading of securities, and withdrawals without penalties.
What are the benefits of using taxable accounts?
Taxable accounts are beneficial for short-term investment objectives, diversifying retirement portfolios, fulfilling liquidity needs, and planning for estates.
Can assets in a taxable account be transferred to heirs?
Yes, assets in a taxable account can be transferred to heirs without mandatory minimum distributions (RMDs), facilitating a smooth transfer of wealth.
How can taxable accounts help families manage their finances?
Taxable accounts provide the flexibility to access resources as needed, aligning with various financial strategies that are especially relevant for families managing their budgets.
What role does tax optimization play in wealth management?
Tax optimization is crucial in wealth management as it can enhance financial potential, secure futures for children, and help families achieve long-term aspirations through effective tax planning.
What is the importance of a disciplined approach to investing?
A disciplined approach to investing is significant because it helps individual investors act consistently and avoid the risks associated with complacency in their investment strategies.
List of Sources
- Define Taxable Accounts: Key Characteristics and Functions
- When You Should Use a Taxable Brokerage Account (https://smartasset.com/investing/when-you-should-use-a-taxable-brokerage-account)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- 10 Great Investing Quotes to Consider (https://smartasset.com/investing/top-10-investing-quotes-of-all-time)
- Contextualize Taxable Accounts: Importance in Wealth Management
- fidelity.com (https://fidelity.com/viewpoints/investing-ideas/asset-location-lower-taxes)
- T. Rowe Price Personal Investor – Four reasons to save for retirement in a taxable general investing account (https://troweprice.com/personal-investing/resources/insights/4-reasons-to-save-for-retirement-in-a-taxable-account.html)
- Explore Types of Taxable Accounts: Variations and Comparisons
- 2025 tax season wrap up: The final numbers (https://accountingtoday.com/list/tax-filing-season-statistics-for-2025)
- Understanding Taxable Brokerage Accounts vs. IRA (https://sofi.com/learn/content/what-is-a-taxable-account)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- Analyze Tax Implications: Strategies for Effective Use of Taxable Accounts
- Tax-Efficient Investment Management Strategies from Merrill (https://ml.com/tax-managed-strategies.html)
- How To Build a Tax Efficient Taxable Account as a Physician (https://wealthkeel.com/blog/how-to-build-a-tax-efficient-taxable-account-as-a-physician)
- Top 5 tips for managing taxable portfolios | Russell Investments (https://russellinvestments.com/us/blog/top-5-tips-for-managing-taxable-portfolios)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading