

Overview
Imagine a financial strategy that empowers you to take control of your family’s future. Infinite banking is just that—a way for individuals to utilize whole life insurance policies as a personal banking system. This approach allows you to borrow against the cash value of these policies, providing the flexibility to meet various financial needs as they arise.
Consider the possibilities when you overfund your policy for cash value growth. Not only can you enjoy tax-free benefits, but you can also hear inspiring success stories from families who have embraced this strategy. These stories illustrate how they achieved financial autonomy and managed their resources more effectively.
It’s important to understand that with infinite banking, you’re not just investing in a policy; you’re investing in your family’s future. This strategy can help you navigate financial challenges with confidence, ensuring that you have the means to support your loved ones when it matters most.
Together, we can explore how infinite banking can align with your family values and goals. If you’re ready to take the next step, remember that we’re here for you, supporting you in this journey toward financial empowerment.
Key Highlights:
- Infinite banking is a strategy that allows individuals to use whole life insurance policies as a personal banking system.
- By borrowing against the cash value of their policies, individuals can manage cash flow independently of traditional banks.
- The growing interest in whole life insurance reflects a desire for financial autonomy amid rising credit card interest rates.
- R. Nelson Nash’s book ‘Becoming Your Own Banker’ popularized infinite banking, emphasizing economic independence through whole life policies.
- Key components of infinite banking include specially designed whole life insurance, overfunding for cash value growth, and flexible loan repayment options.
- Benefits of infinite banking include tax-free growth, liquidity for immediate financial needs, and enhanced control over personal finances.
- Potential risks involve high premiums, slow growth of cash value, and the complexity of understanding the strategy.
- Success stories, like that of Emily and Mark, illustrate how families can achieve financial goals through tailored infinite banking strategies.
Introduction
In a financial landscape where traditional banking often falls short, imagine a strategy that empowers you to take control of your finances. The concept of infinite banking emerges as a revolutionary approach, allowing individuals to leverage the cash value of whole life insurance policies. This means you can act as your own banker, providing yourself with liquidity and financial flexibility when you need it most.
As families increasingly seek innovative ways to accumulate wealth and reduce debt, infinite banking offers a compelling alternative that emphasizes financial autonomy. It’s important to understand that this strategy can help you navigate the complexities of modern wealth management while prioritizing what truly matters—your family’s future.
With real-life success stories illustrating its benefits, more and more families are discovering how infinite banking can secure their financial futures. Together, we can navigate this journey, ensuring that you have the support and resources needed to thrive in today’s world. We’re here for you, ready to explore the possibilities that infinite banking can bring to your family’s financial well-being.
Define Infinite Banking: Understanding the Concept
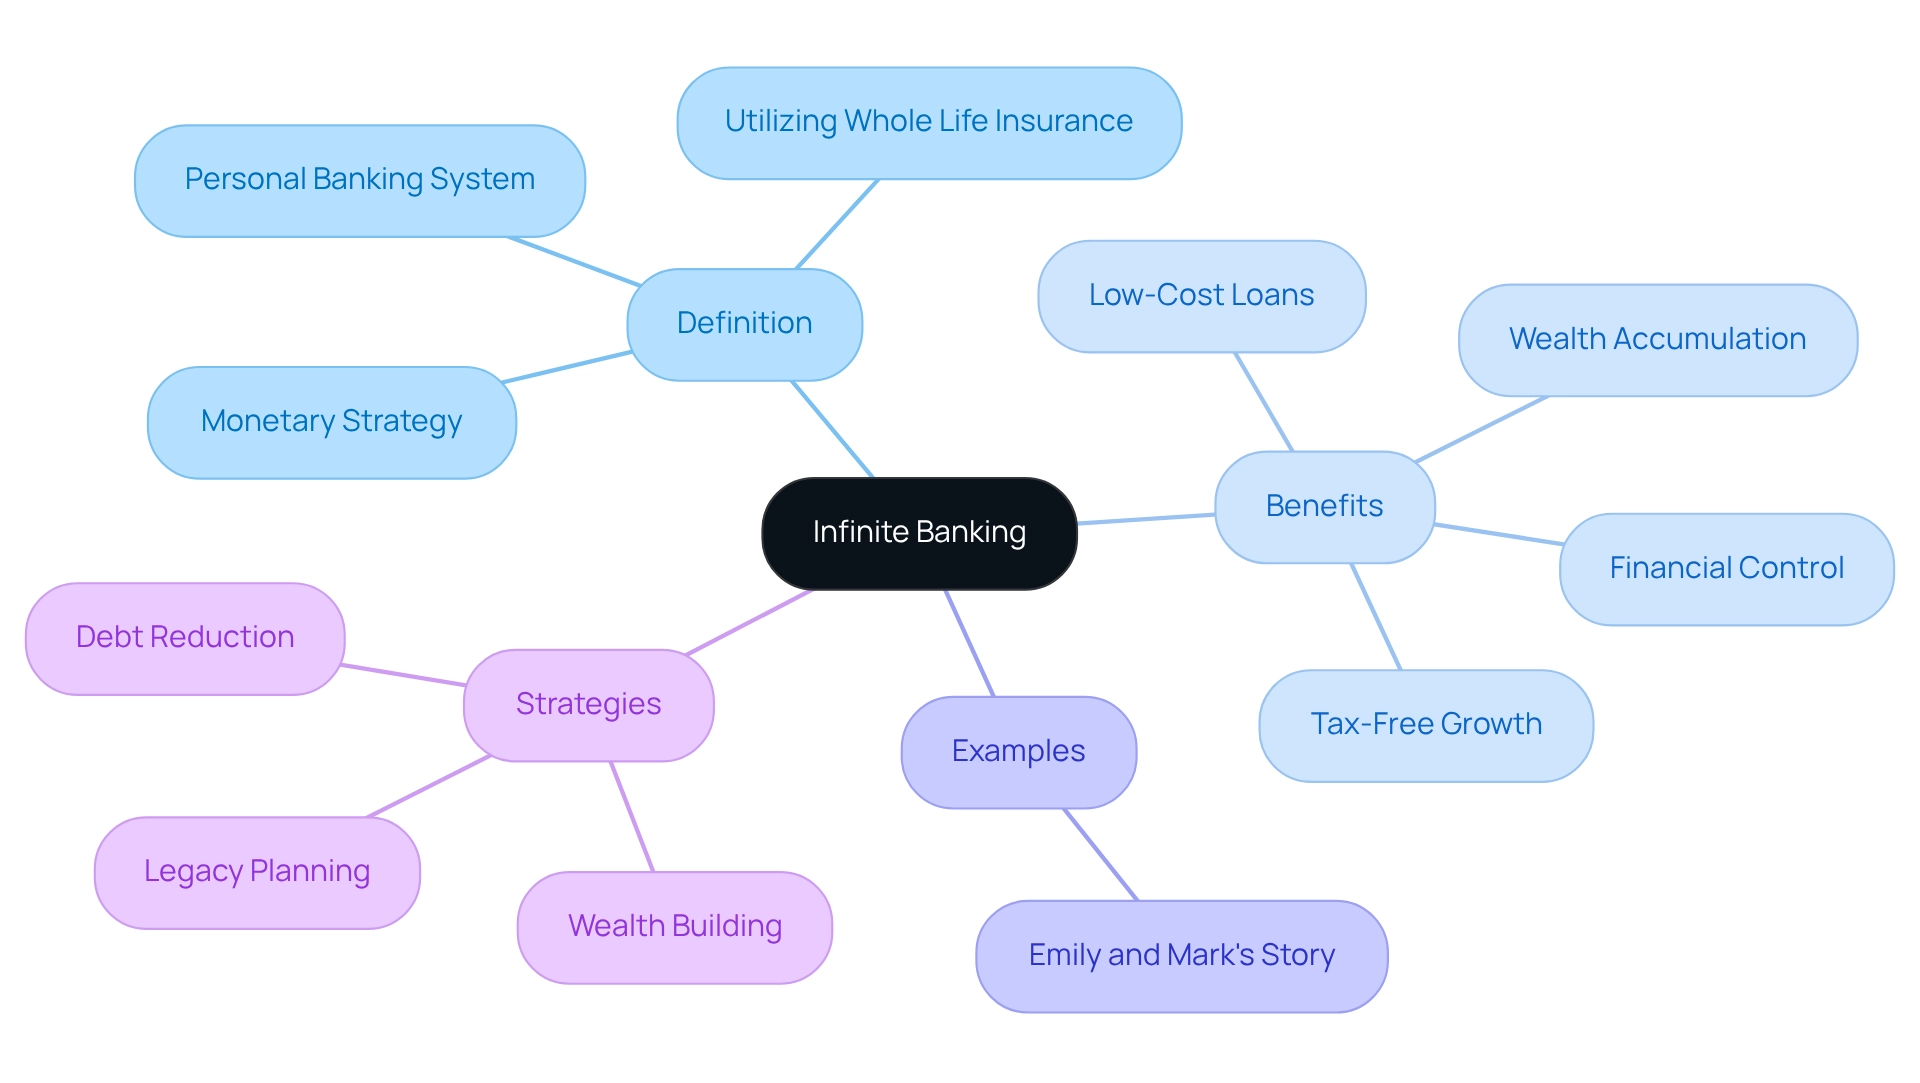
What is infinite banking? It is a monetary strategy that enables individuals to utilize the liquidity of permanent life insurance policies, especially whole life insurance, to create a personal banking system customized to their needs. Imagine being able to borrow against your policy’s monetary worth, allowing you to operate as your own banker. By funding a whole life policy generously, you can access liquidity for various financial needs while permitting your liquid assets to grow. This method emphasizes your financial control, providing a means to manage cash flow independently of conventional financial institutions.
Recent statistics reveal that many individuals are now turning to whole life insurance for cash value accumulation, reflecting a growing desire for financial autonomy. With credit card annual percentage rates (APR) soaring to 20% to 30% or more, families are increasingly seeking strategies, such as what is infinite banking, to reduce debt, build wealth, and plan for future legacies. Developing a personalized infinite financing strategy becomes crucial in this context.
For instance, consider Emily and Mark, a young couple navigating challenging careers. They collaborated with Bright Advisers to craft a comprehensive strategy that utilized whole life insurance for cash value growth. This approach not only safeguarded their invested premiums but also provided the flexibility to manage their finances efficiently, ensuring they could meet their children’s educational needs while preparing for retirement, illustrating what is infinite banking and its benefits for young families.
As fiscal consultants note, this approach can significantly enhance a family’s economic resilience, offering key benefits such as tax-free growth, access to low-cost loans, and the ability to accumulate wealth without relying on conventional financial products. These benefits underscore the compelling nature of what is infinite banking for individuals seeking to secure their financial future, as illustrated by the success stories of families like Emily and Mark who have embraced this innovative wealth management method.
Together, we can navigate this journey towards financial security, ensuring that your family’s needs are met with compassion and understanding. We’re here for you, ready to support you in creating a brighter financial future.
Trace the Origins: History and Evolution of Infinite Banking
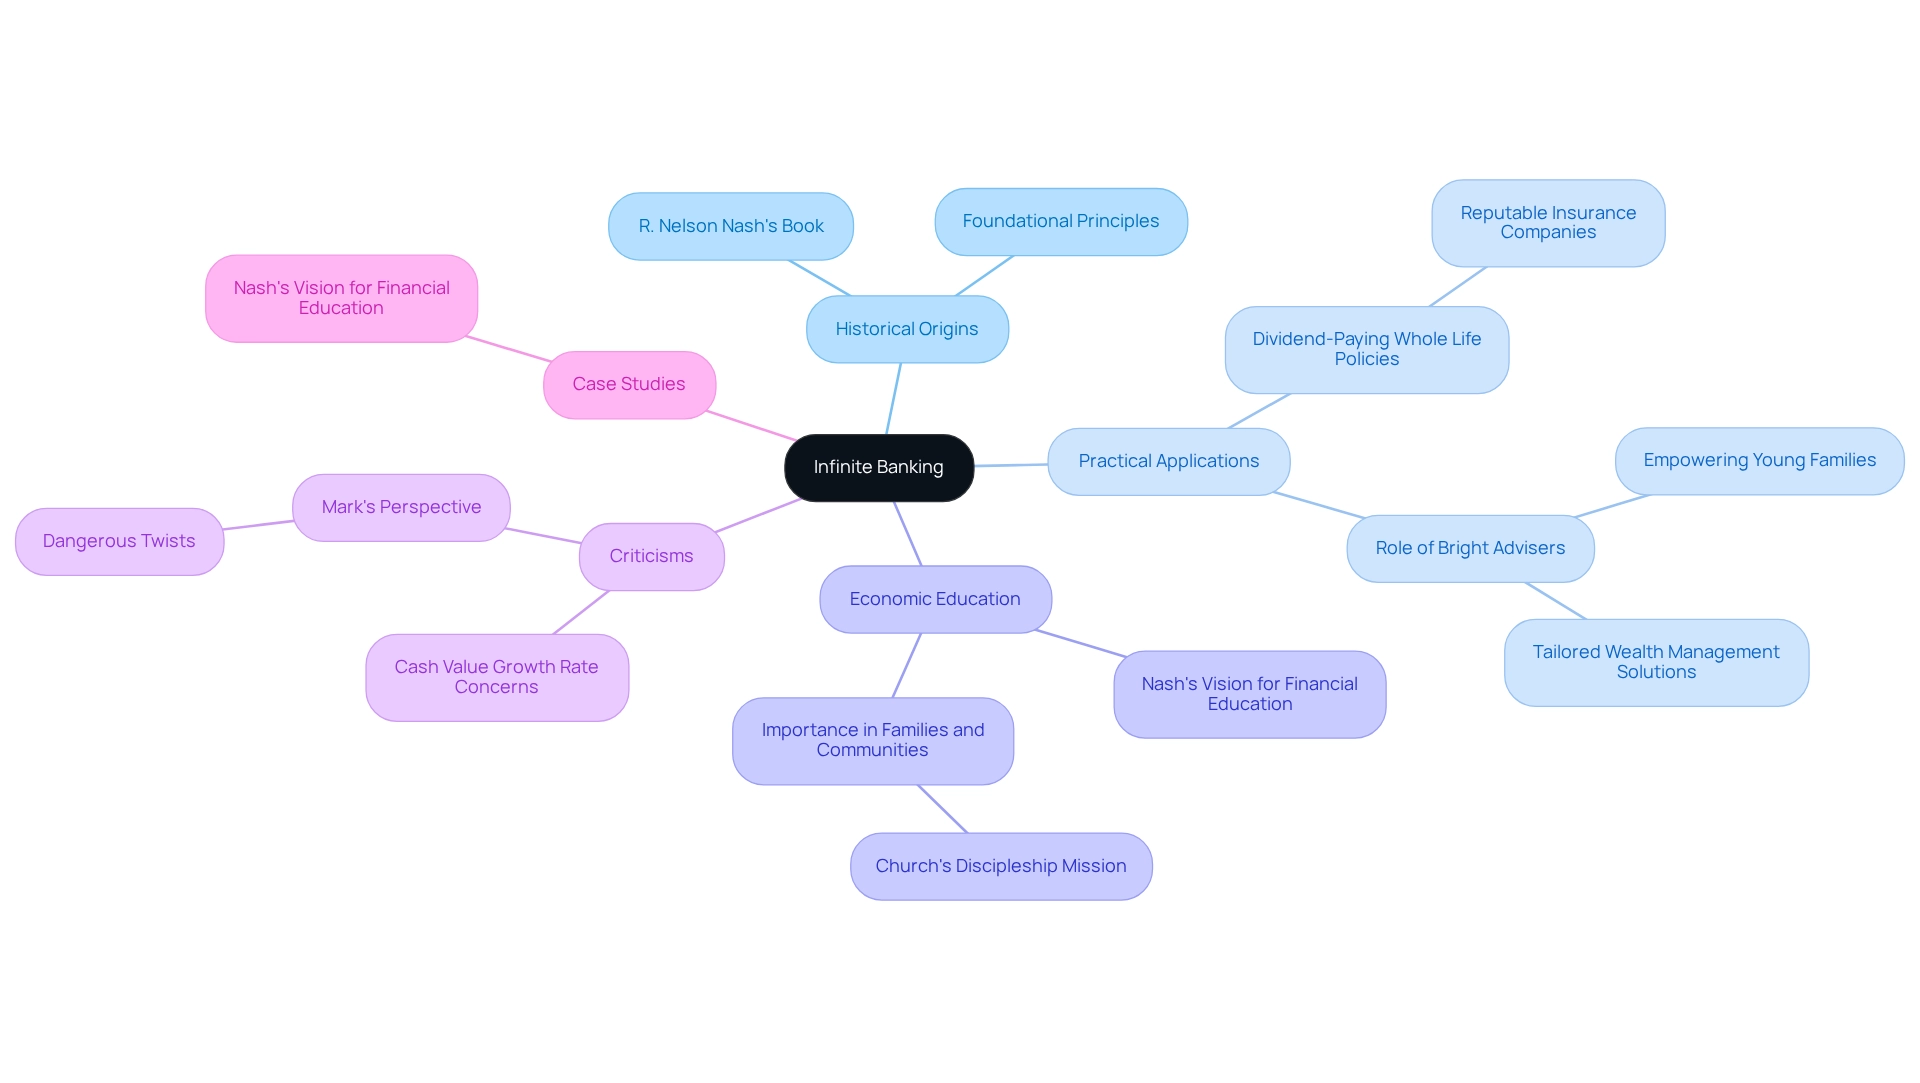
The concept of what is infinite banking gained prominence through R. Nelson Nash’s influential book, ‘Becoming Your Own Banker,’ published in 2000. Yet, the foundational principles have been utilized for over a century, adapting to changing economic conditions. Nash’s strategy emerged as a solution to the challenges posed by unfavorable interest rates and the constraints of traditional financial systems. He encouraged families to consider dividend-paying whole life insurance policies from reputable providers as a means to build wealth and create a personal banking system, highlighting what is infinite banking, which has resonated with many advisors and families seeking innovative ways to manage their finances.
This approach emphasizes economic independence and control, allowing families to leverage their liquid assets for various needs while simultaneously growing their wealth. Bright Advisers embodies this philosophy by offering tailored wealth management solutions that empower young families to achieve financial independence. Through personalized strategies, they help clients like Emily and Mark enhance their financial well-being, reduce debt, and plan for retirement, ultimately providing them the flexibility to make career choices that align with their desired work-life balance.
However, it’s essential to recognize that a critical perspective on the strategy’s effectiveness raises the question of what is infinite banking and whether the cash value growth rate may often fall short of what Infinite Bankers aspire to achieve. Nash’s vision extended beyond mere financial tactics; he believed in the vital role of economic education, particularly within families and faith communities. His advocacy for teaching the principles of infinite finance has fostered a culture of resource management, ensuring that future generations are equipped to apply these concepts effectively.
A significant case study titled ‘Nash’s Vision for Financial Education’ highlights his commitment to economic literacy, underscoring the importance of educating families about these principles, while the evolution of infinite banking has been marked by a growing body of literature, with numerous books sold since 2000, reflecting an increasing interest in alternative economic strategies. This rising interest underscores Nash’s impact in the field. Historical case studies illustrate Nash’s profound influence on contemporary financial practices, showcasing how his teachings have reshaped personal finance.
As the concept of what is infinite banking continues to evolve, it serves as a vital resource for those seeking to navigate the complexities of wealth management and achieve economic independence. Moreover, Nash believed that financial education should be an integral part of the church’s discipleship mission, further highlighting the importance of embedding economic literacy into community values, particularly in understanding what is infinite banking, which has its advocates but also faces criticisms.
As Mark noted, these ‘dangerous twists’ can indeed be concerning but are not truly ‘twists’ to IBC, emphasizing the need for a balanced understanding of the concept. Critics often point out that the cash value growth rate may not align with the expectations set by proponents, which can lead to disillusionment among new adopters. As the concept of what is infinite banking continues to develop, it remains an essential tool for those looking to navigate the intricacies of wealth management and economic independence, aligning with Bright Advisers’ mission to help families understand what is infinite banking and make informed decisions with their wealth to preserve it for future generations.
Explore Key Components: How Infinite Banking Works
Infinite financing is built on several essential elements that work together to create a robust financial strategy:
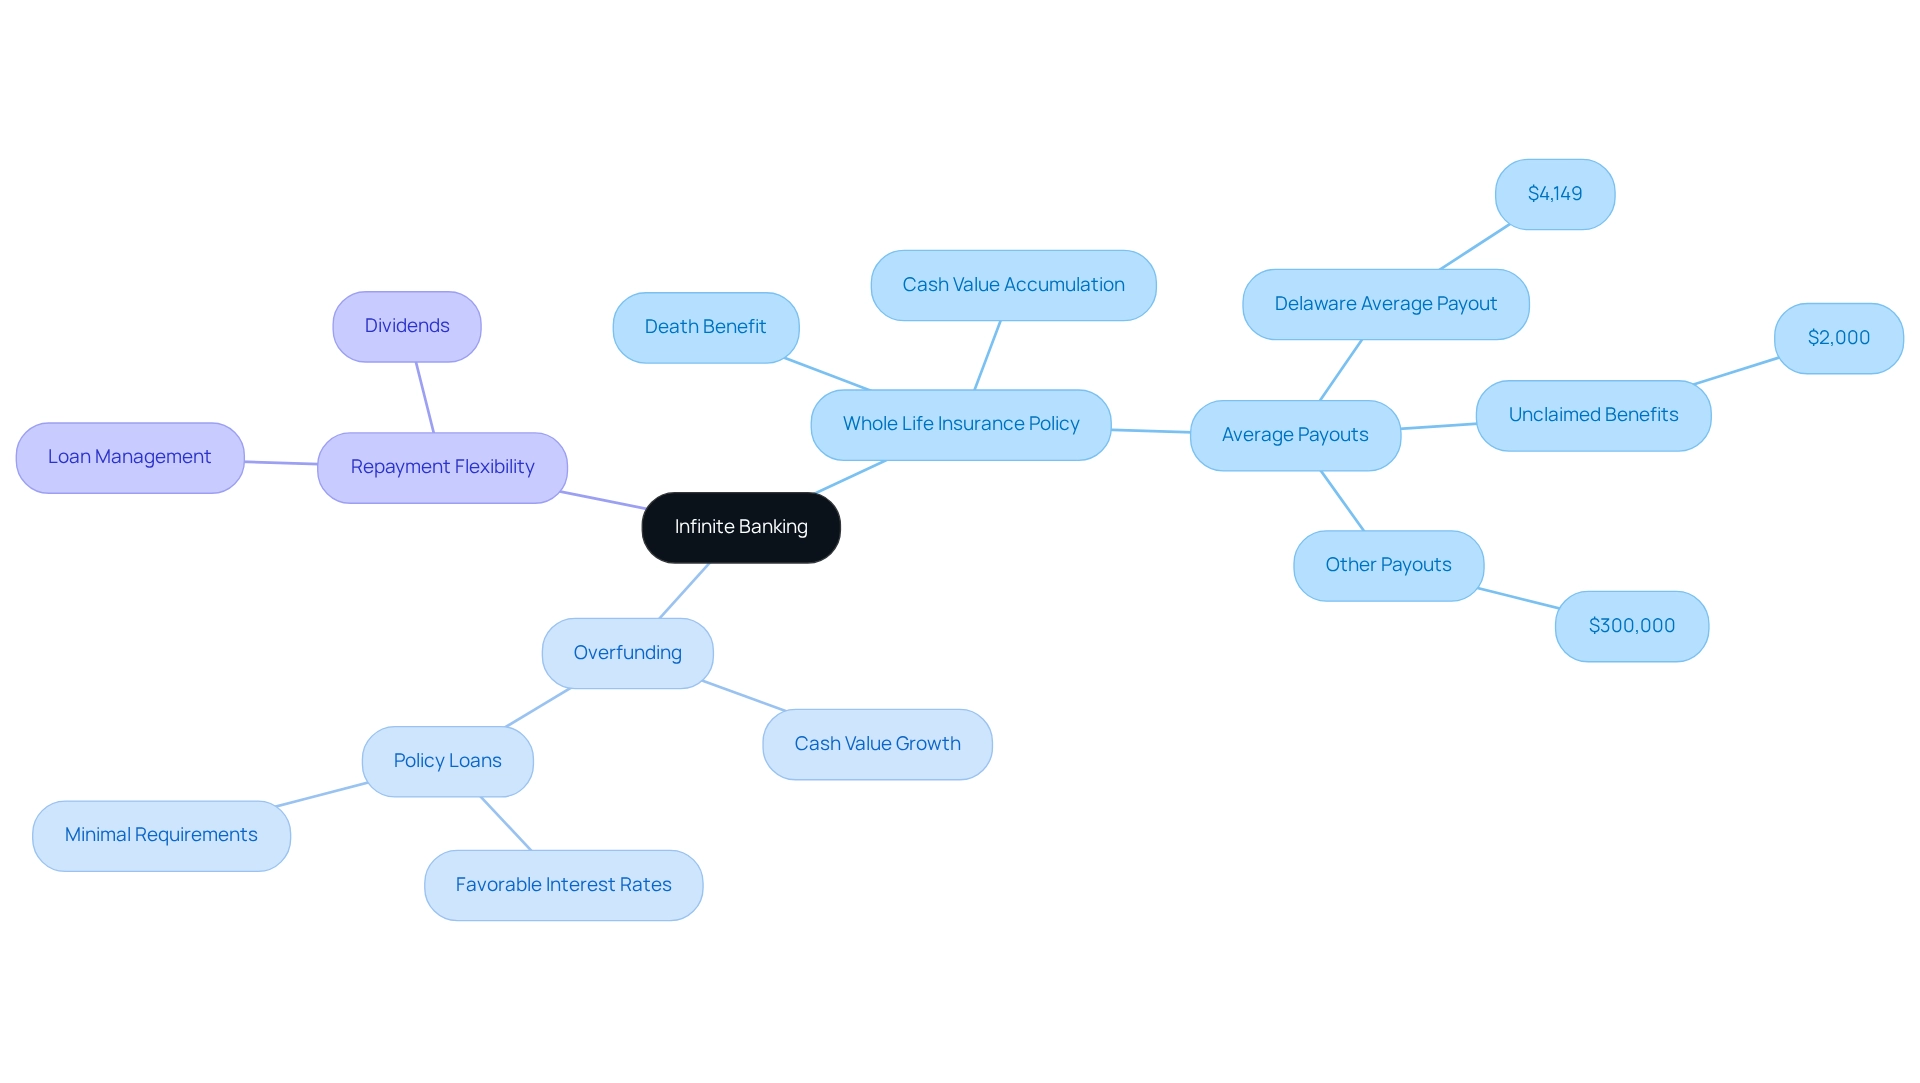
- At the heart of infinite banking lies what is infinite banking, which is a specially designed whole life insurance policy. This policy not only provides a death benefit but also accumulates cash value over time, serving as a financial resource for policyholders. Tori Addison, Principal Researcher, notes that Delaware boasts the highest average life insurance payout per active policy, averaging $4,149. This highlights the potential benefits of such policies. Bright Advisers emphasizes the importance of low fund fees, making these policies more accessible for families striving to enhance their financial security.
- Overfunding: To fully leverage the benefits of their policies, many individuals opt to overfund them. This practice accelerates the growth of cash value, creating greater opportunities for borrowing against it later. By partnering with Bright Advisers, families can tailor their wealth management strategies to bolster their understanding of what is infinite banking, ensuring they meet both short-term and long-term goals. One of the most attractive features of infinite banking is the ability to take out policy loans against the policy’s value. These loans typically offer favorable interest rates and do not impose the stringent requirements associated with traditional loans, making them accessible for many families. The average unclaimed life insurance benefit stands at $2,000, while other payouts can reach up to $300,000, showcasing the financial potential these policies offer. Bright Advisers’ commitment to minimal fees further enhances the appeal of these loans for young families.
- Repayment Flexibility: Borrowers enjoy significant freedom in repaying their loans, allowing them to manage their finances effectively. This flexibility ensures that the cash value continues to grow, as the policy generates dividends even while loans are outstanding. This feature is particularly beneficial for families looking to ease financial stress while securing their futures.
Families often face challenges in financial planning, such as juggling immediate expenses with long-term savings goals. The cash value growth rates for whole life insurance policies can vary, but they generally provide a stable return that contributes to long-term financial security. Recent statistics reveal that many families are recognizing the importance of whole life insurance, with a notable increase in policy ownership as they strive to bridge the gap between their coverage and actual financial needs. This trend indicates a narrowing divide between the coverage individuals have and the amount they truly need, reflecting a shift towards improved financial security.
Real-world examples illustrate the effectiveness of overfunding whole life insurance policies. For instance, families who have strategically overfunded their policies have successfully utilized policy loans to cover significant expenses, such as education or home purchases, while still allowing their cash value to grow. This approach not only meets urgent financial needs but also fosters a legacy of responsibility and financial literacy for future generations. Additionally, the move towards online life insurance purchases signals changing consumer behavior, highlighting the necessity for insurance companies to enhance their online presence and adapt to modern preferences.
Evaluate Pros and Cons: Benefits and Risks of Infinite Banking
What is infinite banking? It provides a range of benefits that can significantly enhance financial management for families, particularly for young parents navigating their financial journeys. Let’s explore these advantages together:
- Tax Benefits: Imagine a scenario where policy loans are typically tax-free. The monetary worth accumulates on a tax-deferred basis, allowing families to grow their wealth without immediate tax implications. For instance, after just one year of a $1,000 monthly contribution to a whole life policy, families could access nearly $10,000. This potential for growth is not just theoretical; it mirrors the experiences of clients like Emily and Mark, who, with the guidance of Bright Advisers, refined their strategies to achieve their dreams of economic independence and work-life balance.
- Liquidity: Consider how easy it is to access resources when needed. What is infinite banking? It allows individuals to tap into their value quickly, bypassing the delays often associated with traditional bank approvals. A Calgary physician, for example, utilized his infinite banking policy to secure emergency funds, which provided immediate financial relief and empowered him to invest more confidently in other opportunities. Similarly, Emily and Mark found that the liquidity afforded by their financial planning empowered them to make informed decisions about their careers and investments.
- Control: It’s essential to feel in control of your financial resources. Policyholders experience improved control over their assets, facilitating effective management and strategic planning. Many clients in their 30s and 40s express excitement about witnessing a consistent rise in their policy funds while still having access to their money. This sense of empowerment was evident for Emily and Mark, who crafted a comprehensive plan with Bright Advisers that included strategies for debt reduction and liquidity management, aligning perfectly with their personal and financial aspirations.
However, it’s important to consider the potential risks:
- High Premiums: Whole life insurance policies often come with substantial premiums, requiring a significant upfront investment that may not be feasible for every family.
- Slow Accumulation Growth: The growth of funds can be gradual, which might discourage those in search of immediate liquidity solutions. The statistic regarding the average cash value accessible after one year underscores this gradual accumulation.
- Complexity: The intricacies of infinite banking necessitate a comprehensive understanding for effective implementation, which can feel overwhelming for some individuals. Utilizing a questionnaire can guide clients toward wiser financial choices, helping to navigate this complexity.
As we look ahead to 2025, more families are exploring innovative financial strategies. It’s vital to carefully weigh the advantages and disadvantages of infinite banking. While it can be a powerful tool for wealth management—especially for young families like Emily and Mark striving to build a secure financial future—approaching it with a clear understanding of both its potential and its pitfalls is crucial. Remember, we’re here for you, ready to support you on this journey together.
Conclusion
The exploration of infinite banking unveils a transformative financial strategy that empowers individuals to take charge of their wealth management. Imagine creating a personal banking system using the cash value of whole life insurance policies. This approach not only provides liquidity but also nurtures long-term financial growth for families. The benefits—such as tax-free loans and enhanced control over finances—underscore how this strategy can reshape traditional financial practices, especially for young families striving for financial independence.
Since its introduction by R. Nelson Nash, the concept of infinite banking has evolved and gained traction among those seeking innovative alternatives to conventional banking. It’s important to understand that financial education and stewardship play a crucial role in navigating the complexities of wealth management. Real-life success stories, like that of Emily and Mark, illustrate the tangible advantages of infinite banking, showcasing how families can achieve their financial goals while securing their legacies.
However, as you consider this strategy, it’s essential to maintain a balanced perspective. While infinite banking offers compelling benefits, such as liquidity and tax advantages, it also requires a significant commitment in terms of premiums and understanding its complexities. As interest in alternative financial strategies continues to grow, we encourage families to assess their unique situations and seek professional guidance. Together, we can unlock the full potential of infinite banking for your financial future, ensuring that you feel supported every step of the way.
Frequently Asked Questions
What is infinite banking?
Infinite banking is a monetary strategy that allows individuals to use the liquidity of permanent life insurance policies, particularly whole life insurance, to create a personal banking system tailored to their needs. It enables policyholders to borrow against their policy’s monetary worth, effectively allowing them to act as their own banker.
How does infinite banking work?
By funding a whole life insurance policy generously, individuals can access liquidity for various financial needs while allowing their liquid assets to grow. This approach emphasizes financial control and provides a means to manage cash flow independently of traditional financial institutions.
Why are people turning to whole life insurance for cash value accumulation?
Many individuals are increasingly seeking financial autonomy, especially in the context of rising credit card annual percentage rates (APRs) that can exceed 20% to 30%. Strategies like infinite banking are being explored to reduce debt, build wealth, and plan for future legacies.
Can you provide an example of how infinite banking benefits families?
Emily and Mark, a young couple, worked with financial consultants to create a strategy using whole life insurance for cash value growth. This approach protected their invested premiums and offered flexibility to manage their finances, helping them meet their children’s educational needs while preparing for retirement.
What are some key benefits of infinite banking?
Key benefits include tax-free growth, access to low-cost loans, and the ability to accumulate wealth without relying on conventional financial products. This method can significantly enhance a family’s economic resilience.
How can individuals get support in implementing an infinite banking strategy?
Individuals can seek assistance from financial consultants who can help navigate the journey toward financial security, ensuring that families’ needs are met with compassion and understanding while creating a brighter financial future.
List of Sources
- Define Infinite Banking: Understanding the Concept
- Infinite Banking with IUL: A Step-by-Step Guide to Becoming Your Own Banker | Capital for Life (https://capitalforlife.com/blog/iul-infinite-banking)
- Is Infinite Banking A Smart Financial Strategy? | Canadian LIC (https://canadianlic.com/blog/is-infinite-banking-a-smart-financial-strategy)
- Infinite Banking Concept: Everything You Need to Know (https://livingwealth.com/infinite-banking)
- What is Infinite Banking? (https://johnstevenson.com/infinite-banking)
- Trace the Origins: History and Evolution of Infinite Banking
- Infinite Banking Wiki: Concepts, Strategies & History Explained – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/infinite-banking-wiki)
- Nelson Nash: Pioneer of the Infinite Banking Concept – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/nelson-nash-the-infinite-banking-concept)
- Bank on Yourself – Problems with Infinite Banking Concept | White Coat Investor (https://whitecoatinvestor.com/infinite-banking-bank-on-yourself)
- Explore Key Components: How Infinite Banking Works
- Top Life Insurance Statistics for 2025 (https://marketwatch.com/insurance-services/life-insurance/life-insurance-statistics)
- Life Insurance Facts and Statistics 2025 | Bankrate (https://bankrate.com/insurance/life-insurance/life-insurance-statistics)
- Infinite Banking: Using Life Insurance as a Source of Liquidity – NerdWallet (https://nerdwallet.com/article/insurance/infinite-banking)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Evaluate Pros and Cons: Benefits and Risks of Infinite Banking
- Top 10 Pros and Cons of Infinite Banking – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/pros-and-cons-of-the-infinite-banking-concept)
- Is Infinite Banking A Smart Financial Strategy? | Canadian LIC (https://canadianlic.com/blog/is-infinite-banking-a-smart-financial-strategy)
- Is Whole Life Insurance a Scam or Rip Off? 5 Surprising Benefits for 2025 – I&E | Whole Life & Infinite Banking Strategies (https://insuranceandestates.com/whole-life-insurance-rip-off-scam)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin