

Key Highlights
- Liability Driven Investment (LDI) aligns assets with obligations to ensure cash flows meet future needs, particularly in retirement funding.
- LDI is crucial for defined benefit retirement plans, helping manage risks related to interest rate changes and ensuring resources are available for payouts.
- As of 2025, 27.1% of pension fund assets are priced based on valuations, highlighting increased exposure to valuation risk since the Global Financial Crisis.
- Total unfunded obligations for pension funds amount to $1.13 trillion, emphasising the urgency of effective LDI strategies.
- LDI strategies improve the funded status of retirement plans, as evidenced by a rise from 101.1% to 103.8% in funded ratios despite increasing Pension Benefit Obligations.
- LDI helps stabilise funding and predictability in retirement plans, addressing challenges like funding volatility and liquidity needs.
- The average return for plans with equity allocations below 15% was 7.98% in FY2025, showcasing the importance of fixed income in LDI strategies.
- LDI strategies have evolved to incorporate diverse asset classes and risk management techniques, enhancing their effectiveness for families.
Introduction
Many parents feel overwhelmed when trying to grasp retirement funding, especially while juggling family responsibilities. Imagine having a strategy like Liability Driven Investment (LDI) that helps you align your family’s needs with your future goals. This approach ensures that your pension funds can meet their commitments without adding stress to your life.
So, how can you and your family use LDI to navigate retirement planning with confidence? Together, we can explore this journey and find the best path for your family’s financial well-being.
Define Liability Driven Investment (LDI)
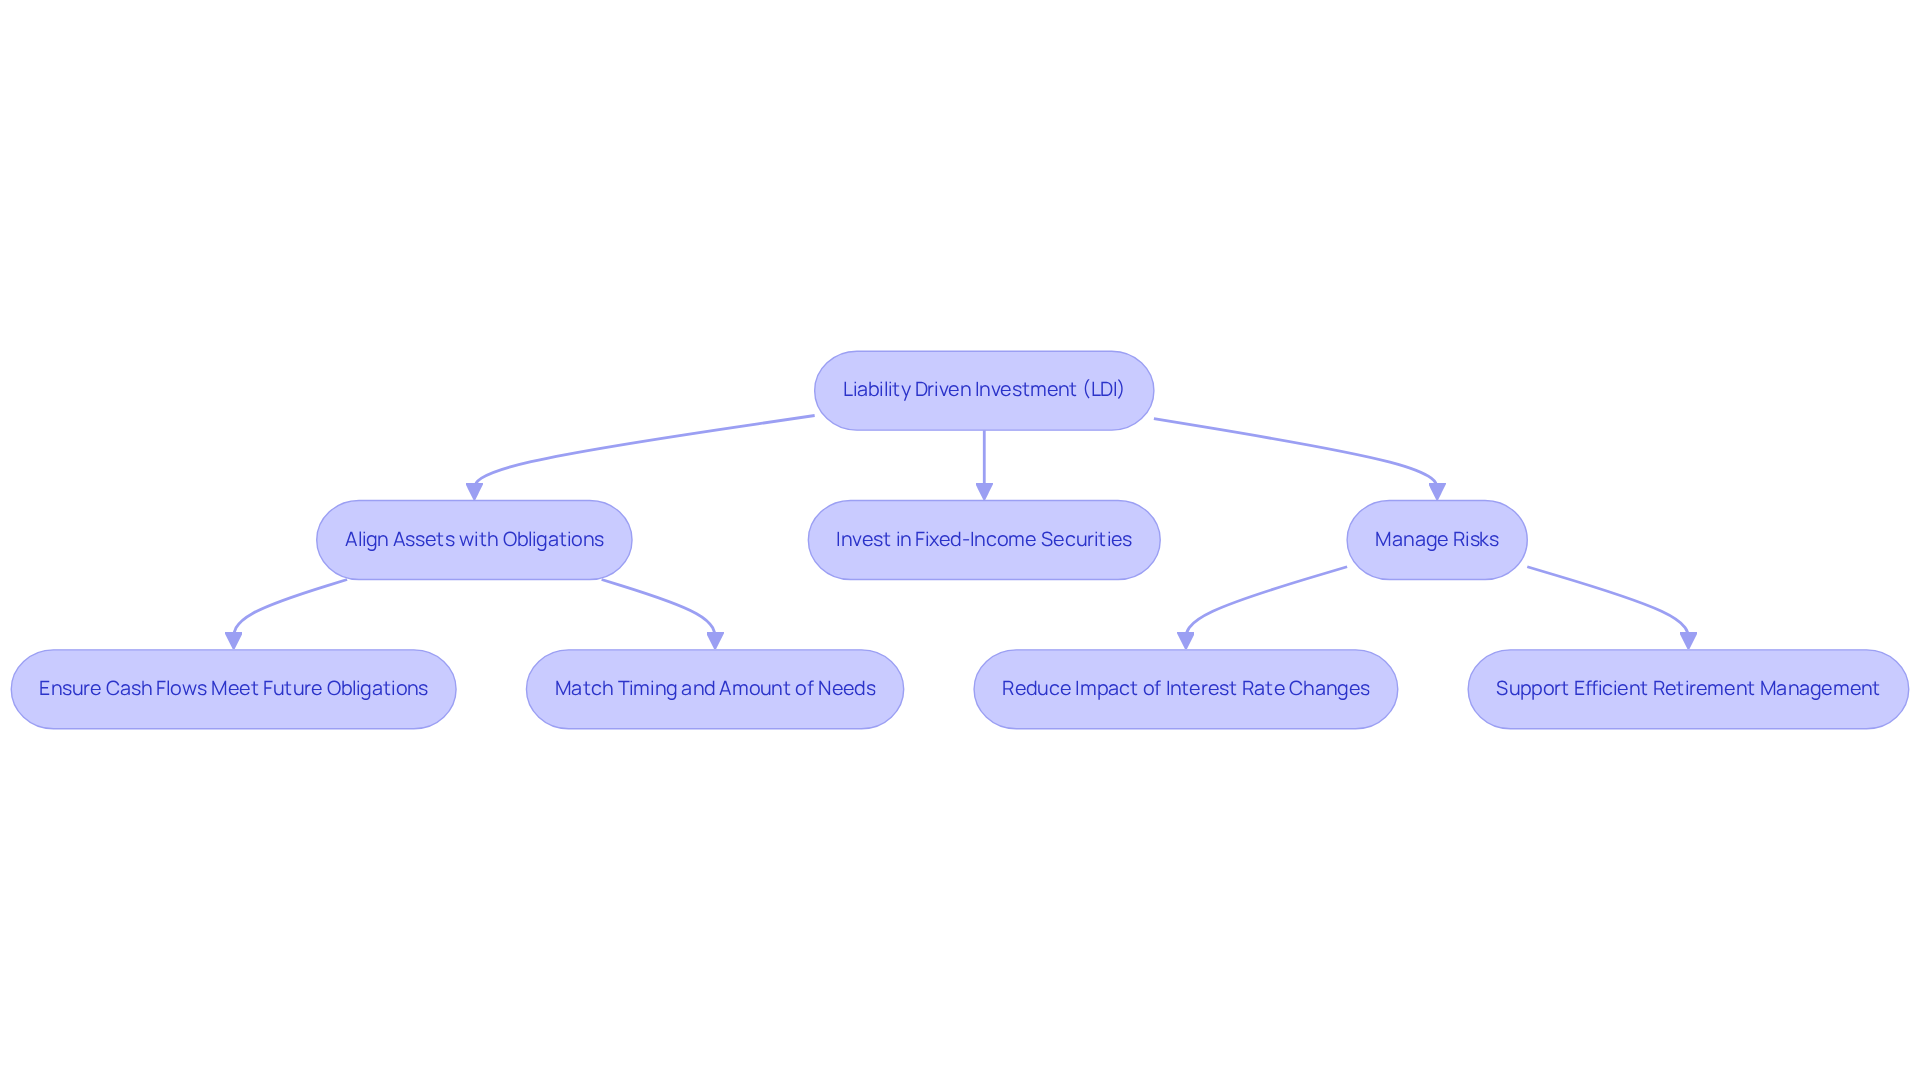
Imagine the peace of mind that comes from knowing your family’s financial future is secure with Liability Driven Investment (LDI), a method that helps align assets with obligations. The essential principle of LDI is to ensure that the cash flows generated from investments are sufficient to meet future obligations, like retirement payouts. This often means investing in fixed-income securities that match the timing and amount of anticipated needs. By focusing on liability driven investment pension funds, retirement plans can effectively manage risks related to interest rate changes, ensuring that necessary resources are available when benefits are due. Liability driven investment pension funds are especially important for defined benefit retirement plans, where ensuring future payouts is a significant concern.
Recent statistics highlight the growing importance of LDI. Did you know that the share of pension fund assets priced based on valuations has increased to 27.1% as of 2025? That’s a significant rise from an average of 9.0% between 2001 and 2007. This shift underscores the heightened exposure to valuation risk, which has tripled since the Global Financial Crisis. Additionally, total unfunded obligations total $1.13 trillion, emphasizing the urgent nature of this matter even as funded ratios improve.
Case studies illustrate the effectiveness of LDI. For instance, despite an increase in Pension Benefit Obligation (PBO) from $1.241 trillion at the end of FY2024 to $1.253 trillion at the end of FY2025, the funded ratio improved from 101.1% to 103.8%. This shows how LDI can help families feel more secure about their financial future. As one expert noted, “A liability-driven investment strategy – matching assets to liabilities – efficiently manages the risk of not meeting those obligations.” Furthermore, LDI strategies assist in managing portfolio risk and reducing the effect of retirement plans on an organization’s financial well-being, making them crucial for efficient retirement management. Understanding LDI can empower you to take control of your family’s financial journey, ensuring you’re ready for the obligations that await.
Identify Problems Addressed by LDI
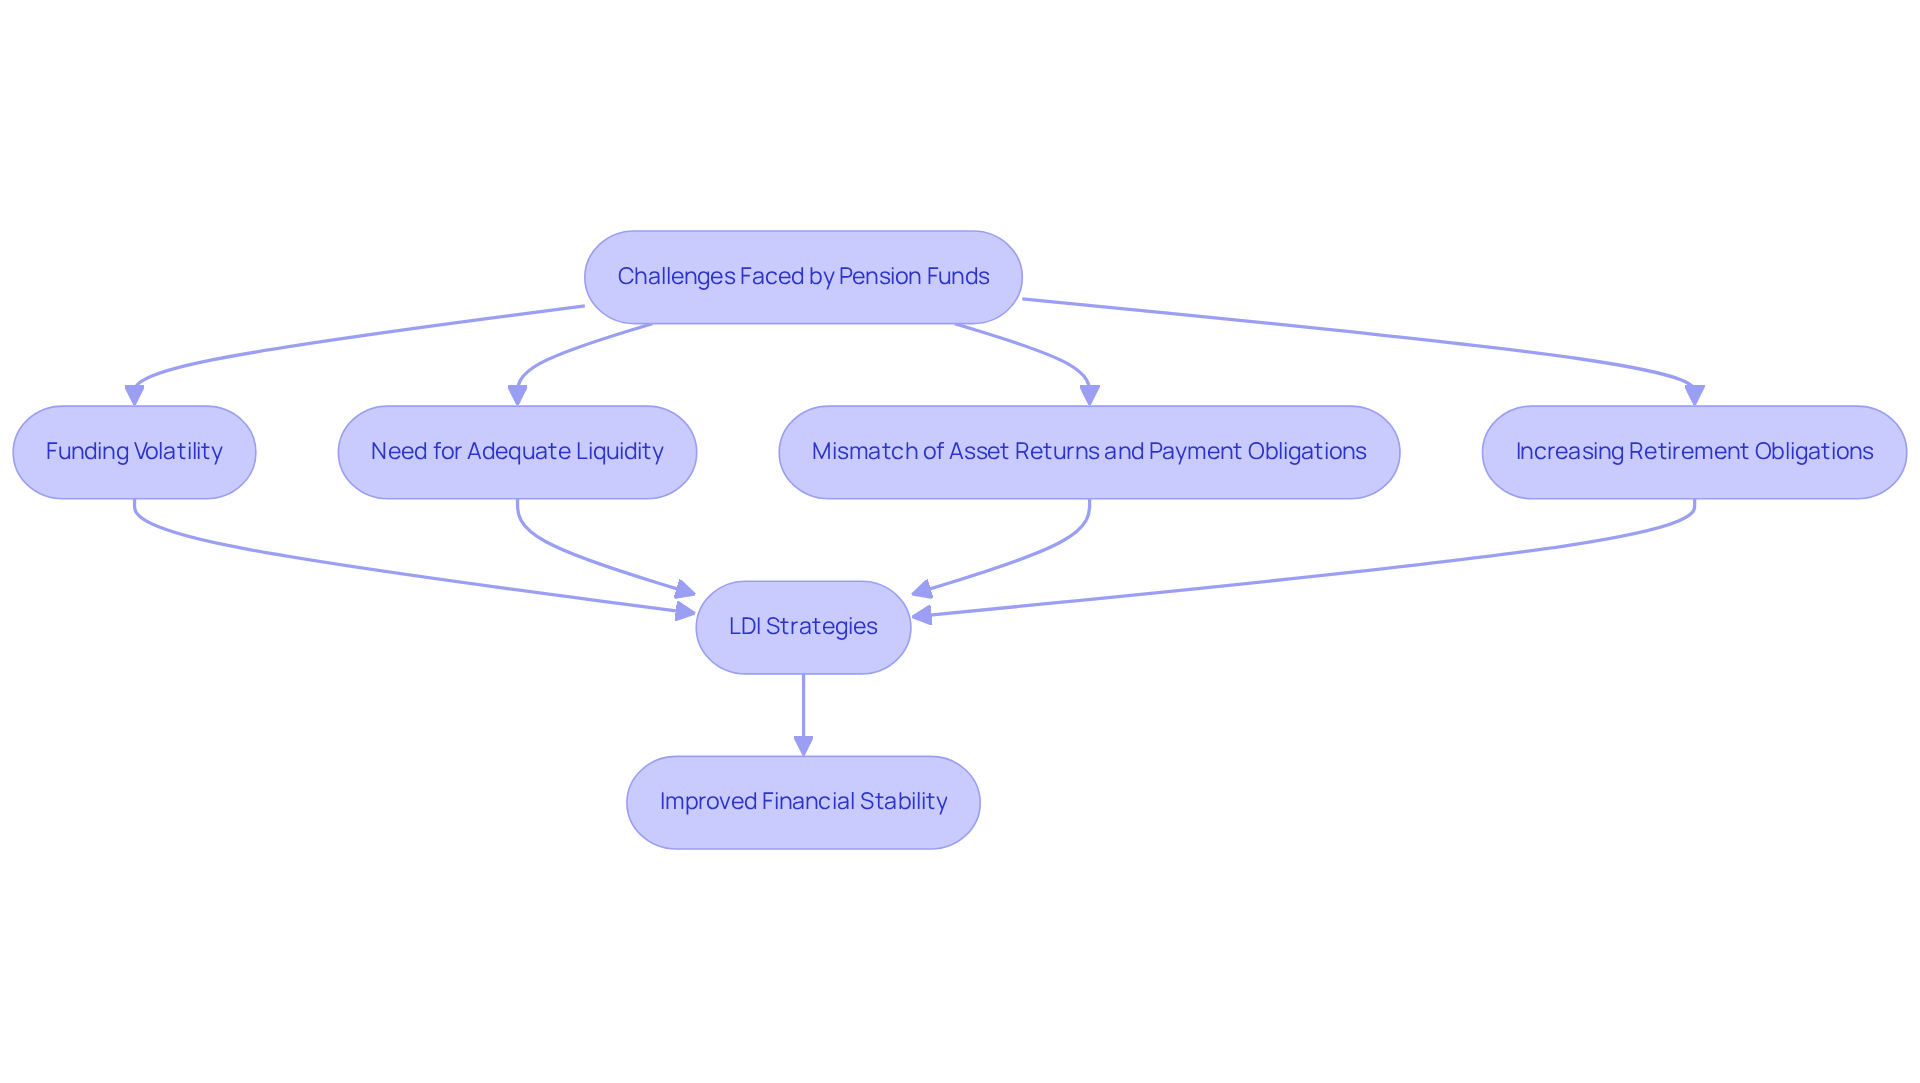
Imagine the worry of planning for your family’s future while facing the complexities of retirement funding. Liability driven investment pension funds implement strategies to tackle several pressing challenges faced by pension funds, including funding volatility and the need for adequate liquidity for future payouts. When interest rates change, it can feel overwhelming to think about how it affects your obligations and savings. A significant issue is the mismatch between the timing of asset returns and the timing of payment obligations. In 2025, many families saw their retirement obligations increase by about 7%, adding to their worries about the future.
LDI strategies help ensure that your investments align with your future needs, giving you peace of mind. This method not only aids in stabilizing funding but also improves predictability in funding needs, enabling retirement funds to plan more effectively for their future obligations. In 2026, the average funded status of retirement plans improved from 81.2% in 2025 to 85%, yet the total unfunded liabilities remained significant at $1.13 trillion. This means many families might face uncertainty in their retirement plans, affecting their peace of mind.
Moreover, the average return for plans with equity allocations below 15% was 7.98% in FY2025, while those with significant fixed income allocations saw returns of about 7%. These statistics demonstrate the significance of liability driven investment pension funds in managing the complexities of funding and ensuring that obligations can be fulfilled without placing excessive pressure on plan sponsors. By utilizing liability driven investment pension funds strategies, retirement plans can enhance their financial stability and ensure the benefits promised to their members. By understanding and implementing LDI strategies, you can take a proactive step towards securing your family’s financial future.
Explore Benefits of LDI for Pension Funds
Imagine a future where your family’s financial security is not just a hope, but a reality. Let’s explore how liability driven investment pension funds can be a game-changer for your family’s retirement plans.
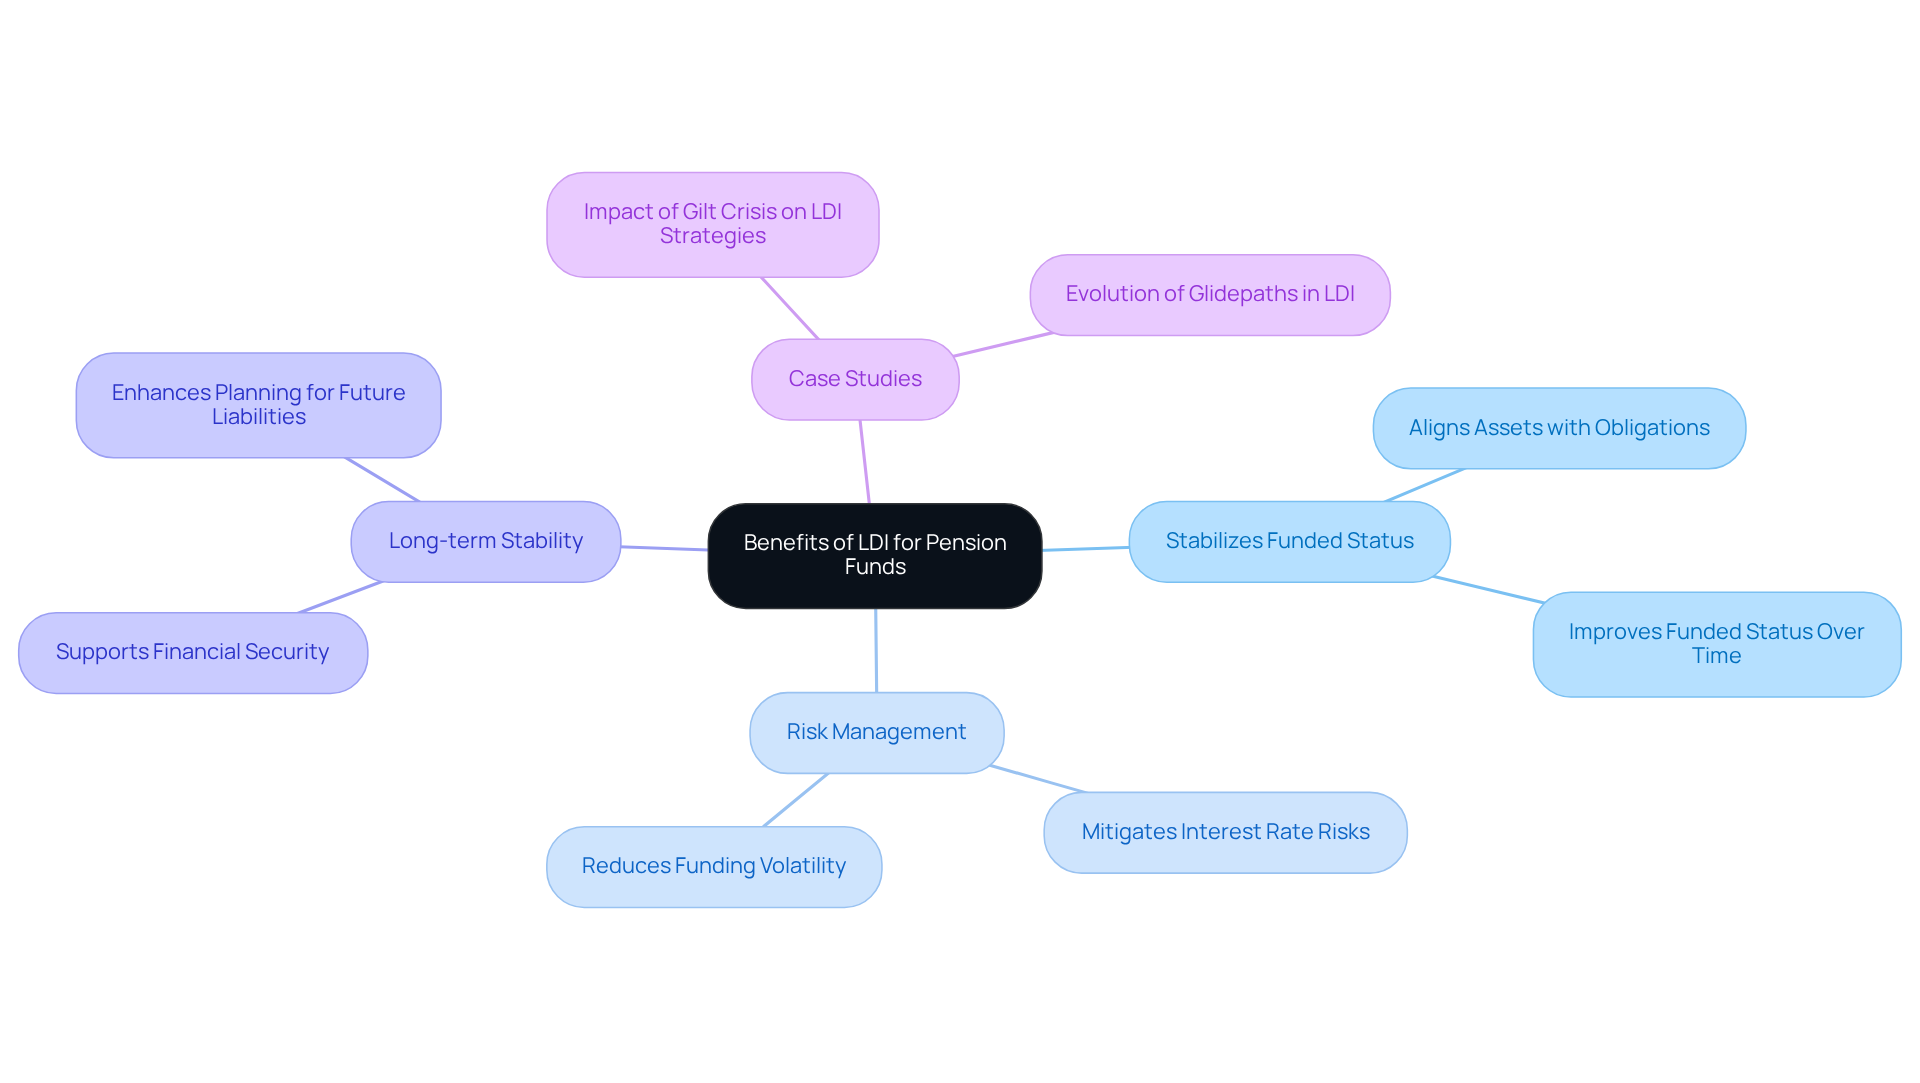
LDI helps stabilize a retirement plan’s funded status by aligning assets with obligations. This means retirement plans can better manage risks related to interest rates, helping you feel more secure about your future. Experts emphasize that having the right resources in place can make all the difference during market ups and downs.
Think of LDI as a guiding hand, encouraging retirement funds to focus on long-term stability for your family’s future. Case studies show that retirement plans integrating LDI strategies earlier have successfully reduced risk as their funded status improves.
With LDI, you can feel confident knowing there’s a solid plan in place to protect your family’s retirement. By aligning investment strategies with current and future liabilities, liability driven investment pension funds support the overall financial stability of retirement funds, ensuring they can meet their obligations to retirees. By embracing LDI strategies, you’re not just planning for retirement; you’re safeguarding your family’s future.
Trace the Evolution of LDI Strategies
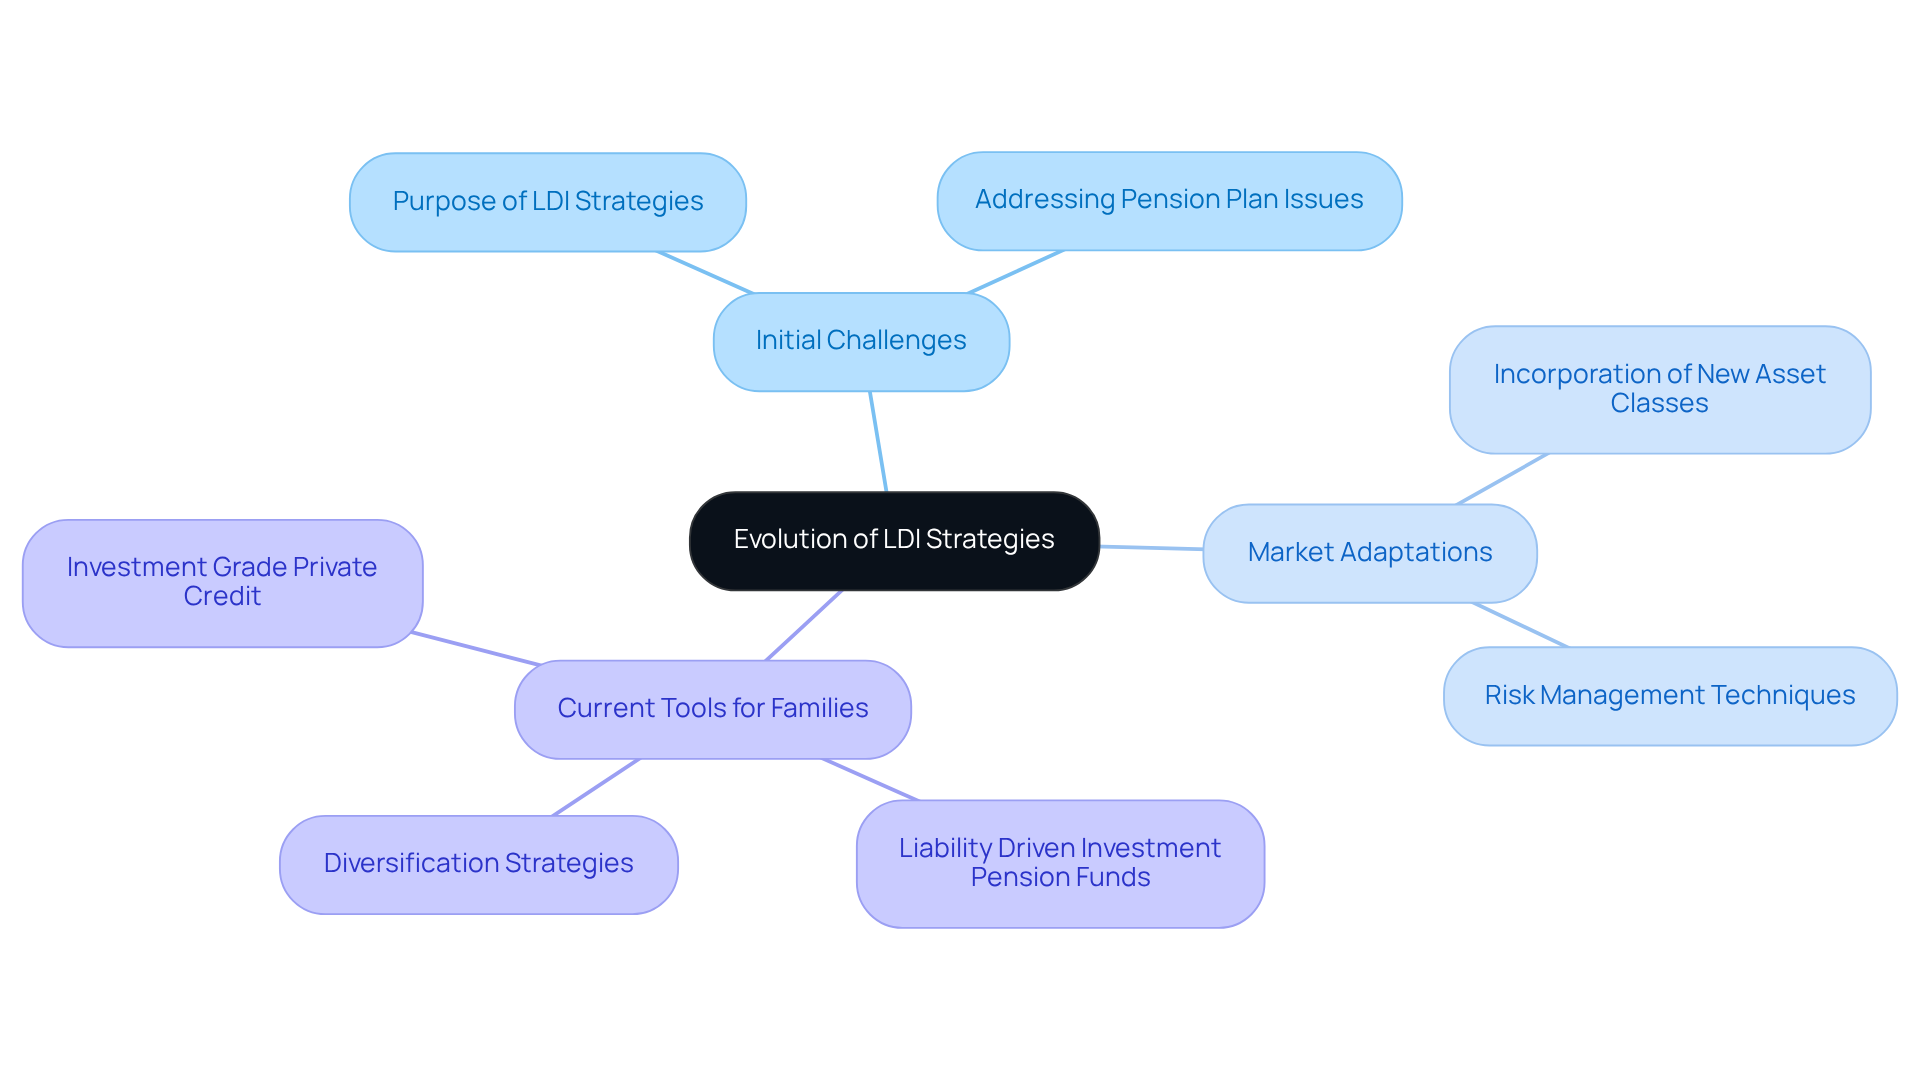
Imagine feeling secure about your family’s financial future, even amidst the complexities of investment strategies such as liability driven investment pension funds. These strategies were initially created to address challenges in pension plans, but they’ve become more sophisticated as liability driven investment pension funds to meet the needs of families like yours.
As market conditions shifted, LDI strategies began to incorporate a wider range of asset classes and risk management techniques. Navigating the complexities of financial strategies can feel daunting, especially when you’re focused on your family’s future. But understanding these evolving strategies can empower you to make informed decisions that protect your family’s future.
Today, families like yours can utilize liability driven investment pension funds, which include a variety of tools that help match financial obligations more effectively, ensuring peace of mind for the future. By grasping these strategies, you can take proactive steps towards securing your family’s financial well-being. Together, we can navigate this journey.
Conclusion
Imagine the worry of not being able to provide for your family’s future; understanding Liability Driven Investment (LDI) can help ease those concerns. LDI helps families align their resources with what they’ll need in the future, making sure retirement payouts are met without added stress. It simplifies the financial journey, making it easier for families to meet their commitments and enjoy peace of mind.
As we’ve explored, LDI is becoming increasingly important for families wanting to secure their financial future. With rising pension fund needs and obligations, LDI strategies are essential for families to feel secure about their future. In today’s world, embracing LDI can be a powerful way for families to protect their financial future.
Taking the first step towards understanding LDI can empower your family to build a secure financial future together.
Frequently Asked Questions
What is Liability Driven Investment (LDI)?
Liability Driven Investment (LDI) is a strategy that aligns assets with financial obligations, ensuring that the cash flows generated from investments are sufficient to meet future obligations, such as retirement payouts.
How does LDI work?
LDI typically involves investing in fixed-income securities that match the timing and amount of anticipated needs, helping to manage risks related to interest rate changes and ensuring necessary resources are available when benefits are due.
Why is LDI important for pension funds?
LDI is particularly important for defined benefit retirement plans, as it helps ensure that future payouts are met, thereby managing the financial risks associated with these obligations.
What recent statistics highlight the importance of LDI?
As of 2025, the share of pension fund assets priced based on valuations has increased to 27.1%, up from an average of 9.0% between 2001 and 2007. Additionally, total unfunded obligations amount to $1.13 trillion, indicating the urgent need for effective LDI strategies.
Can you provide an example of LDI effectiveness?
A case study showed that despite an increase in Pension Benefit Obligation (PBO) from $1.241 trillion at the end of FY2024 to $1.253 trillion at the end of FY2025, the funded ratio improved from 101.1% to 103.8%, demonstrating how LDI can enhance financial security.
How does LDI help manage portfolio risk?
LDI strategies assist in managing portfolio risk and reducing the impact of retirement plans on an organization’s financial well-being, making them essential for effective retirement management.
How can understanding LDI benefit families?
Understanding LDI can help families take control of their financial future by ensuring they are prepared for the obligations that lie ahead, ultimately providing peace of mind regarding their financial security.
List of Sources
- Define Liability Driven Investment (LDI)
- State of Pensions 2026 (https://equable.org/report/state-of-pensions-2026)
- What is Liability Driven Investment & LDI Pensions? (https://xpsgroup.com/news-views/insights-briefings/what-liability-driven-investment-and-ldi-pensions)
- 2026 Corporate Pension Funding Study (https://milliman.com/en/insight/2026-corporate-pension-funding-study)
- Liability-Driven Investing (LDI) for Defined Benefit Plans (https://russellinvestments.com/content/ri/us/en/institutional-investor/solutions/investment-programs/defined-benefit/liability-driven-investing.html)
- What is LDI? Foundations of Liability-Driven Investing (https://business.bofa.com/en-us/content/workplace-benefits/what-is-liability-driven-investing-ldi.html)
- Identify Problems Addressed by LDI
- 2026 Corporate Pension Funding Study (https://milliman.com/en/insight/2026-corporate-pension-funding-study)
- State of Pensions 2026 (https://equable.org/report/state-of-pensions-2026)
- Public Pension Funded Levels Improve Amidst Rising Interest Rates – Center for Retirement Research (https://crr.bc.edu/public-pension-funded-levels-improve-amidst-rising-interest-rates)
- From Volatility to Stability: A Macro Hedging Approach for U.S. Pension Systems (https://ortecfinance.com/en/insights/whitepaper-and-report/from-volatility-to-stability)
- Explore Benefits of LDI for Pension Funds
- Liability-Driven Investing (LDI) for Defined Benefit Plans (https://russellinvestments.com/content/ri/us/en/institutional-investor/solutions/investment-programs/defined-benefit/liability-driven-investing.html)
- What is Liability Driven Investment & LDI Pensions? (https://xpsgroup.com/news-views/insights-briefings/what-liability-driven-investment-and-ldi-pensions)
- The future of liability-driven investing (https://russellinvestments.com/content/ri/us/en/insights/russell-research/2025/02/the-future-of-liability-driven-investing.html)
- Trace the Evolution of LDI Strategies
- The Next Wave of LDI Evolution (https://am.landg.us.com/insights/insights-blog/the-next-wave-of-ldi-evolution)
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Five Quotes from Financial History to Guide Trustees (https://rpc.cfainstitute.org/blogs/enterprising-investor/2024/five-quotes-from-financial-history-to-guide-trustees)
- Quotes on Market History • Novel Investor (https://novelinvestor.com/quote-category/market-history)
- Eight Great Investing Quotes (https://southstatebank.com/retirement-plan-services/retirement-insights/eight-great-investing-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading