

Overview
Understanding personal wealth is vital for you and your family. It encompasses the total value of your assets, minus any liabilities, with net worth acting as a key measure of this wealth. Imagine if you could navigate your financial future with confidence, knowing that each step you take brings you closer to economic stability and long-term goals.
Factors like real estate, social safety nets, and tailored financial strategies play crucial roles in this journey. These elements not only secure your family’s future but also provide peace of mind as you work towards shared aspirations. It’s important to understand how these components interact to create a solid foundation for your family’s financial health.
Together, we can explore the best strategies that resonate with your family’s values. By focusing on your unique circumstances, we can develop a plan that supports your dreams and addresses your concerns. Remember, we’re here for you, ready to assist you in navigating this journey toward financial well-being.
Key Highlights:
- Personal wealth is defined as the total value of all assets owned by an individual, minus liabilities.
- Net worth is a key measure of personal wealth, calculated by subtracting total debts from total assets.
- Understanding personal wealth is crucial for economic health and achieving long-term goals.
- Social Security assets represent 20% of household resources, highlighting the importance of safety nets, especially for lower-income families.
- The depletion of Social Security trust funds by 2034 emphasizes the need for families to understand their economic situation.
- Real estate is a significant component of personal wealth, particularly for families with young children.
- Economic stability is supported by personal assets, which serve as a safety net against unexpected expenses.
- Different backgrounds impact wealth accumulation, necessitating customized economic strategies.
- Historical perspectives show that the definition of personal wealth has evolved from land ownership to diversified investments.
- Key characteristics of personal wealth include liquidity, diversification, and growth potential.
- Strategies for building personal wealth involve budgeting, saving, investing, and continuous financial education.
- Families can benefit from tailored asset management solutions to achieve financial security and independence.
Introduction
In a world where financial security is essential, understanding the nuances of personal wealth becomes vital for families. Personal wealth is more than just a number; it represents the total value of an individual’s assets, minus liabilities, and serves as a reflection of their financial health. As we navigate through life, the definition of wealth evolves, encompassing not only cash and property but also the thoughtful management of these resources to ensure long-term stability for our loved ones.
Imagine if you could secure a prosperous future for your children while managing the complexities of today’s financial landscape. In 2025, families face the dual challenge of navigating these intricate paths while aiming to create a lasting legacy. This article delves into the core meaning of personal wealth, its significance in financial planning, and the strategies that empower families to build and preserve their wealth effectively.
Together, we can navigate this journey, ensuring that your family’s financial health is not just a goal, but a reality. We’re here for you, ready to explore the ways in which understanding personal wealth can lead to a brighter future for generations to come.
Defining Personal Wealth: Understanding Its Core Meaning
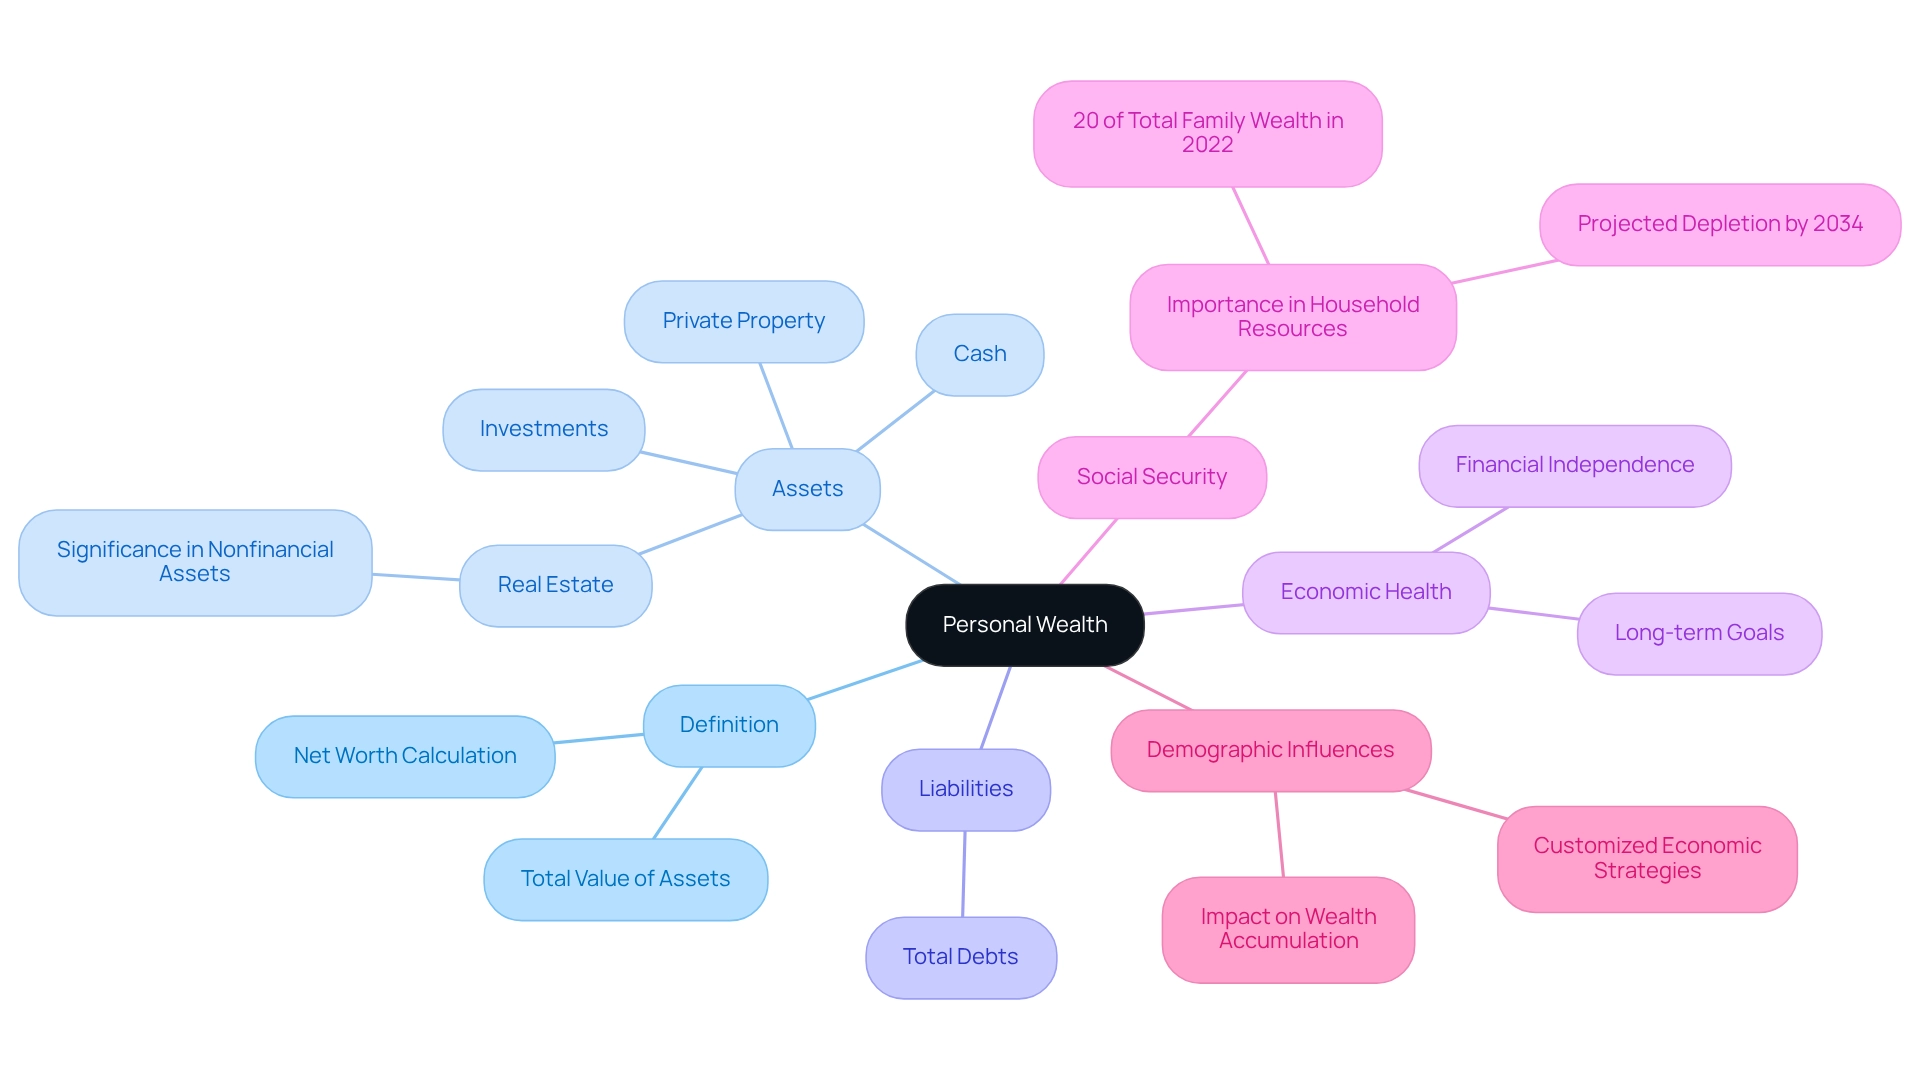
Defining what is personal wealth involves understanding that it encompasses the total value of all assets owned by an individual, minus any liabilities. This includes cash, investments, real estate, and private property. To understand what is personal wealth, it is typically assessed through net worth, which is calculated by subtracting total debts from total assets. Understanding what is personal wealth is crucial; it reflects a person’s economic health and their ability to achieve long-term goals. It goes beyond simple monetary ownership; it embodies what is personal wealth, referring to the resources that provide security and opportunities for future generations.
Imagine a future where individual prosperity is not just about accumulating assets but also about understanding what is personal wealth and managing it wisely to ensure economic independence and stability. In 2022, Social Security assets comprised 20% of overall household resources, underscoring the importance of social safety nets, especially for families with lower incomes. However, forecasts indicate that the total reserves in Social Security trust funds are expected to be depleted by fiscal year 2034. This reality highlights the necessity for families to thoroughly understand their economic situation, particularly in terms of what is personal wealth, as experts affirm that it is vital for achieving economic independence.
Isabel V. Sawhill, a Senior Fellow Emeritus in Economic Studies, notes that real estate forms a significant portion of nonfinancial assets, which helps illustrate what is personal wealth. For households with young children, the average net worth in 2025 reflects the unique challenges and opportunities they face in building a secure economic future. At Bright Advisers, we are dedicated to empowering young families through tailored asset management solutions and personalized planning strategies. By grasping the essential concept of personal assets and leveraging the resources we provide, families can make informed decisions that align with their values and aspirations.
Moreover, discussions on demographic influences on household wealth reveal how different backgrounds can impact wealth accumulation, emphasizing the need for customized economic strategies. By understanding these dynamics, families can navigate their financial journeys more effectively. Together, we can explore how Bright Advisers can assist you in reaching your financial goals. Please feel free to reach out to us at (714) 987-2967 or email hello@brightadvisers.com. We’re here for you.
The Importance of Personal Wealth in Financial Security and Planning
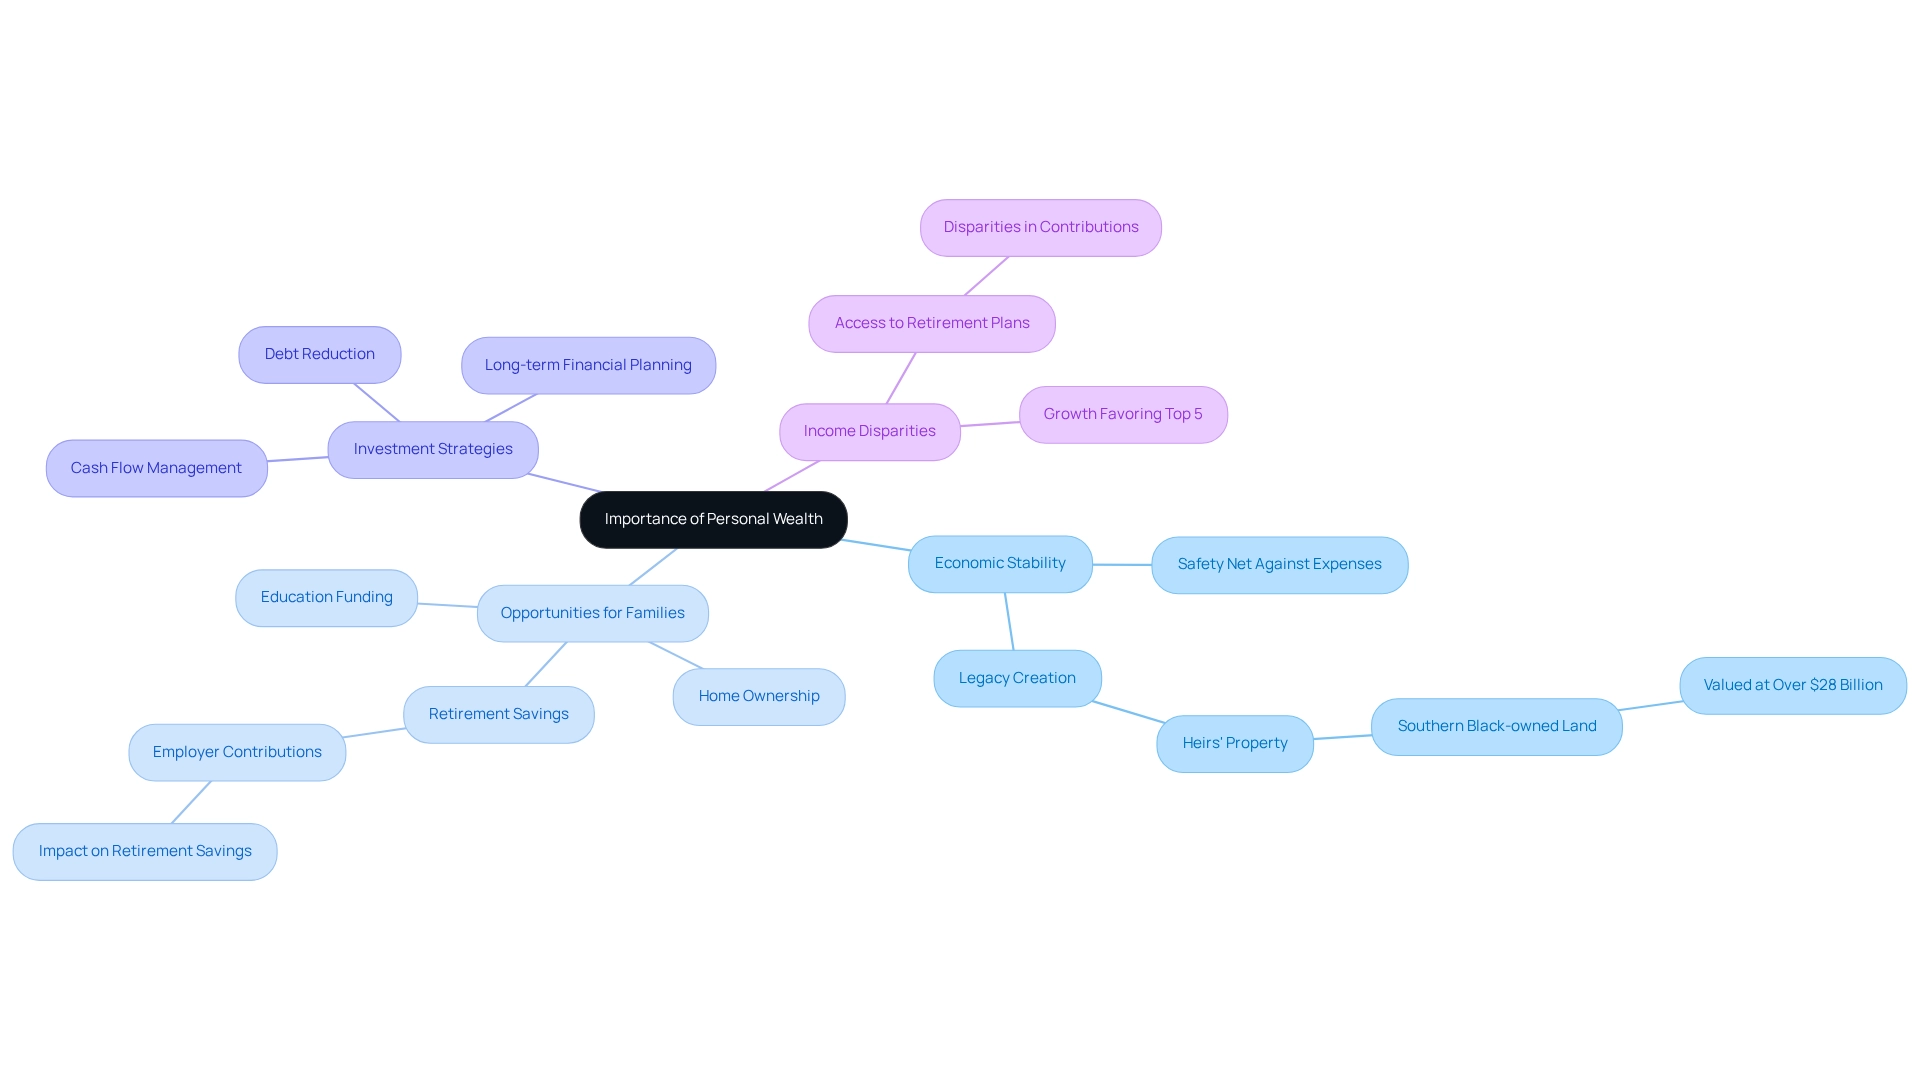
Personal assets are essential for economic stability, acting as a safety net against unexpected expenses and market fluctuations. They empower families to seize opportunities that can enrich their lives—think education, home ownership, and retirement savings. For instance, families with access to private resources can invest in their children’s education, significantly boosting their future earning potential and contributing to overall economic stability.
Imagine a family that owns their home; they often enjoy greater economic security compared to renters. In fact, heirs’ property constitutes over a third of Southern Black-owned land, valued at more than $28 billion. This highlights just how crucial personal assets are for creating a legacy and accumulating resources for future generations, emphasizing what is personal wealth as a foundation for effective financial planning. This knowledge informs budgeting, investment strategies, and risk management. Families who grasp their financial situation are better positioned to make informed choices that align with their long-term aspirations. Take young professionals like Emily and Mark, who partnered with Bright Advisers. They navigated the complexities of financial planning and crafted a strategy that aligned with their goal of achieving financial freedom. By reducing debt, managing cash flow, and investing wisely, they gained the flexibility to choose careers that fit their desired work-life balance.
However, not all households have the same opportunities. Case studies reveal that families without access to employer-sponsored retirement plans miss out on critical contributions that could significantly enhance their savings. This gap underscores the importance of individual resources in ensuring a comfortable retirement. As highlighted in the case study ‘The Role of Employer Contributions,’ households lacking these plans face challenges in boosting their retirement savings. Economic experts consistently emphasize that understanding what is personal wealth not only enhances economic stability but also fosters informed decision-making, paving the way for a successful future. Additionally, while income growth from 2011 to 2018 became more equitable, it still favored households in the top 5%, revealing ongoing income disparity issues. Neil Bennett, a statistician, points out that the Survey of Income and Program Participation provides valuable insights into income dynamics, further underscoring the vital role of individual assets in ensuring financial security.
Together, we can navigate this journey towards financial well-being, ensuring that your family has the resources needed to thrive.
The Evolution of Personal Wealth: Historical Perspectives
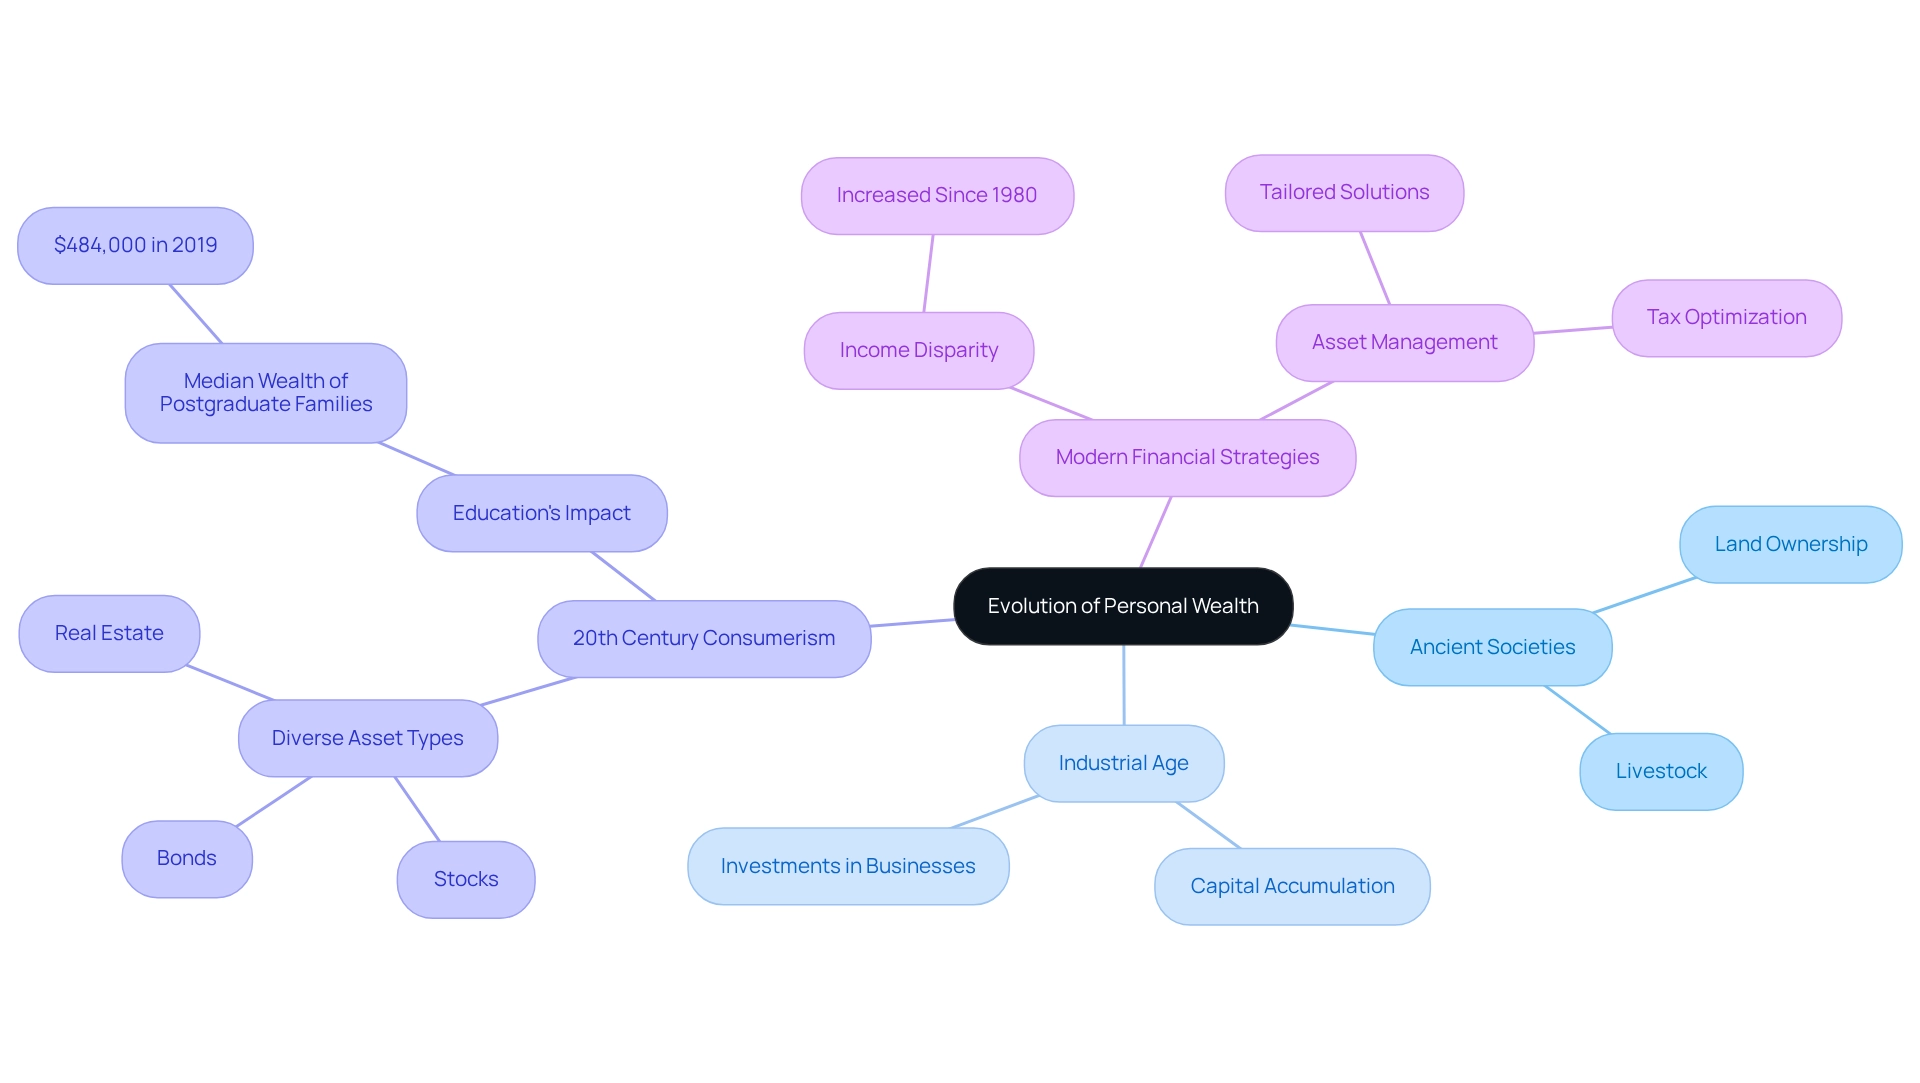
The concept of individual prosperity, or what is personal wealth, has transformed significantly over time, and understanding this evolution can provide valuable insights for families today. In ancient societies, prosperity was largely measured by land ownership and livestock, reflecting the agrarian economies of that era. As we moved into the industrial age, the focus shifted to capital accumulation and investments in businesses, marking a pivotal change in how we perceive and measure prosperity.
Fast forward to the 20th century, an era of consumerism emerged, broadening the definition of personal affluence to encompass a diverse range of assets, including stocks, bonds, and real estate. This shift highlighted the growing importance of economic markets and investment strategies in building wealth. By 2019, households with postgraduate degrees boasted a median net worth of $484,000, showcasing how education can influence economic success and the widening gap in resources within our society. In contrast, households led by individuals aged 65 to 75 had median assets of $269,000, illustrating the disparities in resources across different age groups, and highlighting what is personal wealth as it relates to economic literacy and effective resource management. The rise of technology and innovative financial solutions has added layers of complexity to asset management, making it essential for individuals—especially young families—to navigate these challenges with care. Bright Advisers emphasizes the importance of tailored asset management solutions that empower families to achieve financial security and independence through personalized planning and tax optimization.
Imagine Jay and Emma, hypothetical clients aiming to reduce financial stress. They can benefit from customized retirement strategies and education savings options that align with their family goals. Furthermore, the growing income disparity in the U.S. since 1980 complicates the assessment of household assets and underscores what is personal wealth among certain demographics. Understanding what is personal wealth through the historical trajectory of individual assets not only sheds light on its current state but also emphasizes the necessity of informed financial planning for a successful future. As Bright Advisers advocates, integrating family values and understanding into asset management is crucial for fostering multi-generational prosperity. Christine Browne wisely noted that the complexities of managing resources require a nuanced understanding of both historical and contemporary factors that influence individual finances.
Together, we can navigate this journey toward financial well-being, ensuring that your family’s needs and aspirations are at the forefront of your planning.
Key Characteristics of Personal Wealth: Components and Interactions
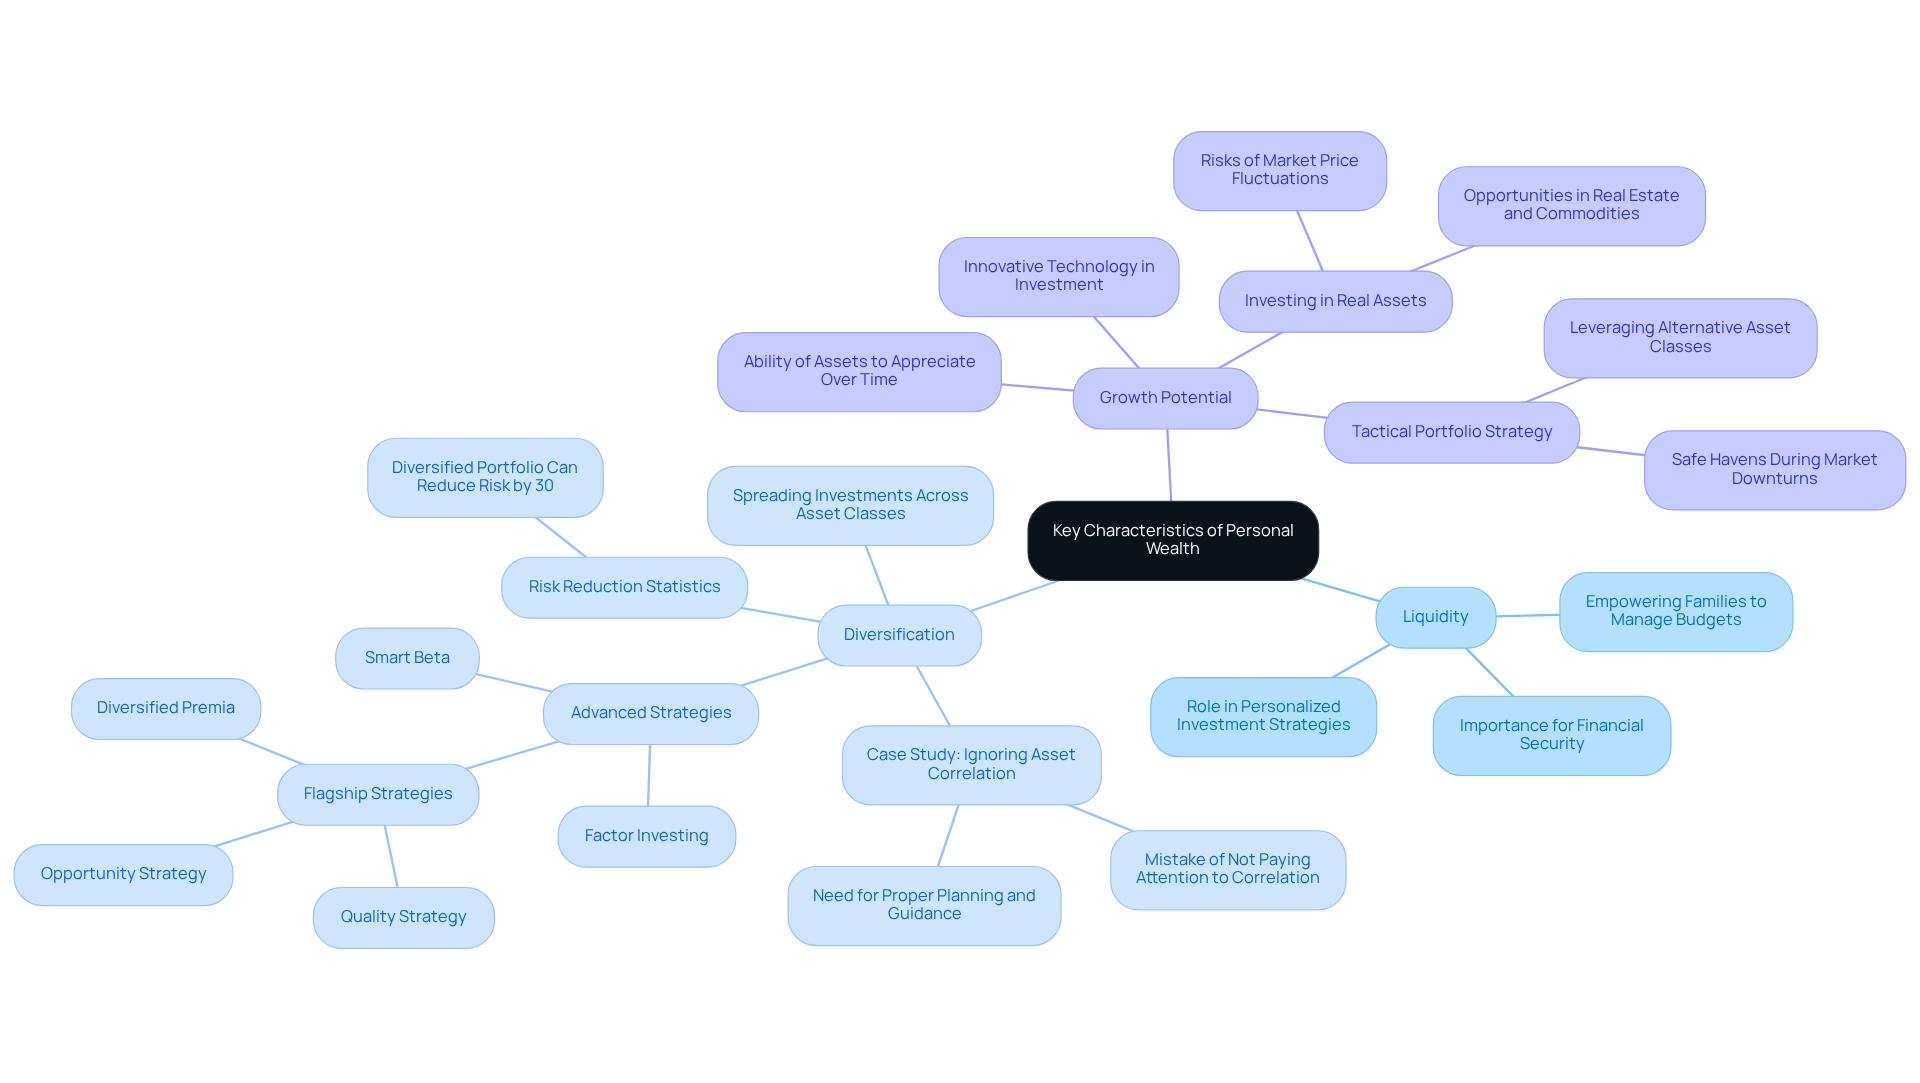
Key traits of individual prosperity include liquidity, diversification, and growth potential—essential elements for families striving to secure their economic futures. Imagine having the peace of mind that comes from knowing your assets can be easily converted into cash when urgent needs arise. Liquidity ensures that households can address immediate financial concerns without jeopardizing their overall wealth. Bright Advisers emphasizes the importance of liquidity in their personalized investment strategies, empowering families to manage their budgets effectively and collaborate with advisors on their financial plans. By moving away from traditional investment products, families can embrace innovative strategies that align with their unique needs.
Diversification is another vital aspect of financial well-being. It involves spreading investments across various asset classes to minimize risk exposure. Consider a well-diversified portfolio as a safety net during market fluctuations, providing stability against economic changes. Bright Advisers utilizes advanced strategies like smart beta and factor investing, including their flagship strategies such as Diversified Premia, Opportunity Strategy, and Quality Strategy. These approaches help construct diversified portfolios that enhance investment efficiency. In fact, statistics show that a diversified portfolio can reduce risk by up to 30%, highlighting the critical role of asset allocation in personal investment strategies.
Growth potential is about the ability of assets to appreciate over time, a crucial factor for long-term wealth accumulation. For instance, investing in real assets like real estate and commodities can present significant growth opportunities, despite the inherent risks of market price fluctuations. Bright Advisers’ innovative technology has rendered conventional investment products less relevant, allowing families to focus on strategies that maximize growth potential while keeping costs down. Their Tactical Portfolio strategy, for example, leverages alternative asset classes that serve as safe havens during market downturns.
A case study titled “Ignoring Asset Correlation in Diversification” illustrates the pitfalls of neglecting the correlation between different asset types, which can lead to inadequate diversification. This serves as a reminder that even a varied portfolio may lack true diversification if the assets are correlated. Proper planning and professional guidance are essential. As business author Jeffrey Gitomer wisely states, “Failure is not about insecurity, it’s about lack of execution.” Understanding these key traits allows families to develop informed financial strategies that enhance what is personal wealth and contribute to their overall economic well-being. By prioritizing liquidity, diversification, and growth potential, families can effectively manage their resources and pave the way for a prosperous future. Together, we can navigate this journey toward financial security.
Strategies for Building and Preserving Personal Wealth
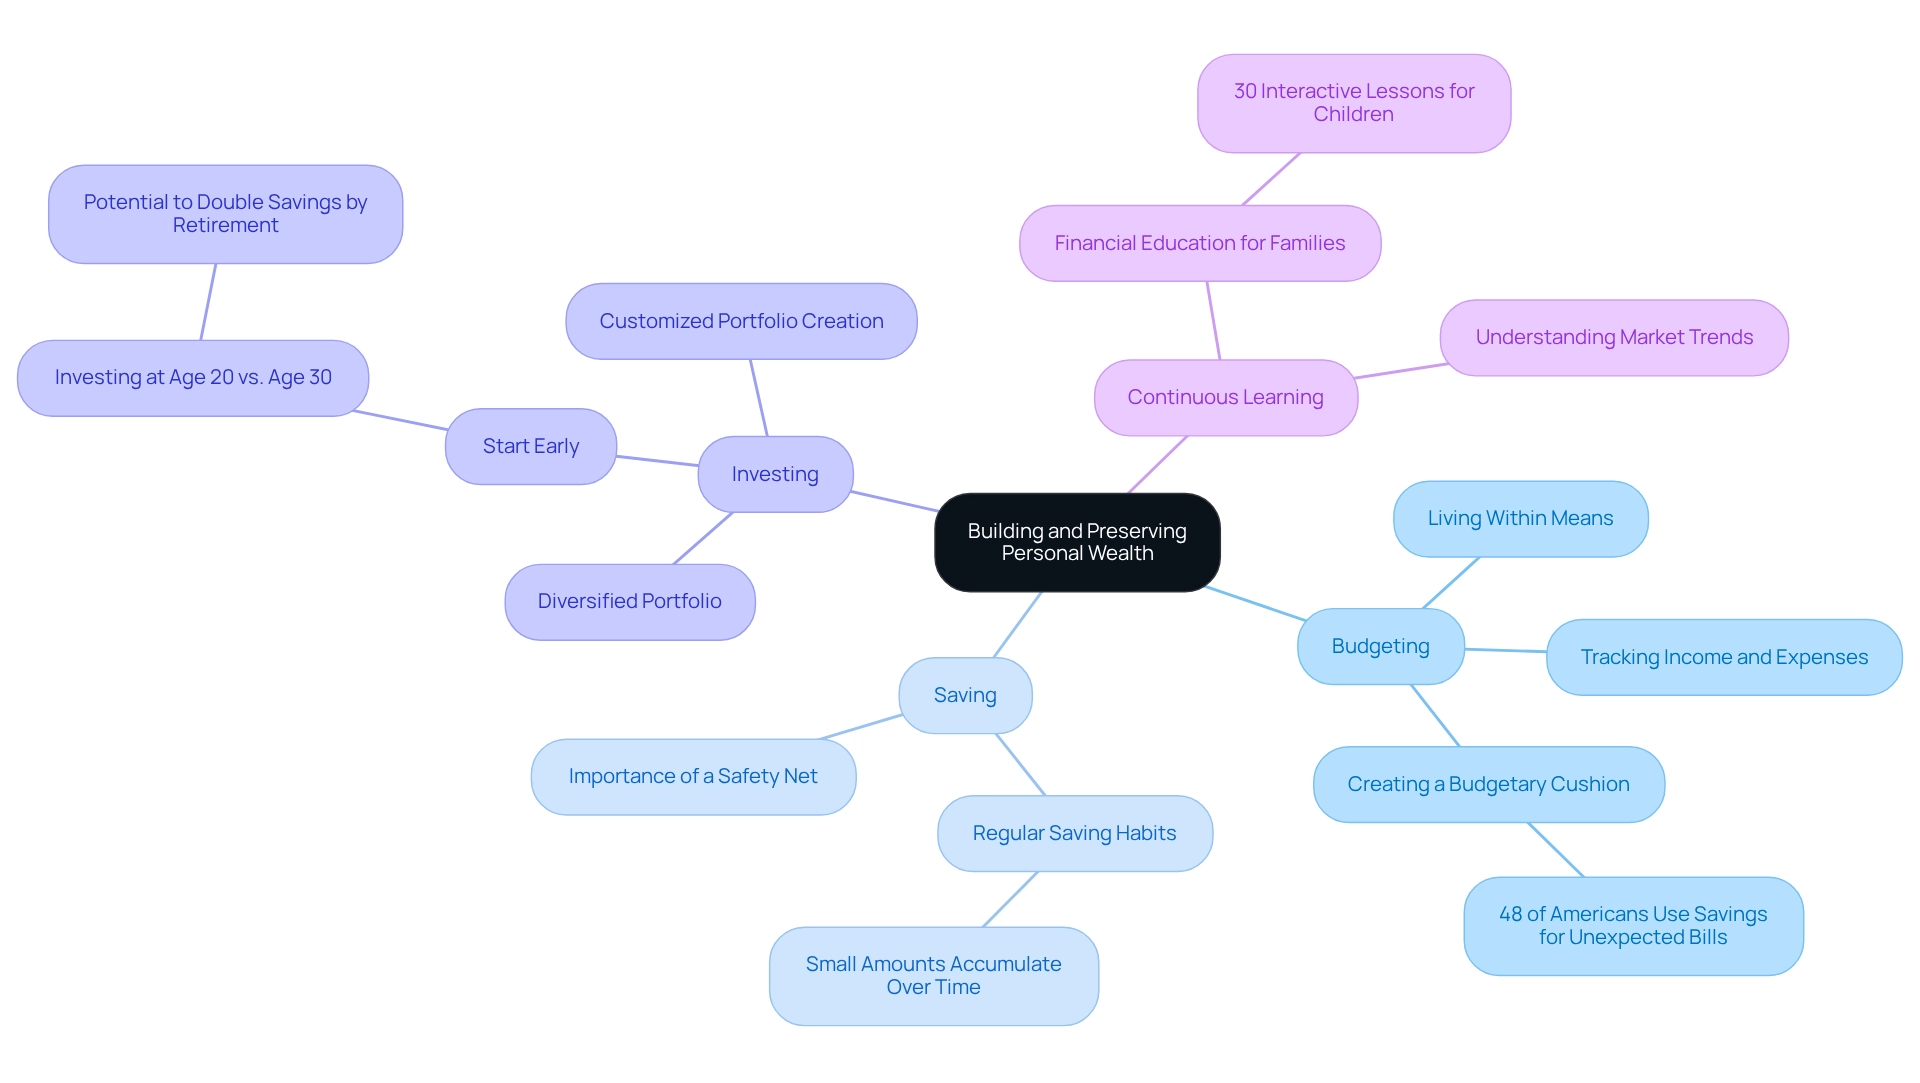
Building and preserving what is personal wealth requires a thoughtful strategy that encompasses budgeting, saving, investing, and continuous learning. Establishing a budget is essential; it helps you keep track of your income and expenses, ensuring you live within your means. Regular saving, even in small amounts, can accumulate significantly over time, creating a vital safety net for those unexpected expenses. Imagine if you could avoid financial stress—almost half of Americans have tapped into their savings for unforeseen costs, underscoring the importance of having that budgetary cushion. At Bright Advisers, we offer personalized planning services tailored specifically for families with young children, helping you prepare for unexpected costs and manage financial surprises with confidence.
Investing in a diversified portfolio is key to fostering wealth growth. Financial advisors suggest starting early; for instance, beginning to invest at age 20 instead of waiting until age 30 can potentially double your savings by retirement. This principle is particularly important for families looking to secure their financial future while prioritizing their children’s needs. Bright Advisers showcases innovative investment strategies grounded in scientific research, empowering families to make informed decisions about their economic futures. Our customized portfolio creation ensures that each investment aligns with your family’s unique financial plan, while our flexible risk management strategies adapt to changes in your financial situation, which ultimately reflects what is personal wealth in understanding market trends and personal finance principles for making informed decisions. Families can greatly benefit from the tailored strategies provided by planners at Bright Advisers, which align with their specific goals and circumstances. We offer 30 on-demand interactive lessons designed to teach children how to manage their own money and make wise financial choices as they grow. Case studies reveal that individuals with higher education levels tend to have significantly greater average savings; for example, college graduates hold an average of $116,010 compared to just $9,130 for those without a high school diploma. Bright Advisers is here to help families enhance their financial knowledge and savings strategies, reinforcing our commitment to promoting multi-generational wealth.
As we look ahead to 2025, the average savings rates for households with young children reflect a growing awareness of the importance of financial planning. By employing effective budgeting and saving techniques, families can lay a strong foundation for asset protection and growth, ensuring a secure financial future for generations to come. Bright Advisers’ comprehensive wealth management services—including tax strategies, risk mitigation, and legacy planning—address the challenges families face in financial planning, making the process easier so you can focus on what truly matters—your loved ones. We invite you to join our waitlist today to discover how we can support your family’s financial journey.
Conclusion
Understanding personal wealth is crucial for families seeking long-term financial stability in today’s complex environment. It’s not just a figure; it represents your financial health through the balance of assets and liabilities. This highlights the need for strategic management. As families face the challenges of 2025, comprehending personal wealth becomes essential for effective financial planning and legacy building.
Personal wealth serves as a cornerstone for your financial security, enabling you to invest in education, home ownership, and retirement. Effective strategies empower families to manage risks and seize opportunities, enhancing their overall quality of life. Tailored wealth management solutions can simplify financial complexities, ensuring that your decisions align with your family values and aspirations.
The evolution of personal wealth underscores the need for adaptability in changing economic landscapes. Here, financial literacy and strategic planning are vital for achieving prosperity. Families are encouraged to focus on liquidity, diversification, and growth potential in their investments to build a resilient financial foundation.
In summary, building and preserving personal wealth through budgeting, saving, investing, and education is essential. By adopting these strategies and seeking professional guidance, families can secure their financial futures and create meaningful legacies. Understanding personal wealth is not merely a target; it is a pathway to financial independence and lasting success for generations to come. Together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is personal wealth?
Personal wealth is defined as the total value of all assets owned by an individual, minus any liabilities. It includes cash, investments, real estate, and private property.
How is personal wealth assessed?
Personal wealth is typically assessed through net worth, which is calculated by subtracting total debts from total assets.
Why is understanding personal wealth important?
Understanding personal wealth is crucial as it reflects a person’s economic health and their ability to achieve long-term goals. It also embodies the resources that provide security and opportunities for future generations.
What role do Social Security assets play in personal wealth?
In 2022, Social Security assets comprised 20% of overall household resources, highlighting the importance of social safety nets for families with lower incomes. However, forecasts indicate that these reserves may be depleted by fiscal year 2034.
How does real estate contribute to personal wealth?
Real estate forms a significant portion of nonfinancial assets, which illustrates personal wealth and helps households build a secure economic future.
What challenges do families with young children face regarding personal wealth?
Households with young children face unique challenges and opportunities in building a secure economic future, which is reflected in their average net worth.
How can families effectively manage their personal wealth?
Families can manage their personal wealth by understanding their financial situation, leveraging resources for informed decision-making, and utilizing tailored asset management solutions.
What impact do demographic influences have on household wealth?
Different backgrounds can impact wealth accumulation, emphasizing the need for customized economic strategies to navigate financial journeys effectively.
What are some examples of how personal assets contribute to economic stability?
Personal assets serve as a safety net against unexpected expenses and market fluctuations, empowering families to invest in education, home ownership, and retirement savings.
What disparities exist in access to retirement resources?
Families without access to employer-sponsored retirement plans miss out on critical contributions that could significantly enhance their savings, highlighting ongoing income disparity issues.
List of Sources
- Defining Personal Wealth: Understanding Its Core Meaning
- Trends in the Distribution of Family Wealth, 1989 to 2022 (https://cbo.gov/publication/60807)
- Six facts about wealth in the United States (https://brookings.edu/articles/six-facts-about-wealth-in-the-united-states)
- The Importance of Personal Wealth in Financial Security and Planning
- Nine Charts about Wealth Inequality in America (https://apps.urban.org/features/wealth-inequality-charts)
-
- Trends in income and wealth inequality (https://pewresearch.org/social-trends/2020/01/09/trends-in-income-and-wealth-inequality)
- Disparities in Wealth by Race and Ethnicity in the 2019 Survey of Consumer Finances (https://federalreserve.gov/econres/notes/feds-notes/disparities-in-wealth-by-race-and-ethnicity-in-the-2019-survey-of-consumer-finances-20200928.html)
- Households With a White, Non-Hispanic Householder Were Ten Times Wealthier Than Those With a Black Householder in 2021 (https://census.gov/library/stories/2024/04/wealth-by-race.html)
- The Evolution of Personal Wealth: Historical Perspectives
- Wealth Inequality in America over Time: Key Statistics (https://stlouisfed.org/open-vault/2020/december/has-wealth-inequality-changed-over-time-key-statistics)
-
- Trends in income and wealth inequality (https://pewresearch.org/social-trends/2020/01/09/trends-in-income-and-wealth-inequality)
- Trends in the Distribution of Family Wealth, 1989 to 2022 (https://cbo.gov/publication/60807)
- Key Characteristics of Personal Wealth: Components and Interactions
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- What Is a Diversified Portfolio? | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/what-is-a-diversified-portfolio.html)
- 100+ Entrepreneur Quotes | American Express (https://americanexpress.com/en-us/business/blueprint/resource-center/start/100-quotes-from-successful-entrepreneurs)
- Strategies for Building and Preserving Personal Wealth
- Average American Savings in 2025: How Your Savings Compare (https://marketwatch.com/financial-guides/banking/average-american-savings)
- The Average Savings Account Balance In The U.S. | Bankrate (https://bankrate.com/banking/savings/savings-account-average-balance)
- What’s the Average Savings Account Balance? Insights & Trends (https://businessinsider.com/personal-finance/banking/average-american-savings)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Family Governance for high-income W-2 families at Bright Advisers.
Keep reading