

Key Highlights
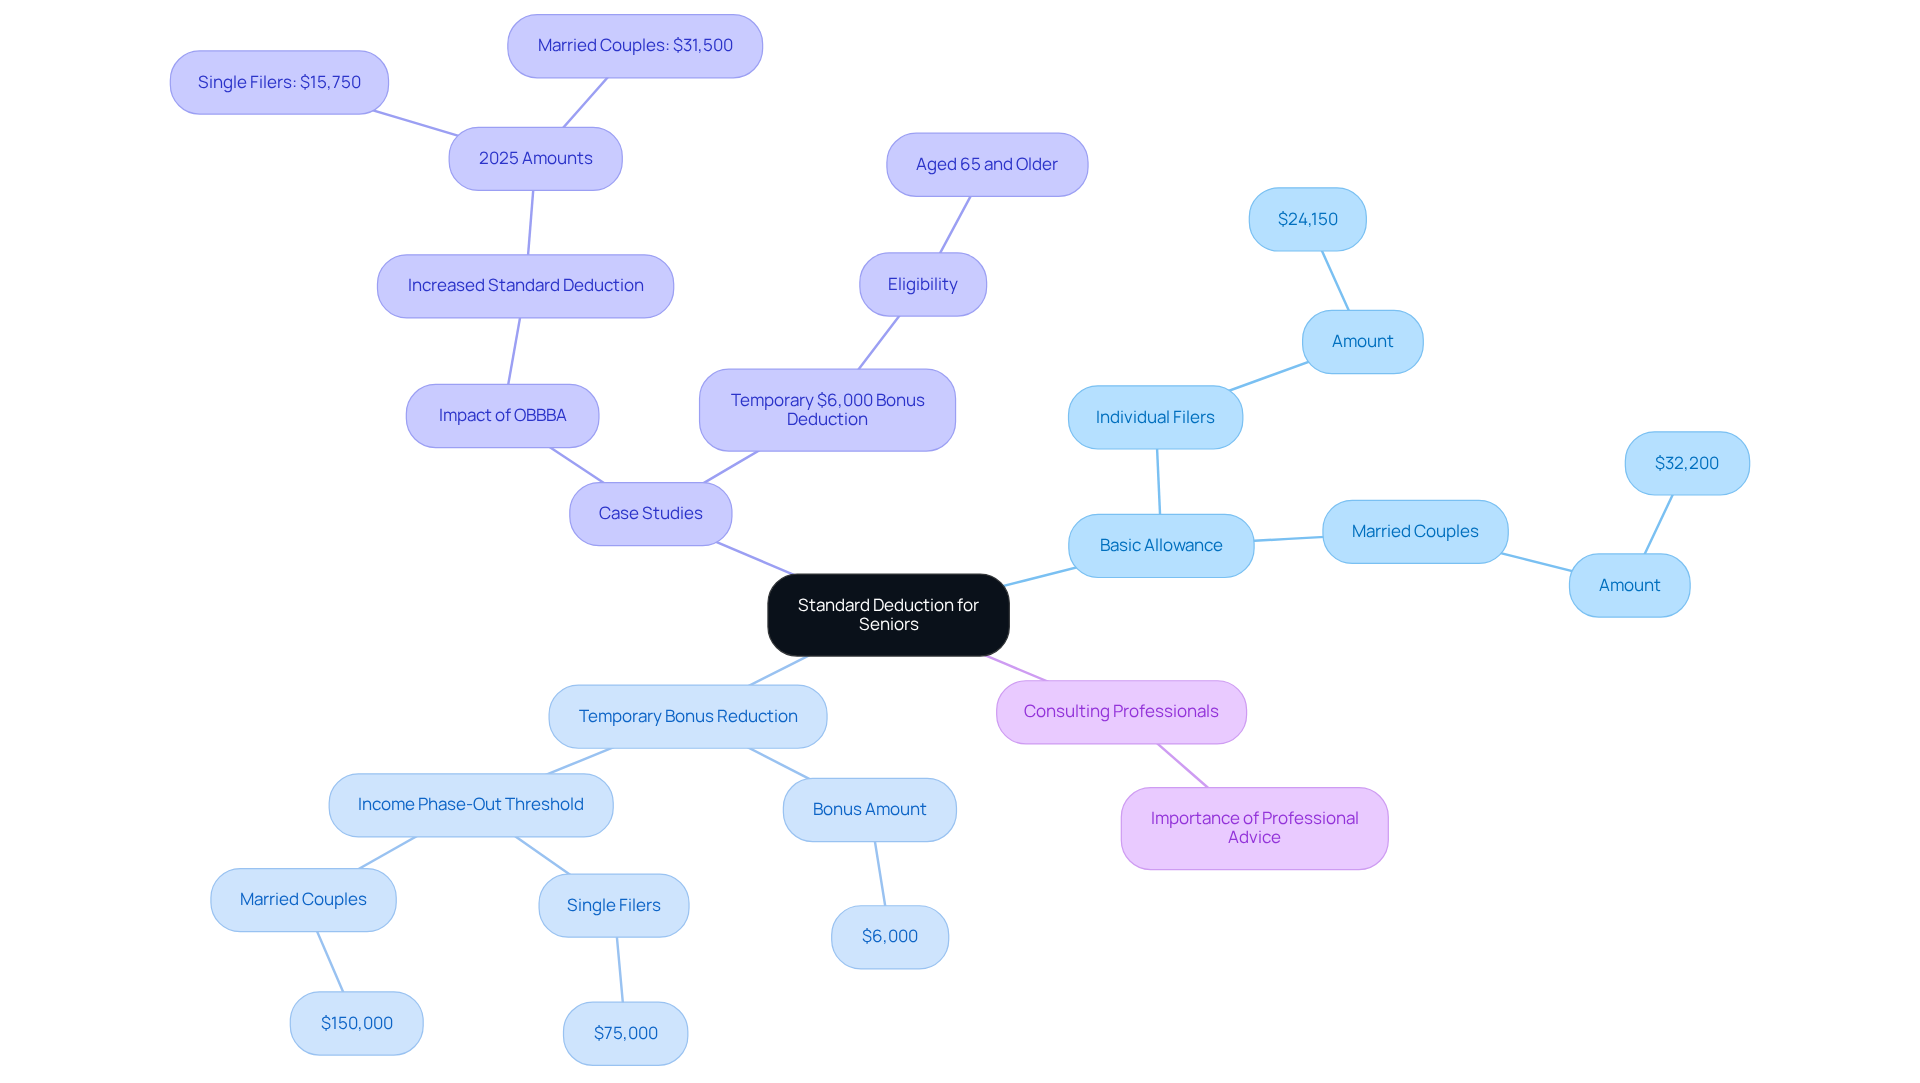
- The standard deduction for seniors aged 65 and older is higher than for younger taxpayers, with amounts set at $24,150 for individuals and $32,200 for married couples filing jointly in 2026.
- Widows over 65 can claim a standard deduction of $41,500, which includes an additional $6,000 for age, available for two years after the spouse’s passing.
- Eligibility for the widow’s deduction requires paying more than half the cost of maintaining the home and is subject to income phase-outs for higher earners.
- A temporary $6,000 bonus reduction for seniors is available from 2025 to 2028, phasing out for individuals with modified adjusted gross incomes above $75,000.
- Understanding the difference between standard and itemised deductions is crucial for seniors, as itemising may benefit those with significant expenses.
- Consulting a tax professional can help seniors navigate these deductions and optimise their financial situation.
Introduction
Many seniors feel lost when trying to navigate tax deductions, especially after a significant loss. For widows over 65, the standard deduction offers a vital lifeline, providing substantial tax relief that can ease financial burdens during a challenging time.
Imagine if understanding the standard deduction could empower widows to reclaim their financial stability while focusing on what truly matters – family and well-being. It’s important to understand how these changes affect you and your family.
As the tax landscape evolves, questions about eligibility and benefits can arise, but with the right knowledge, you can find peace of mind.
Define the Standard Deduction for Seniors
Imagine the relief of simplifying your tax process as you age, allowing you to focus more on your family. The basic allowance is a set dollar figure that lowers the income subject to taxation. For seniors, especially those aged 65 and above, the typical allowance is greater than for younger taxpayers. This increase acknowledges the financial challenges that often accompany aging. For the tax year 2026, what is the standard deduction for a widow over 65, considering that the basic allowance for individual filers aged 65 and older is $24,150, while married couples filing jointly can claim $32,200 if both partners are over 65. This reduction helps make tax filing easier, so seniors can lower their taxable income without the hassle of itemizing expenses.
The recent changes to the standard allowance are particularly advantageous for seniors. For instance, the introduction of a temporary $6,000 bonus reduction for individuals aged 65 and older, available from 2025 to 2028, further enhances tax relief. This bonus reduction phases out for individuals with modified adjusted gross incomes surpassing $75,000, offering targeted assistance for qualifying seniors.
Case studies demonstrate the effect of these reductions. For instance, the One Big Beautiful Bill Act (OBBBA) raised the basic allowance for tax year 2025, which has established a precedent for continuous modifications. These changes can help ease financial burdens, allowing seniors to focus on what truly matters – spending time with family. As tax laws evolve, talking to a tax professional can really help you understand these benefits and how they might affect your situation. By understanding these benefits, you can take control of your finances and enjoy more precious moments with your loved ones.
Detail the Standard Deduction Amount for Widows Over 65
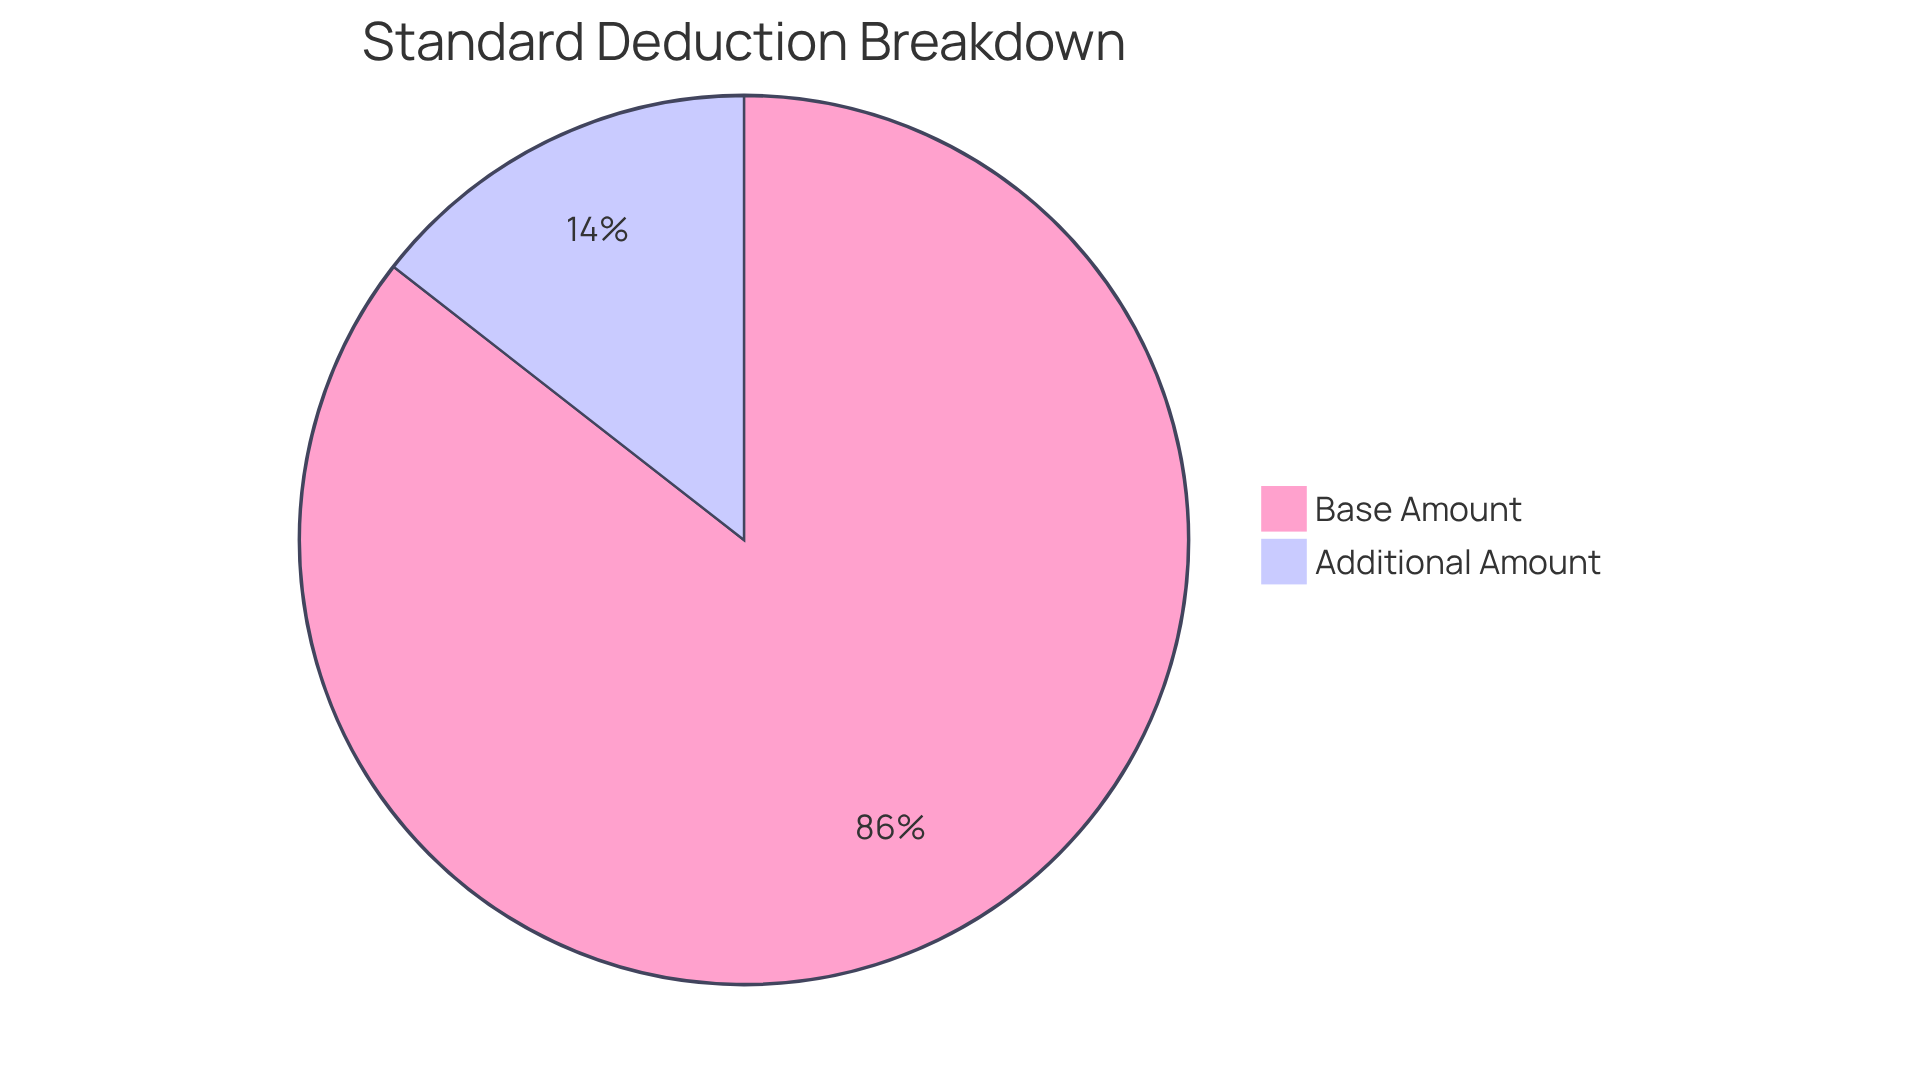
Imagine facing the world alone after losing a partner, with financial worries weighing heavily on your heart. For widows over 65, understanding what is the standard deduction for a widow over 65 reveals a silver lining in the considerable financial assistance available. In 2026, a widow filing as a qualifying surviving spouse can claim what is the standard deduction for a widow over 65, which totals $41,500, including an extra $6,000 for being over 65. This improved allowance is accessible for two years after the passing of a spouse, allowing widows to experience comparable tax advantages as when they were wed.
To qualify for this status, the widow must have paid more than half the cost of maintaining her home. However, it’s important to understand that the full advantage of the bonus reduction phases out for:
- Joint filers with modified adjusted gross income (MAGI) above $250,000
- Single filers above $175,000
These tax advantages can provide a much-needed cushion during this challenging time, enabling widows to retain more of their income as they navigate new economic circumstances. Understanding these benefits can empower you to focus on healing while ensuring your financial stability.
Explain Eligibility Requirements for the Standard Deduction
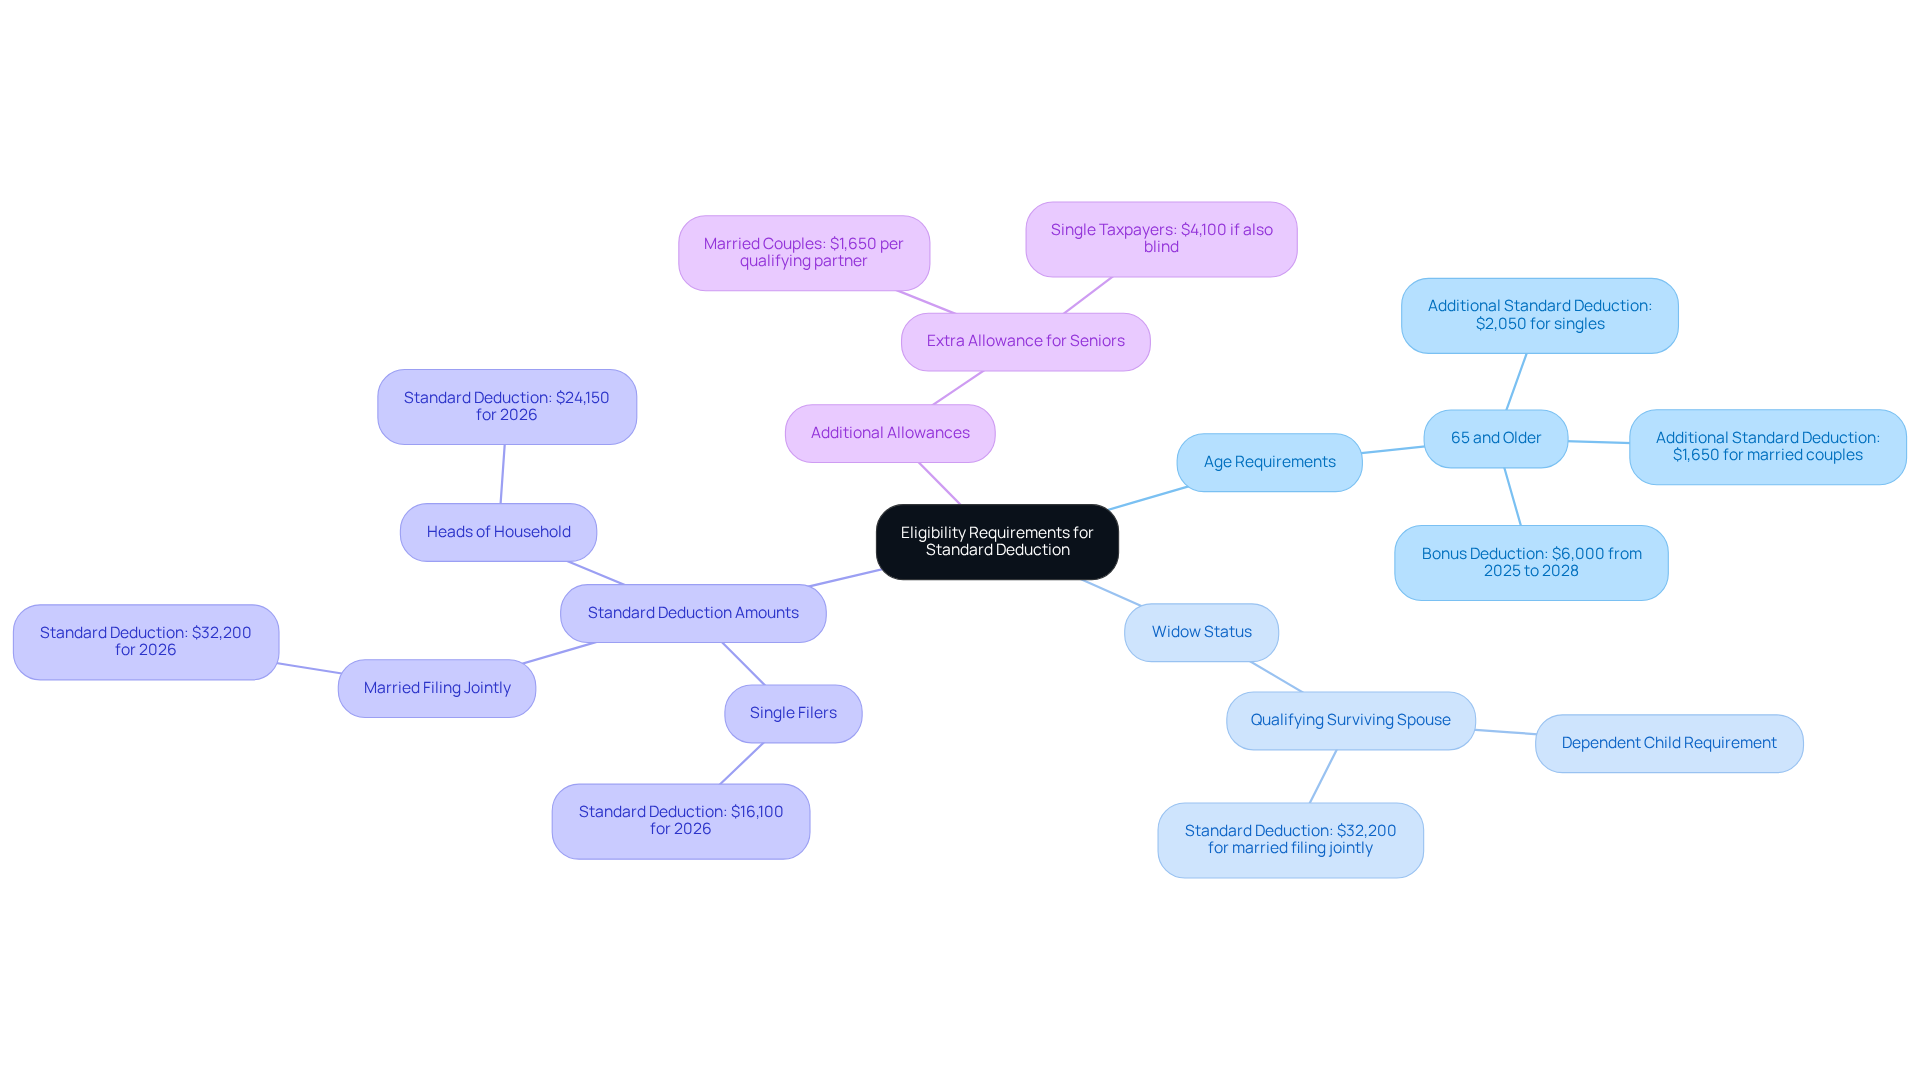
Navigating tax responsibilities can feel overwhelming, especially for seniors who are trying to secure their family’s future. Let’s explore how you can qualify for the basic allowance, ensuring you get the support you deserve. For seniors aged 65 and older, the primary requirement is simply age; you must be 65 by the end of the tax year. If you’re a widow filing as a qualifying surviving spouse, having lost your spouse within the last two years and having a dependent child can help you understand what is the standard deduction for a widow over 65 to request a larger basic allowance. This status allows you to request a larger basic allowance, providing much-needed relief as you navigate your tax responsibilities.
For the upcoming 2026 tax year, individual filers may be interested in what is the standard deduction for a widow over 65, which is set at a basic allowance of $16,100. If you’re aged 65 and above, you can claim an extra standard allowance of $2,050. Married couples filing jointly can claim an additional $1,650 for each qualifying partner aged 65 or older. Moreover, the increased allowance for seniors enables individuals aged 65 and above to claim an extra $6,000 reduction per person, or $12,000 for married couples filing jointly, from 2025 through 2028. These provisions can ease the tax burden for eligible seniors, helping them make the most of their benefits and focus on what truly matters. Remember, understanding these allowances can lighten your financial load, allowing you to focus on what truly matters-your family.
Compare Standard Deduction and Itemized Deductions
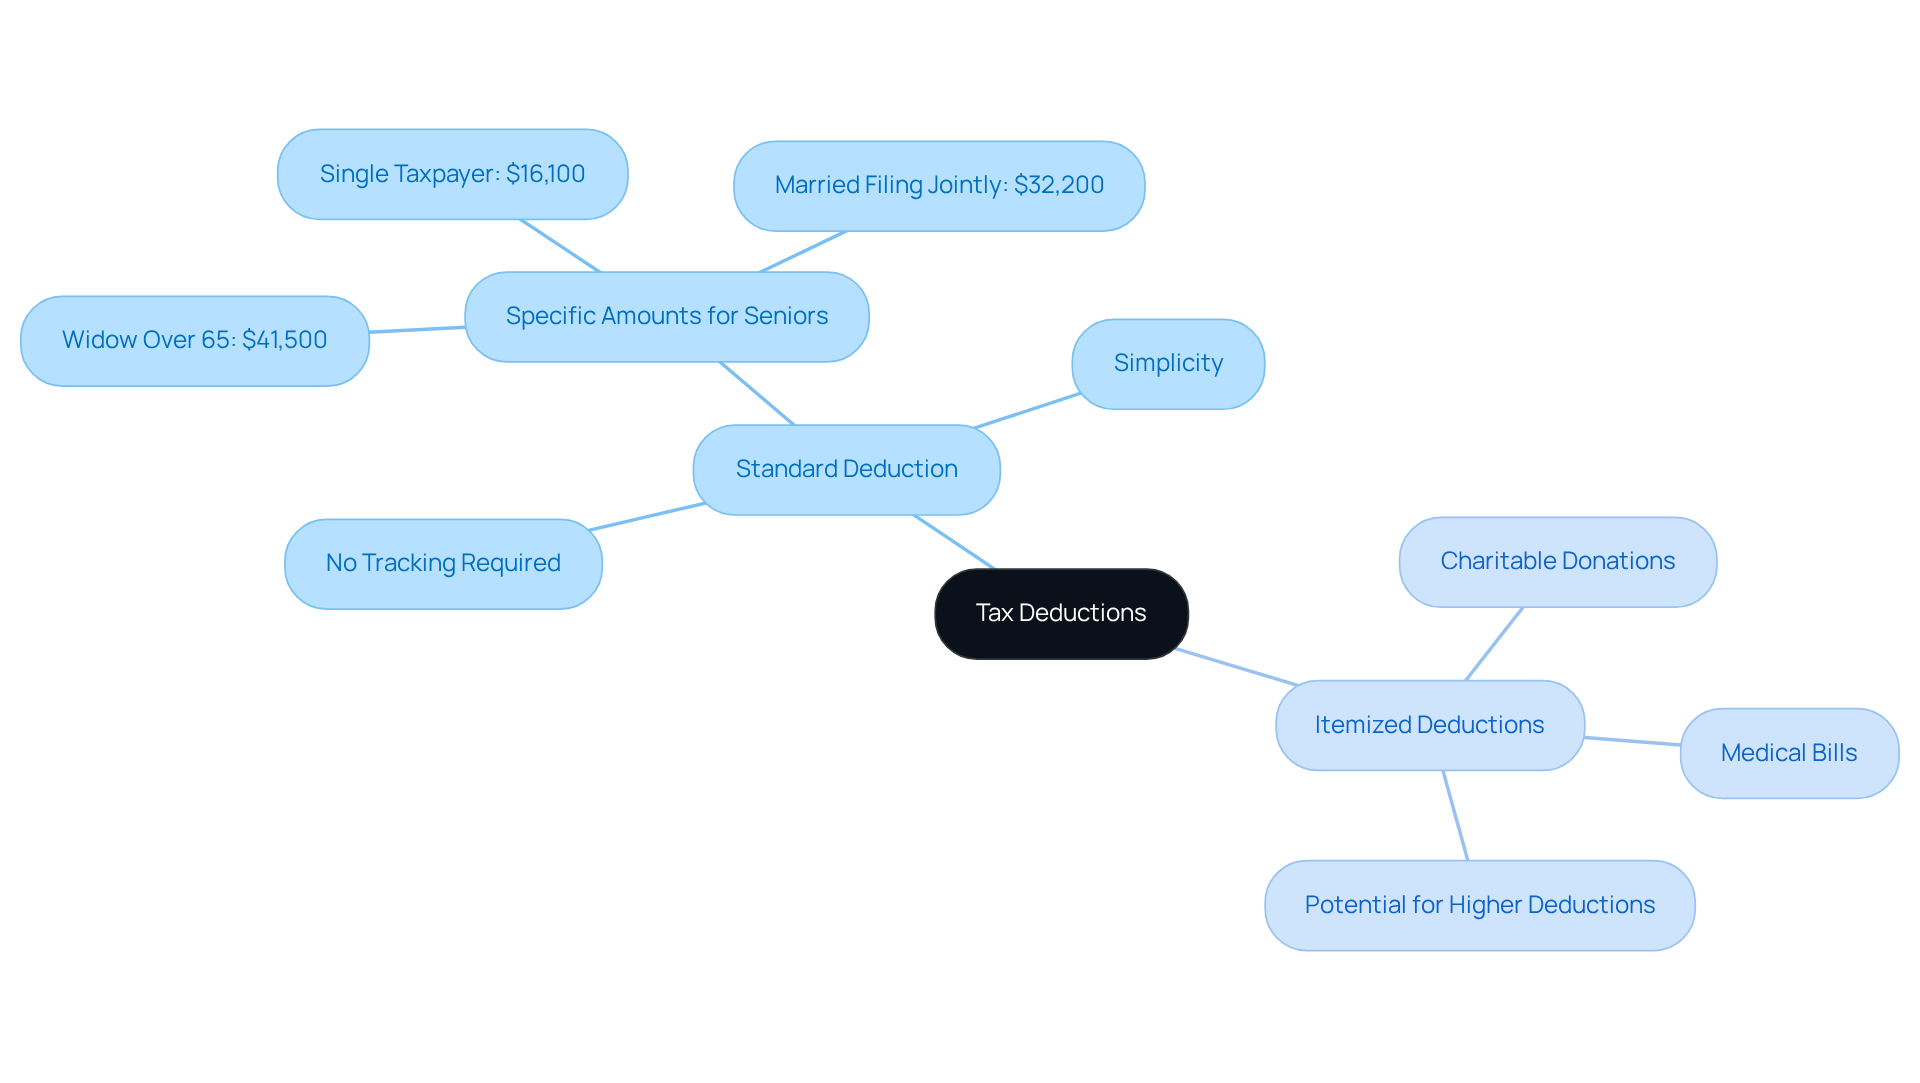
Imagine feeling overwhelmed by choices when all you want is to simplify your financial life. The standard deduction can be a lifesaver, offering a straightforward way to lower your taxable income without the hassle of keeping track of every little expense. But if you have significant expenses, itemizing might be the way to go, allowing you to claim things like medical bills and donations to your favorite charities.
For many older adults, especially widows over 65, understanding what is the standard deduction for a widow over 65 often feels like a comforting choice, providing both simplicity and value. Grasping these options is crucial for families navigating the challenges of life after loss, helping them feel more secure in their financial decisions. Taking a proactive approach to tax planning can ease the burden during tough transitions, helping families feel ready for whatever comes next.
Take Allison and Brian, for instance. In their late 40s, they found themselves struggling to improve their financial situation because they hadn’t planned their taxes effectively. Even with good incomes, they didn’t realize the financial opportunities slipping through their fingers. Working with Bright Advisers opened their eyes to how tax planning could help them reduce liabilities and grow their wealth. Their journey highlights how crucial it is to understand the difference between standard and itemized deductions, especially for young families aiming for financial stability.
Conclusion
Navigating tax responsibilities can feel overwhelming, especially for widows over 65 during such a challenging time. Imagine feeling the weight lift as this deduction simplifies your tax process and helps you keep more of your hard-earned income. With the standard deduction amount set at $41,500 for qualifying surviving spouses in 2026, it becomes a vital tool for easing financial burdens and fostering stability.
Throughout this article, we’ve shared key insights about the eligibility requirements and advantages of the standard deduction. It’s important to understand that as a widow, you can benefit from an additional allowance due to your age, and the temporary bonus reduction further enhances your tax relief. The comparison between standard and itemized deductions underscores the importance of making informed choices that align with your unique financial situation, especially as a senior facing distinct challenges.
When you understand the standard deduction, you can make choices that truly prioritize your well-being and that of your family. Engaging with a tax professional can provide personalized guidance, ensuring that every eligible benefit is maximized. By prioritizing tax planning, families can focus on what truly matters – cherishing moments with loved ones and creating lasting memories.
Frequently Asked Questions
What is the standard deduction for seniors aged 65 and above for the tax year 2026?
For the tax year 2026, the standard deduction for individual filers aged 65 and older is $24,150. For married couples filing jointly, if both partners are over 65, they can claim a standard deduction of $32,200.
How does the standard deduction help seniors with their taxes?
The standard deduction lowers the income subject to taxation, making tax filing easier for seniors. It allows them to reduce their taxable income without the need to itemize expenses, which can simplify the tax process.
What additional tax relief is available for seniors from 2025 to 2028?
From 2025 to 2028, there is a temporary $6,000 bonus reduction available for individuals aged 65 and older. This bonus reduction phases out for individuals with modified adjusted gross incomes exceeding $75,000.
What recent legislation has impacted the standard deduction for seniors?
The One Big Beautiful Bill Act (OBBBA) raised the basic allowance for the tax year 2025, establishing a precedent for ongoing modifications to the standard deduction that can benefit seniors.
Why is it important for seniors to understand these tax benefits?
Understanding these tax benefits can help seniors take control of their finances, ease financial burdens, and allow them to focus on spending quality time with family. Consulting a tax professional can provide personalized insights into how these changes may affect individual situations.
List of Sources
- Define the Standard Deduction for Seniors
- Standard deduction 2026: What it is and how it works | Fidelity (https://fidelity.com/learning-center/smart-money/standard-deduction)
- IRS Updates 2026 Tax Deduction for People Age 65 and Older (https://kiplinger.com/taxes/new-tax-deduction-change-over-65)
- Federal Individual Income Tax Brackets, Standard Deductions, and Personal Exemption: 1988 to 2026 (https://congress.gov/crs-product/RL34498)
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill)
- IRS Releases 2026 Tax Brackets, Contribution Limits, Other Tax Updates | PERA On The Issues (https://copera.org/pera-on-the-issues/irs-releases-2026-tax-brackets-contribution-limits-other-tax-updates)
- Detail the Standard Deduction Amount for Widows Over 65
- Standard Deduction for a Widow Over 65: Rules and Strategies (https://smartasset.com/taxes/what-is-the-standard-deduction-for-a-widow-over-65)
- The Extra Standard Deduction for People Age 65 and Older: How Much Can You Save? (https://kiplinger.com/taxes/extra-standard-deduction-age-65-and-older)
- Qualifying surviving spouse: What’s the tax filing status after the death of your spouse? (https://hrblock.com/tax-center/filing/personal-tax-planning/qualifying-widow-or-widower?srsltid=AfmBOorSeKHR_s22W4G16fiGkdHwiO_VRl7q98bpq64EmtABB41GSZhg)
- Standard deduction 2026: What it is and how it works | Fidelity (https://fidelity.com/learning-center/smart-money/standard-deduction)
- Explain Eligibility Requirements for the Standard Deduction
- IRS Updates 2026 Tax Deduction for People Age 65 and Older (https://kiplinger.com/taxes/new-tax-deduction-change-over-65)
- Standard Deduction 2026: Amounts, How It Works – NerdWallet (https://nerdwallet.com/taxes/learn/standard-deduction)
- IRS Releases 2026 Tax Brackets, Contribution Limits, Other Tax Updates | PERA On The Issues (https://copera.org/pera-on-the-issues/irs-releases-2026-tax-brackets-contribution-limits-other-tax-updates)
- 2026 filing season updates and resources for seniors | Internal Revenue Service (https://irs.gov/newsroom/2026-filing-season-updates-and-resources-for-seniors)
- Filing Taxes as a Widow(er) in 2026: Complete Guide for Surviving Spouses (https://wingsforwidows.org/popular-articles/how-to-file-taxes-in-2026-as-a-recent-widow-or-widower)
- Compare Standard Deduction and Itemized Deductions
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill)
- Standard Deduction vs. Itemized Deductions: Which Is Better? (https://turbotax.intuit.com/tax-tips/tax-deductions-and-credits/tax-deduction-wisdom-should-you-itemize/amp/L8Ln7K0Gp)
- Standard Deduction for a Widow Over 65: Rules and Strategies (https://smartasset.com/taxes/what-is-the-standard-deduction-for-a-widow-over-65)
- New Tax Break for Seniors – Center for Retirement Research (https://crr.bc.edu/new-tax-break-for-seniors)
- Federal Individual Income Tax Brackets, Standard Deductions, and Personal Exemption: 1988 to 2026 (https://congress.gov/crs-product/RL34498)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading