

Overview
Imagine a world where your family can save significantly on healthcare costs. The upside to having a high deductible in insurance primarily includes lower monthly premiums, allowing you to allocate more resources toward what truly matters—your family’s well-being. When paired with Health Savings Accounts (HSAs), you not only enjoy these lower costs but also gain the potential for substantial annual savings, all while benefiting from tax advantages.
It’s important to understand that families can save approximately $1,524 annually in premiums with high deductible health plans (HDHPs). This encourages a more budget-conscious approach to healthcare, making it easier for you to manage expenses without sacrificing quality care. Plus, HSAs offer a wonderful opportunity for tax-free savings that can be used for medical expenses, providing peace of mind during uncertain times.
Together, we can navigate this journey toward financial wellness, ensuring that your family’s health and financial priorities are met with compassion and support. We’re here for you every step of the way, helping you make informed decisions that align with your family’s values and goals.
Key Highlights:
- HDHPs have higher deductibles and lower monthly premiums, appealing to healthy families who may not expect frequent medical visits.
- For 2025, the IRS defines HDHPs with minimum deductibles of $1,650 for individuals and $3,300 for families, and maximum out-of-pocket expenses of $8,300 for individuals and $16,600 for families.
- Pairing HDHPs with Health Savings Accounts (HSAs) offers tax benefits, allowing families to save for healthcare costs while reducing overall expenses.
- Since 2018, enrolment in HDHPs has declined, indicating families are carefully considering their healthcare options.
- HDHPs can lead to savings of approximately $1,524 annually in premiums, freeing up funds for other household needs.
- Families using HDHPs are encouraged to shop for medical services, potentially leading to better pricing and quality of care.
- However, HDHPs can result in significant out-of-pocket costs, which may deter families from accessing necessary medical treatment.
- Studies show insured adults with chronic conditions are more likely to forgo medications due to high costs associated with HDHPs.
- 48% of families in HDHPs struggle to pay medical bills, compared to 21% in traditional plans, highlighting the financial challenges these plans can pose.
Introduction
Navigating the complexities of health insurance can feel overwhelming for families striving to balance their financial responsibilities with healthcare needs. Imagine if you could lower your monthly premiums while still having coverage for unexpected medical expenses. High deductible health plans (HDHPs) have emerged as a compelling option for many families.
But what is the upside to having a high deductible? This article gently explores the potential benefits and challenges of HDHPs, offering insights that could significantly impact your family’s financial well-being and healthcare decisions.
As healthcare costs continue to rise, it’s important to understand the advantages and risks associated with high deductibles. Together, we can navigate this journey, making informed choices in a rapidly evolving insurance landscape.
Define High Deductible: Understanding the Concept
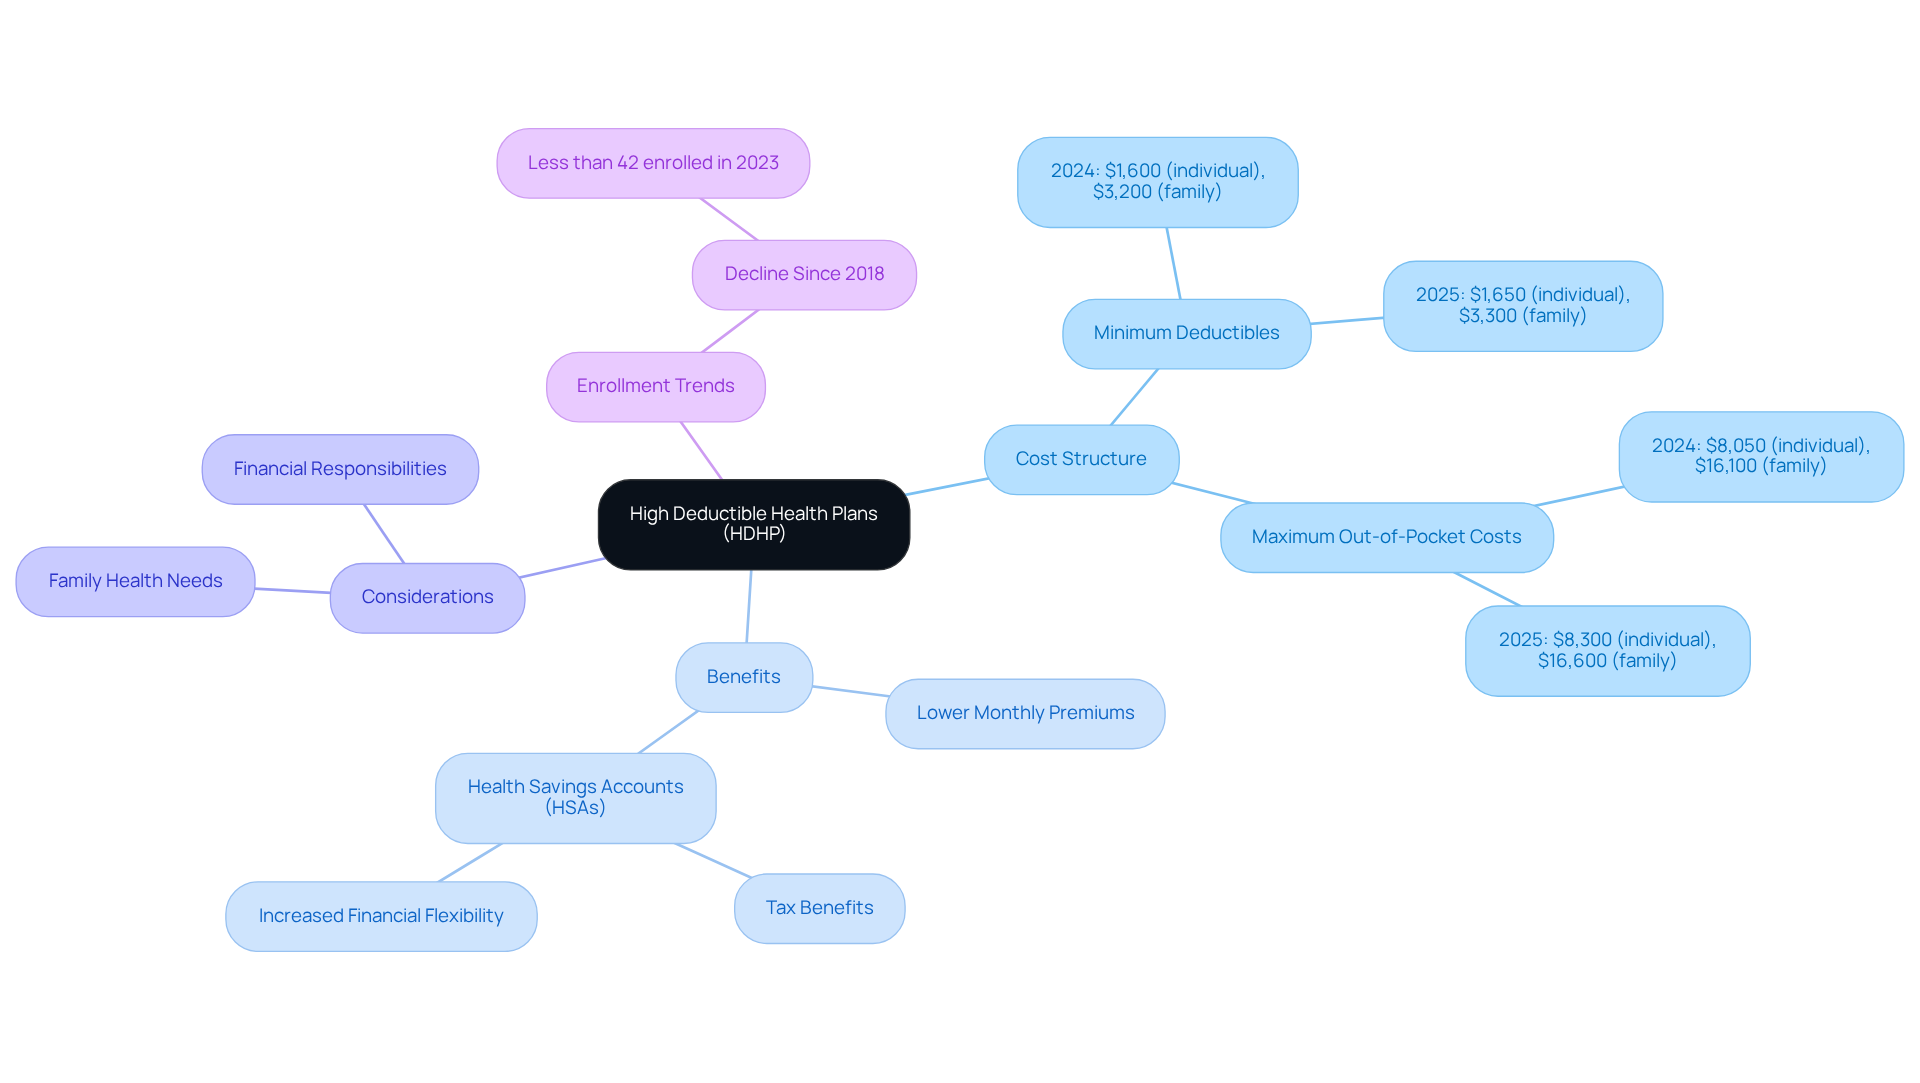
Navigating health insurance can feel overwhelming, especially for young parents trying to balance family needs with financial responsibilities. When considering a high deductible health plan (HDHP), it’s important to ask what is the upside to having a high deductible. With higher deductibles than traditional plans, policyholders typically face more out-of-pocket costs before their insurance kicks in. For 2025, the IRS defines an HDHP as having a minimum deductible of $1,650 for individuals and $3,300 for families, with maximum out-of-pocket expenses set at $8,300 for individuals and $16,600 for families.
These plans often come with lower monthly premiums, making them appealing for families who are generally healthy and don’t expect frequent medical visits, leading to the question: what is the upside to having a high deductible? Understanding this can be crucial as you explore healthcare choices and budgeting for your family’s future. Imagine if you could reduce monthly expenses while still having coverage for unexpected medical needs.
It’s also important to consider pairing HDHPs with Health Savings Accounts (HSAs). HSAs offer tax benefits and improve your financial flexibility, allowing you to save for healthcare costs while enjoying peace of mind. Before enrolling in an HDHP, take the time to review the minimum deductible and maximum out-of-pocket amounts. Experts like Charlene Rhinehart advise this thoughtful approach to ensure you make the best choice for your family.
Interestingly, there has been a trend of declining enrollment in HDHPs since 2018. This suggests that families are carefully weighing their options, making it essential to understand what is the upside to having a high deductible in addition to the benefits and potential drawbacks of these plans. Together, we can navigate this journey and find the right healthcare solution for your family’s unique needs.
Contextualize High Deductibles: Importance in Insurance
High deductible health plans (HDHPs) prompt the inquiry of what is the upside to having a high deductible as a thoughtful approach to managing rising medical expenses. These plans encourage individuals to consider what is the upside to having a high deductible by shifting a larger portion of monetary responsibility to consumers, prompting a more budget-aware approach to their medical choices. This trend is particularly relevant as healthcare expenses continue to rise, prompting families to navigate their budgets with greater care.
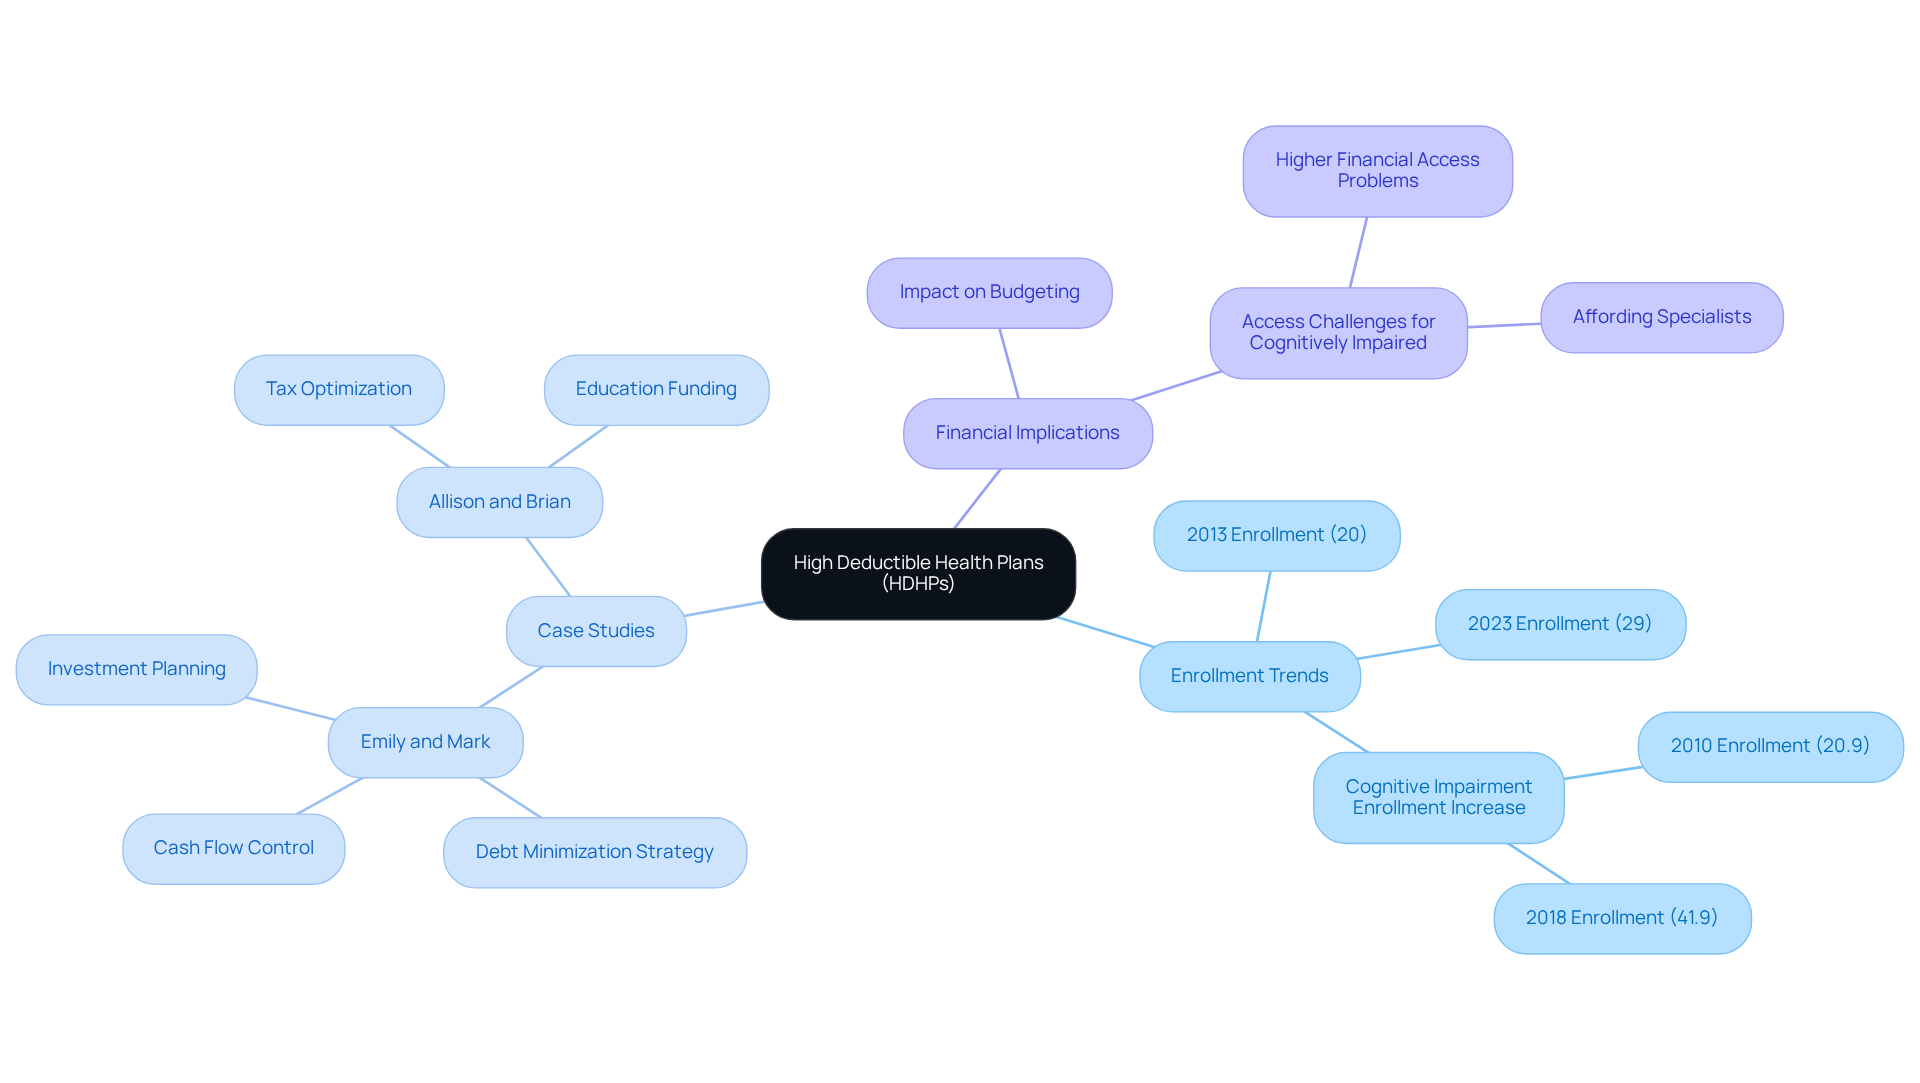
Imagine this: in 2023, approximately 54.7% of the U.S. population relied on employer-sponsored insurance, with a notable increase in HDHP enrollment, rising from 20% in 2013 to 29% in 2023. Families often combine HDHPs with Health Savings Accounts (HSAs), allowing them to save money tax-free for medical expenses, thus enhancing their planning capabilities.
Consider the case of Emily and Mark, a young couple pursuing economic independence. They utilized HDHPs as part of a comprehensive monetary strategy created with Bright Advisers. By executing plans to minimize debt, control cash flow, and invest wisely, they were able to allocate funds more efficiently for both medical needs and other essential costs.
Similarly, Allison and Brian achieved significant economic stability through tax optimization and education funding, which allowed them to enjoy more quality time with their loved ones. However, it’s important to understand that individuals with cognitive impairment may face access challenges under HDHPs, complicating their medical choices.
Grasping the implications of HDHPs is essential for families seeking to understand what is the upside to having a high deductible when making informed decisions about their insurance options. These plans not only influence immediate medical expenses but also impact long-term economic well-being. Together, we can navigate this journey, ensuring that your family’s financial health is prioritized.
Explore Benefits: The Upside of High Deductibles
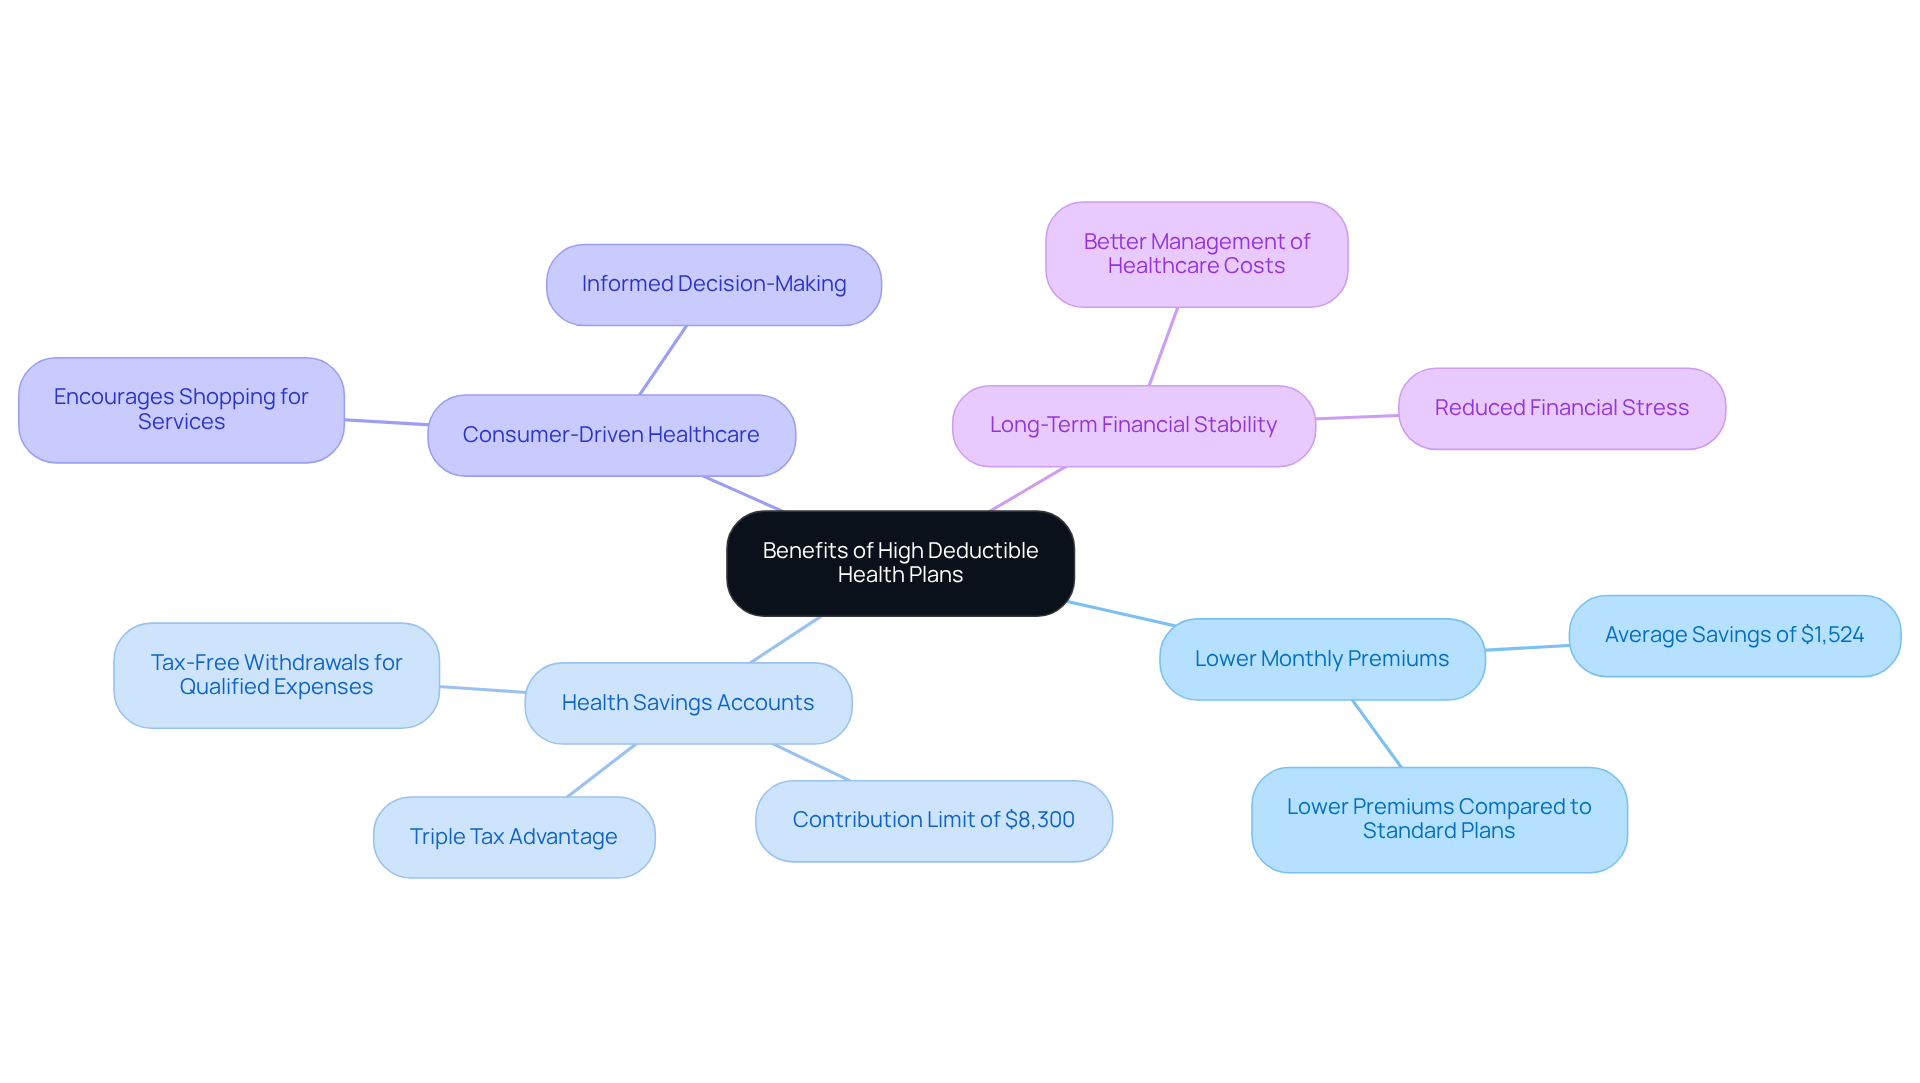
High deductible health plans (HDHPs) offer several appealing advantages, prompting the inquiry of what is the upside to having a high deductible for individuals like Jay and Emma who are striving to manage their healthcare costs effectively and reduce financial stress. One of the most significant benefits is the lower monthly premiums associated with these plans, which can lead to substantial savings. Imagine saving an average of $1,524 each year in premiums by switching to an HDHP instead of conventional plans. This reduction in monthly expenses can free up funds for other essential household needs, like saving for retirement or funding educational costs for your children.
Moreover, HDHPs are designed to work hand-in-hand with Health Savings Accounts (HSAs), allowing families to contribute up to $8,300 per year in pre-tax dollars. This triple tax advantage—pre-tax contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses—can significantly lower overall health-related costs. Families who generally maintain good health may consider what is the upside to having a high deductible, as the savings from lower premiums and tax benefits might outweigh the risks of higher out-of-pocket costs.
Additionally, HDHPs encourage a more consumer-driven approach to medical services. Families are inspired to shop around for services, which can lead to better pricing and improved quality of care. This proactive involvement in medical decisions not only helps households save money but also fosters a more informed way of managing medical expenses. Ultimately, this can enhance long-term financial stability and alleviate monetary stress.
Case studies reveal that families utilizing HDHPs and HSAs can effectively manage their medical expenses while maintaining access to essential services. As healthcare costs continue to rise, families may question what is the upside to having a high deductible, as the strategic use of HDHPs presents a viable option for improving their financial well-being while ensuring adequate coverage. Together, we can navigate this journey towards better health and financial security.
Examine Drawbacks: Understanding the Risks of High Deductibles
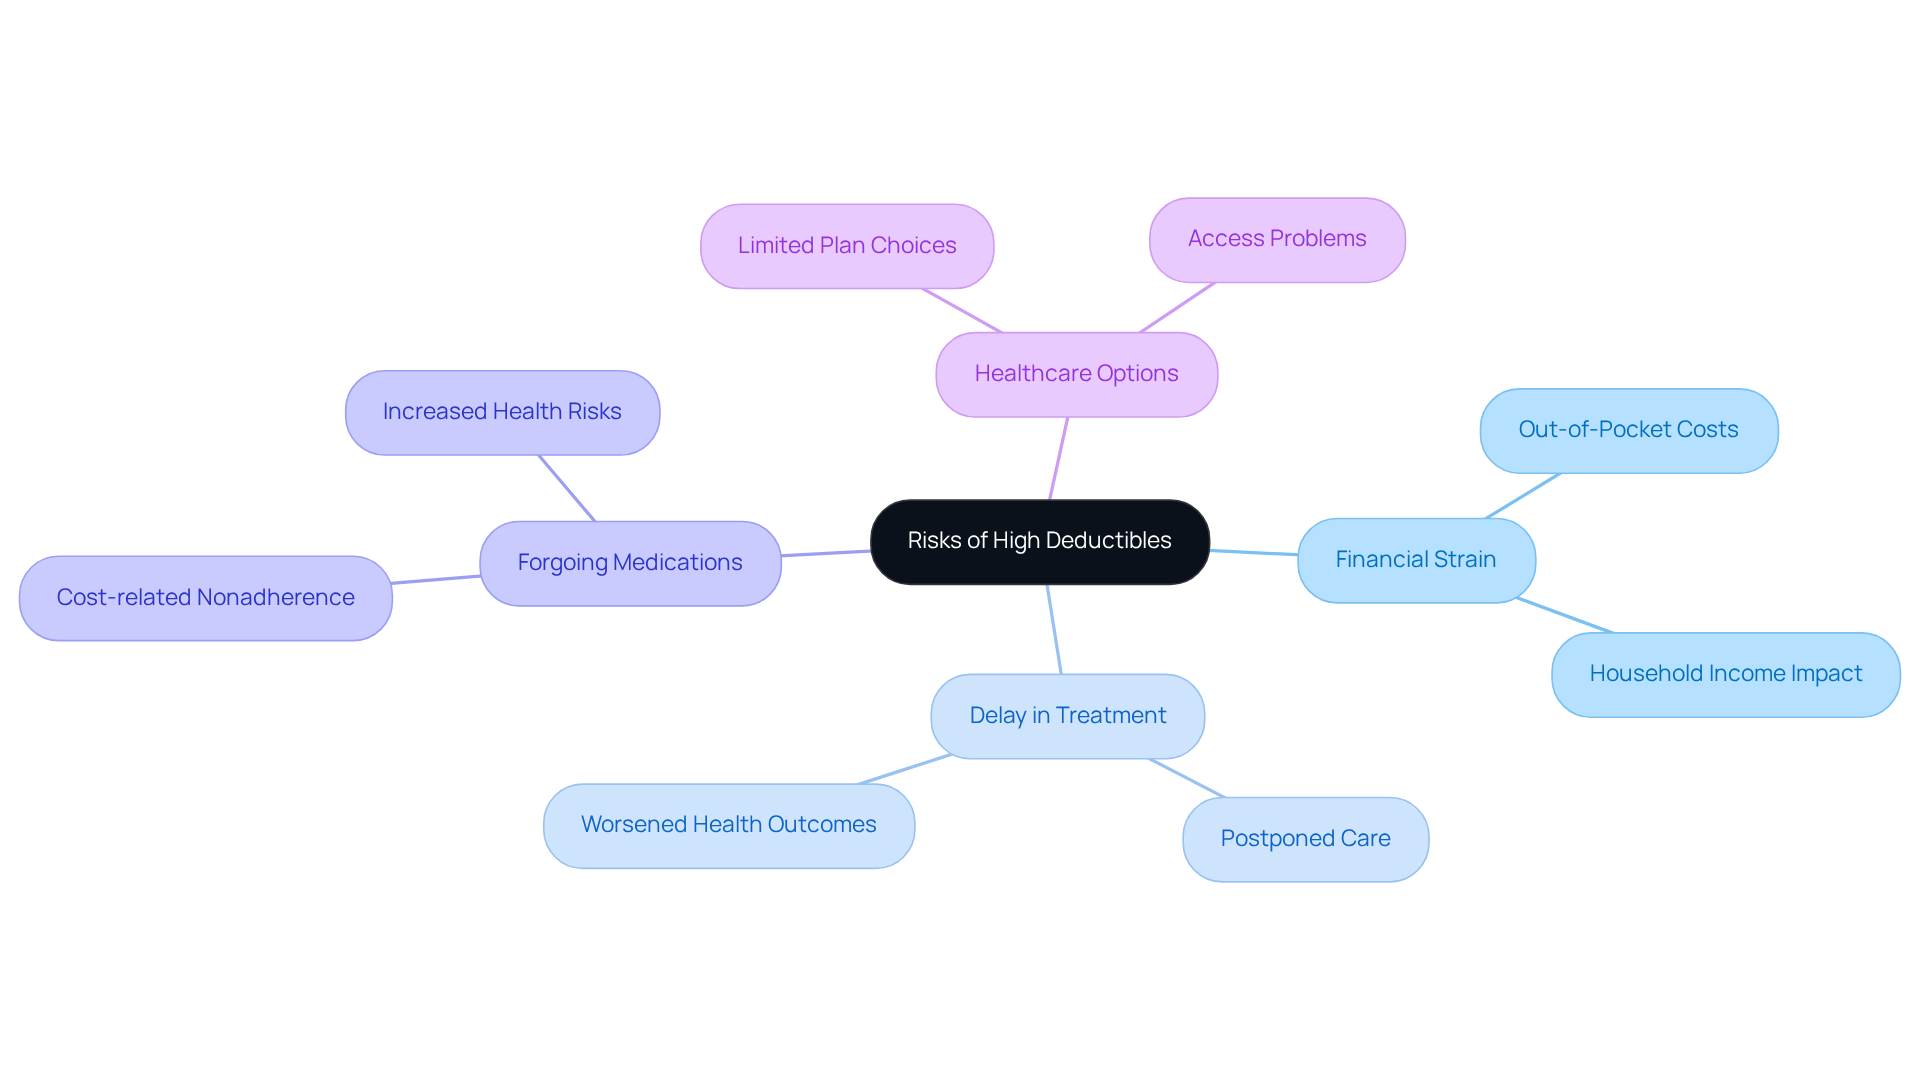
While high deductible insurance plans (HDHPs) can offer various benefits, families must carefully consider what is the upside to having a high deductible along with the significant disadvantages. Imagine facing the possibility of substantial out-of-pocket expenses—this can be particularly daunting for families managing ongoing medical conditions or navigating unexpected health crises. In 2019, approximately 15% of households spent over 10% of their yearly income on out-of-pocket costs, highlighting the financial strain many families endure. This burden can lead to delays in essential medical treatment, creating a ripple effect that impacts overall wellness over time.
It’s important to understand that studies show insured adults with chronic conditions are twice as likely to forgo necessary prescription medications due to cost, which can worsen their health challenges. Additionally, the stress of managing a high deductible can weigh heavily on families operating within tight budgets, with 62% of adults expressing concern about affording medical services.
As families explore their healthcare options, understanding what is the upside to having a high deductible becomes crucial in determining whether an HDHP aligns with their financial situation and healthcare needs. Case studies reveal that families enrolled in HDHPs often report significant financial challenges, with 48% indicating they struggle to pay medical bills, compared to just 21% in traditional plans. This stark contrast underscores the necessity of thoughtful consideration when selecting a health insurance plan. Together, we can navigate this journey, ensuring that families make informed choices that prioritize their health and financial well-being.
Conclusion
High deductible health plans (HDHPs) offer a unique opportunity for families to manage healthcare costs with intention. While these plans come with higher out-of-pocket expenses before insurance coverage kicks in, they often feature lower monthly premiums. This can make them an appealing choice for families in good health or those aiming to save on insurance costs. It’s essential to understand both the benefits and potential drawbacks of HDHPs to make informed decisions that align with your health and financial goals.
Imagine the peace of mind that comes with significant savings on premiums. HDHPs allow families to contribute to Health Savings Accounts (HSAs), fostering a more consumer-driven approach to healthcare. These advantages can enhance your family’s financial stability while encouraging proactive healthcare management. However, it’s important to acknowledge the challenges that high deductibles pose, especially for those with chronic conditions or unpredictable medical needs. The financial strain of high out-of-pocket costs can lead to delays in necessary care and increased stress for families.
Ultimately, choosing a high deductible health plan should be a thoughtful decision based on your individual circumstances and healthcare needs. As healthcare costs continue to rise, we encourage families to weigh the benefits against the potential risks. This ensures that your choice supports both your immediate health requirements and long-term financial well-being. Exploring options like HDHPs can be a valuable step towards achieving greater financial security while maintaining access to essential healthcare services. Remember, together, we can navigate this journey, ensuring you have the support you need every step of the way.
Frequently Asked Questions
What is a high deductible health plan (HDHP)?
A high deductible health plan (HDHP) is a type of health insurance plan that has higher deductibles than traditional plans. For 2025, the IRS defines an HDHP as having a minimum deductible of $1,650 for individuals and $3,300 for families.
What are the maximum out-of-pocket expenses for HDHPs in 2025?
The maximum out-of-pocket expenses for HDHPs in 2025 are set at $8,300 for individuals and $16,600 for families.
What are the advantages of having a high deductible?
The main advantage of having a high deductible is that HDHPs typically come with lower monthly premiums, which can be appealing for families who are generally healthy and do not expect frequent medical visits.
How can Health Savings Accounts (HSAs) benefit those with HDHPs?
Health Savings Accounts (HSAs) offer tax benefits and improve financial flexibility, allowing individuals to save for healthcare costs while providing peace of mind.
What should families consider before enrolling in an HDHP?
Families should review the minimum deductible and maximum out-of-pocket amounts before enrolling in an HDHP to ensure they make the best choice for their unique needs.
Is there a trend in enrollment for HDHPs?
Yes, there has been a trend of declining enrollment in HDHPs since 2018, indicating that families are carefully weighing their options regarding these plans.
List of Sources
- Define High Deductible: Understanding the Concept
- Health plans with high deductibles are becoming less popular (https://statnews.com/2024/12/05/high-deductible-health-insurance-plans-drop-second-straight-year-cdc-says)
- High-Deductible Health Plan (HDHP) Limits for 2025 – GoodRx (https://goodrx.com/insurance/hdhp/high-deductible-health-plan-limits?srsltid=AfmBOorY84dkX2PUBOLXGhRFiC6z6qCIfDwIAXHO_FFciw1d8qvWoxGn)
- CDC finds 43.2% of Americans have high-deductible health plans: 4 additional stats – Becker’s Payer Issues | Payer News (https://beckerspayer.com/payer/cdc-finds-43-2-of-americans-have-high-deductible-health-plans-4-additional-stats)
- What You Need to Know About High-Deductible Health Plans in 2025 (https://investopedia.com/terms/h/hdhp.asp)
- High-Deductible Health Plan Enrollment and Prostate Cancer Screening Rates (https://jamanetwork.com/journals/jama-health-forum/fullarticle/2831838)
- Contextualize High Deductibles: Importance in Insurance
- High deductible health plans and health savings accounts (https://bls.gov/ebs/factsheets/high-deductible-health-plans-and-health-savings-accounts.htm)
- 21 statistics on high-deductible health plans – Becker’s Hospital Review | Healthcare News & Analysis (https://beckershospitalreview.com/finance/21-statistics-on-high-deductible-health-plans)
- Landing | Percent of private-sector employees enrolled in high-deductible health insurance plans by Total | State Health Access Data Assistance Center (https://statehealthcompare.shadac.org/landing/172/percent-of-privatesector-employees-enrolled-in-highdeductible-health-insurance-plans-by-total)
- Trend and effects of high-deductible health insurance plans in the health care system: financial access problems in management of cognitive impairment – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC10372991)
- Section 8: High-Deductible Health Plans with Savings Option – 10240 | KFF (https://kff.org/report-section/ehbs-2023-section-8-high-deductible-health-plans-with-savings-option)
- Explore Benefits: The Upside of High Deductibles
- High deductible health plans and health savings accounts (https://bls.gov/ebs/factsheets/high-deductible-health-plans-and-health-savings-accounts.htm)
- 2024 Employer Health Benefits Survey | KFF (https://kff.org/report-section/ehbs-2024-summary-of-findings)
- Frequently Asked Questions (https://opm.gov/healthcare-insurance/healthcare/health-savings-accounts/frequently-asked-questions)
- Section 8: High-Deductible Health Plans with Savings Option – 10240 | KFF (https://kff.org/report-section/ehbs-2023-section-8-high-deductible-health-plans-with-savings-option)
- High Deductible Health Plans Are Actually Good! (https://hsaforamerica.com/blog/high-deductible-health-plans-are-good-actually)
- Examine Drawbacks: Understanding the Risks of High Deductibles
- Marketplace Affordability: The Hazards of High Deductibles – Healthcare Value Hub (https://healthcarevaluehub.org/resource/2024/marketplace-affordability-the-hazards-of-high-deductibles)
- Trend and effects of high-deductible health insurance plans in the health care system: financial access problems in management of cognitive impairment – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC10372991)
- Americans’ Challenges with Health Care Costs | KFF (https://kff.org/health-costs/americans-challenges-with-health-care-costs)
- Alleviating Financial Hardships Associated with High-Deductible Health Plans for Adults with Chronic Conditions Through Health Savings Accounts – Journal of General Internal Medicine (https://link.springer.com/article/10.1007/s11606-022-07985-5)
- Nearly Half of Families In High-Deductible Health Plans Whose Members Have Chronic Conditions Face Substantial Financial Burden – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC4423400)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin