

Overview
Understanding how financial advisors earn their income is essential for you as a parent navigating the complexities of family finances. Advisors typically operate under various compensation models, including:
- Commission-based
- Fee-only
- Fee-based
These fees can range from 0.25% to 2% of your Assets Under Management (AUM).
Imagine if you could have complete clarity about these models. It’s important to understand that fee transparency not only fosters trust but also aligns the interests of your advisor with your family’s financial goals. This alignment can significantly influence the quality of the financial planning services you receive, ensuring that your family’s needs are prioritized.
As you embark on this journey, know that we’re here for you. Together, we can navigate the intricacies of wealth management, focusing on what truly matters—your family’s future. Remember, having a supportive financial advisor can make all the difference in achieving your dreams and aspirations.
Key Highlights:
- Understanding financial advisor compensation models is essential for families navigating financial planning.
- Commission-based consultants earn income through product sales, potentially leading to conflicts of interest.
- Fee-only consultants charge clients directly, promoting transparency and aligning interests with clients.
- Fee-based consultants use a hybrid model, earning both client fees and commissions, which may introduce some conflicts.
- As of 2025, 40% of consultants still use commission-based models, while 60% have shifted to fee-only or fee-based arrangements.
- The percentage of Assets Under Management (AUM) is a common fee structure, with charges typically ranging from 0.25% to 2% annually.
- Alternative fee structures, including flat fees and hourly rates, are gaining popularity as clients seek clarity and affordability.
- Transparency in fee structures builds trust between clients and advisors, enhancing satisfaction and decision-making.
- The demand for financial advisory services is projected to grow, highlighting the importance of understanding compensation models.
Introduction
Navigating the complex world of financial advisory services can feel overwhelming, especially when trying to understand how advisors are compensated. With various compensation models—ranging from commission-based structures to fee-only arrangements—it’s crucial for clients to grasp the implications of each to meet their financial goals effectively.
Imagine if you could feel confident in your financial decisions, knowing exactly how your advisor is working for you. As the landscape shifts towards more transparent practices, particularly with the rise of fee-only advisors, it becomes increasingly important for individuals, especially young families, to comprehend the nuances of these models.
This article will gently guide you through the different financial advisor compensation structures, examining their impact on client relationships and financial planning. Together, we can explore the significance of aligning advisor incentives with your family’s objectives, ensuring that your financial journey is supported with care and understanding.
Define Financial Advisor Compensation Models
As families navigate their financial planning journey, understanding what percentage do financial advisors make in their compensation models is crucial. These models, which influence how consultants earn their income, can significantly affect the consultant-client relationship and the services offered. The primary structures include commission-based, fee-only, and fee-based models.
Imagine working with a consultant who prioritizes your family’s best interests. Commission-based consultants earn income through the sale of investment products. This approach can sometimes create conflicts of interest, as their earnings are tied to the products they recommend.
On the other hand, fee-only consultants bill clients directly for their services. This model fosters transparency and aligns their interests with yours, minimizing conflicts and building trust. Bright Advisers exemplifies this caring approach, offering hyper-personalized investment portfolios that focus on your financial goals rather than product sales. They leverage advanced technology to enhance efficiency and outcomes, ensuring that your family’s needs are met.
Then, there are fee-based consultants, who operate under a hybrid model. They earn both fees from clients and commissions from product sales, providing flexibility but potentially introducing some conflicts of interest.
As we look ahead to 2025, the wealth management landscape is shifting. More consultants are embracing fee-only models, reflecting a growing demand for transparency and trust. Recent statistics reveal that about 40% of monetary consultants still work on a commission-based model, while 60% have transitioned to fee-only or fee-based arrangements. Notably, North America leads the Financial Advisory Services Market, indicating a robust demand for these essential services.
For families, grasping these compensation models is vital. Real-world examples illustrate the differences: a commission-based consultant may prioritize selling specific investment products, while a fee-only specialist focuses on creating a customized plan that aligns with your long-term objectives. Consider Emily and Mark, a young couple striving for financial independence. They partnered with Bright Advisers to develop a comprehensive plan that not only enhanced their financial well-being but also provided the flexibility to make career choices that reflect their desired work-life balance.
Experts emphasize the importance of selecting the right compensation model. Economic specialists remind us that ‘by definition, saving for anything requires us not to acquire items now so that we can obtain larger ones later.’ This highlights the need for a consultant who prioritizes long-term strategies over immediate transactions.
Moreover, statistics show that 60% of individuals engage a financial consultant after a significant life event. This underscores the importance of having expert support during pivotal moments. With the market for consulting services projected to reach $218.96 billion by 2025, the demand for clear and effective guidance continues to grow. It’s essential for families to understand what percentage do financial advisors make and how this impacts their financial journey. Additionally, some firms offer compensation for new professionals, providing insight into the operational models within the advisory landscape.
Together, we can navigate this journey, ensuring that you have the support and guidance necessary to achieve your family’s financial goals.

Explore Percentage of Assets Under Management (AUM)
The percentage of Assets Under Management (AUM) serves as a widely accepted compensation structure for financial advisors, leading to the inquiry of what percentage do financial advisors make, as charges are determined based on the total assets overseen for a customer. Typically, these fees range from 0.25% to 2% annually, leading to the inquiry of what percentage do financial advisors make, influenced by factors such as portfolio size and the complexity of services offered. Imagine if you had $1 million in assets—you might incur a fee of 1%, translating to an annual cost of $10,000. This arrangement aligns your advisor’s motivations with your wealth development, as their earnings rise alongside your portfolio’s value.
However, it’s important to understand that this model is not without its challenges. Possible conflicts of interest might arise if advisors focus solely on asset growth instead of comprehensive planning, potentially overlooking other essential elements of your financial well-being. Recent statistics indicate that Goldman Sachs’ asset management segment generated $13.9 billion in net revenue in 2023, highlighting the scale and relevance of the industry.
At Bright Advisers, we’re here for you. We are dedicated to reducing fund fees, ensuring that our clients—especially young families—can access wealth management services without the burden of high expenses. Our customized wealth management services empower individuals like Emily and Mark, who have successfully navigated their financial journeys with our support. By focusing on personalized planning and tax optimization, we help families achieve financial freedom and make informed decisions about their futures.
The wealth management sector continues to rely significantly on AUM fee frameworks, with many consultants adapting their strategies to meet the diverse needs of clients. As Julie Pinkerton, an editor, observes, “Human advisors are continuously innovating to offer more choices for individuals with changing needs.” This innovation is particularly significant as the introduction of AI-driven advice and robo-advisory services transforms access to financial guidance. Yet, the need for tailored human support remains, especially for individuals with complex financial situations.
As the advisory landscape evolves, understanding the implications of AUM fees is crucial for you as a client. Advisors are increasingly aware of the need to innovate and provide customized solutions that address your unique financial objectives, ensuring that the AUM model stays relevant and effective in delivering value. Furthermore, the growing enthusiasm for ESG investments among Gen Z (80%) and Millennials (63%) suggests that professionals may need to align their services with these preferences to better assist younger individuals. Together, we can navigate this journey toward financial security and peace of mind.

Examine Alternative Fee Structures: Flat Fees, Hourly Rates, and Commissions
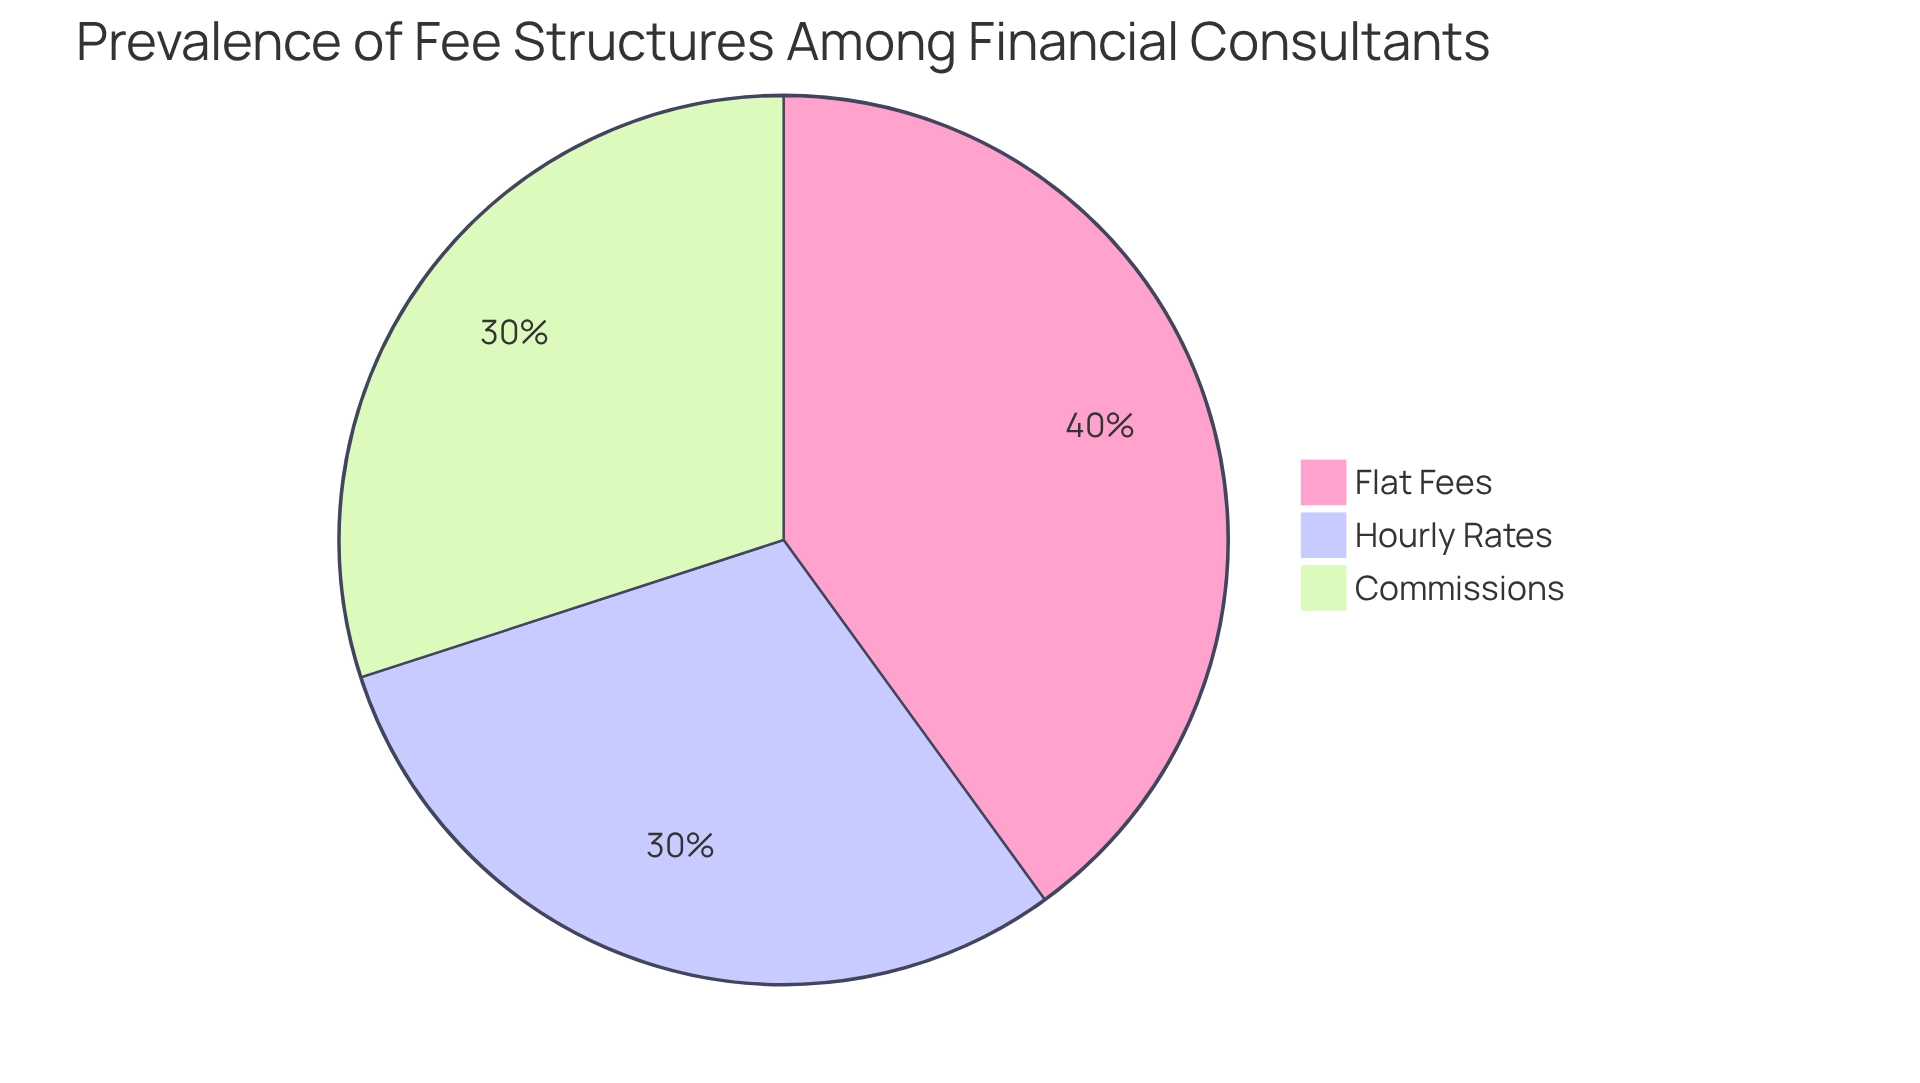
Financial consultants often utilize a variety of pricing structures that go beyond the traditional Assets Under Management (AUM) charges. These include flat fees, hourly rates, and commissions, each offering unique benefits tailored to your needs.
Imagine having a clear understanding of your expenses. Fixed charges provide a consistent cost for specific services, such as comprehensive financial planning, typically valued at around $2,500. Research shows that flat fees can range from $1,500 to $3,000 for similar services, allowing you to know upfront what you’ll pay—no surprises here! On the other hand, hourly rates usually fall between $200 and $400, enabling you to pay only for the time spent addressing your financial needs. This can be especially helpful for those who seek occasional advice rather than ongoing management.
Consider what percentage do financial advisors make in terms of how commission-based consultants earn their revenue. They do so through the sale of investment products, with commissions generally ranging from 3% to 6% of the investment amount. In 2025, we expect average commission rates for financial products sold by consultants to remain within this range. While this model can encourage consultants to recommend specific products, it may also lead to potential conflicts of interest. It’s essential for you to understand these implications. As Nicole Symon points out, “Advisors who charge for their services based on AUM may not accept individuals with balances below a specified amount like $250,000,” highlighting the limitations of this pricing model for some families.
Research indicates that AUM charges for wealth managers typically vary from 0.25% to 2%, which raises the question of what percentage do financial advisors make, with many traditional consultants imposing a baseline of 1%. Robo-advisors often charge an AUM fee of 0.25% to 0.50%, which translates to $125 to $250 annually on a $50,000 account balance. Understanding these charges is crucial for ensuring alignment with your financial goals and making informed choices when selecting an advisor, particularly regarding what percentage do financial advisors make.
As the financial landscape evolves, alternative fee structures are becoming increasingly popular. For instance, flat charges and hourly rates are gaining traction as families seek clarity and affordability in their budgeting. Bright Advisers’ commitment to minimal fund fees enhances accessibility to wealth management, allowing families to focus on their financial futures without the stress of excessive costs. Consultants who embrace these models can cater to a broader range of clients, including those with lower asset balances who may not meet the minimum requirements set by traditional AUM-based consultants. Additionally, online consultants are available for those who find it challenging to locate local specialists, offering services regardless of geographical constraints.
Ultimately, it’s important for you to carefully evaluate which fee arrangement aligns best with your financial goals and preferences. Together, we can navigate this journey and find the right support for your family’s financial well-being.
Assess the Impact of Fee Structures on Financial Planning Choices
Choosing the right fee arrangement is essential for influencing your financial planning choices and overall satisfaction with your advisor. Imagine feeling pressured to maintain higher asset levels just because you’re paying assets under management (AUM) fees. This pressure can lead to unnecessary risks in your investment strategies. Fortunately, fiduciary advisors like those at Lifeworks are here to help you grow your wealth, making their services effectively self-funding. Lifeworks offers a standard investment management charge of 0.80%, payable monthly in advance based on the market value of your portfolio. You can conveniently pay this fee via ACH payment, credit card, or have it deducted from your account by the custodian. On the other hand, if you opt for flat fees, you might find that you appreciate more extensive planning services without the stress of prioritizing asset growth over sound financial decisions.
Understanding the nuances of fee arrangements is crucial for evaluating the true cost of advisory services and determining what percentage do financial advisors make to ensure you receive value for your investment. For instance, research shows that someone with a $2,000,000 portfolio would pay an annual fee of $20,000, prompting the question of what percentage do financial advisors make when an AUM advisor charges 1%. This highlights the significant financial implications of these models. Lifeworks also provides a wrap fee program, where the advisory fee includes specific brokerage and other expenses, potentially offering you a more streamlined cost structure. Additionally, hybrid pricing models that combine flat fees for planning services with AUM-based fees for investment management can create a balanced approach, allowing professionals to deliver comprehensive service without compromising your interests.
Moreover, transparency in fee structures builds trust between you and your advisor. Lifeworks prioritizes clear communication about costs, which enhances your satisfaction and decision-making. Engaging in open conversations about compensation models enables you to align your financial goals with the services provided. As Andrea Coombes wisely notes, “If you’re after basic investment management of a relatively small account, a flat fee of $2,000 a year is likely too much.” This perspective underscores the importance of selecting the right fee structure to ensure a solid financial foundation and a positive advisor-client relationship.
Together, we can navigate this journey, ensuring that your financial planning aligns with your family’s values and aspirations.

Conclusion
Navigating the various financial advisor compensation models is essential for clients, especially young families, as they seek to align their financial planning with their long-term goals. Imagine if you could confidently choose a financial path that truly supports your family’s future. This article highlights three primary compensation structures: commission-based, fee-only, and fee-based models. Each offers distinct advantages and potential conflicts of interest that can significantly impact the advisor-client relationship. By understanding these models, you can make informed decisions that enhance your financial journey.
The growing trend toward fee-only advisors emphasizes transparency and a commitment to clients’ best interests. This shift is particularly beneficial for individuals who want to ensure that their advisors prioritize comprehensive planning over product sales. It’s important to understand that while the percentage of Assets Under Management (AUM) model is widely used, it also presents challenges, including the risk of advisors focusing solely on asset growth at the expense of your broader financial health.
Moreover, alternative fee structures like flat fees and hourly rates are gaining traction, offering clients more predictable costs and flexibility in their financial planning. As the financial landscape evolves, the importance of selecting a fee structure that aligns with your personal financial objectives becomes increasingly clear. Clear communication about fees fosters trust, enabling you to engage more openly with your advisors and make sound financial decisions.
Ultimately, understanding the implications of various compensation models empowers you to choose advisors who truly align with your financial goals. Together, we can navigate this journey. As the demand for transparency and effective advisory services grows, prioritizing your understanding of how advisors are compensated is key to ensuring a supportive and successful financial journey for you and your family.
Frequently Asked Questions
What are the main compensation models for financial advisors?
The primary compensation models for financial advisors include commission-based, fee-only, and fee-based models.
How do commission-based financial advisors earn their income?
Commission-based financial advisors earn income through the sale of investment products, which can sometimes create conflicts of interest since their earnings are tied to the products they recommend.
What are the advantages of working with fee-only financial advisors?
Fee-only financial advisors bill clients directly for their services, fostering transparency and aligning their interests with those of the clients, thus minimizing conflicts and building trust.
What is the fee-based compensation model?
Fee-based consultants operate under a hybrid model where they earn both fees from clients and commissions from product sales, providing flexibility but potentially introducing some conflicts of interest.
What trends are emerging in the wealth management landscape as of 2025?
More consultants are embracing fee-only models due to a growing demand for transparency and trust, with about 60% of monetary consultants having transitioned to fee-only or fee-based arrangements.
Why is it important for families to understand financial advisor compensation models?
Understanding these compensation models is vital for families as it affects the advisor-client relationship, the services offered, and how the advisor prioritizes the clients’ financial goals.
What percentage of individuals typically engage a financial consultant after a significant life event?
Statistics show that 60% of individuals engage a financial consultant after experiencing a significant life event.
What is the projected market value for consulting services by 2025?
The market for consulting services is projected to reach $218.96 billion by 2025, indicating a growing demand for clear and effective financial guidance.
List of Sources
- Define Financial Advisor Compensation Models
- 30+ Financial Advisor Statistics (https://bizplanr.ai/blog/financial-advisor-statistics)
- Salary & Stats (https://cfp.net/why-cfp-certification/financial-planner-salary-and-stats)
- Top 50 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- Explore Percentage of Assets Under Management (AUM)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- What to Know About Financial Advisor Fees & Costs (https://money.usnews.com/financial-advisors/articles/what-to-know-about-financial-advisor-fees-and-costs)
- Examine Alternative Fee Structures: Flat Fees, Hourly Rates, and Commissions
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Financial Advisor Fees and Costs (https://money.com/financial-advisor-fees-and-costs)
- How Much Does a Financial Advisor Cost? (https://smartasset.com/financial-advisor/financial-advisor-cost)
- How Much Do Financial Advisors Charge? Your Updated Guide for 2025 (https://moneylogue.com/blog/how-much-do-financial-advisors-charge-your-updated-guide-for-2025)
- Assess the Impact of Fee Structures on Financial Planning Choices
- What Are the Benefits of a Fee-Based Financial Advisor? (https://aldeninvestmentgroup.com/blog/benefits-of-a-fee-based-financial-advisor)
- How Much Does a Financial Advisor Cost in 2025? – NerdWallet (https://nerdwallet.com/article/investing/how-much-does-a-financial-advisor-cost)
- Financial Advisor Fee Structures: Comparing Flat Fee and AUM (https://advisorhub.com/resources/financial-advisor-fee-structures-comparing-flat-fee-and-aum)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading