

Key Highlights:
- Inheriting a 401(k) involves specific rules varying by beneficiary relationship and plan terms.
- Only designated beneficiaries, such as spouses and children, can inherit a 401(k).
- Non-spouse beneficiaries must adhere to the 10-year rule, requiring full distribution within ten years of the account holder’s death.
- Withdrawals from an inherited 401(k) are taxed as ordinary income, impacting overall tax liabilities.
- Spouse beneficiaries can roll over the inherited 401(k) into an IRA, keep it as a beneficiary account, or take a lump-sum distribution.
- Non-spouse beneficiaries can transfer funds into an inherited IRA or take a lump-sum distribution, with careful planning needed to avoid penalties.
- Consulting a financial advisor can help beneficiaries navigate their options and create a personalised strategy.
- Understanding tax implications, including the potential impact of large withdrawals, is crucial for financial planning.
- Inherited Roth 401(k) distributions are tax-free, but still subject to the 10-year distribution requirement.
- Tax planning strategies, such as spreading out withdrawals, can help minimise tax burdens.
Introduction
Inheriting a 401(k) can feel overwhelming, especially during such a challenging time of loss and transition. It’s essential to grasp the nuances of this financial asset, as the rules surrounding inherited 401(k)s can differ greatly depending on your relationship to the deceased and the specific details of the plan.
Imagine if you could navigate this process with confidence, knowing you’re making the best choices for your family’s future. This article is here to guide you through the essential steps and considerations for managing an inherited 401(k). We’ll explore your options as a beneficiary and help you understand the tax implications involved.
How can you ensure that you’re making informed decisions while also protecting your family’s financial well-being amidst the complexities of inheritance? Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Understand Inherited 401(k) Basics
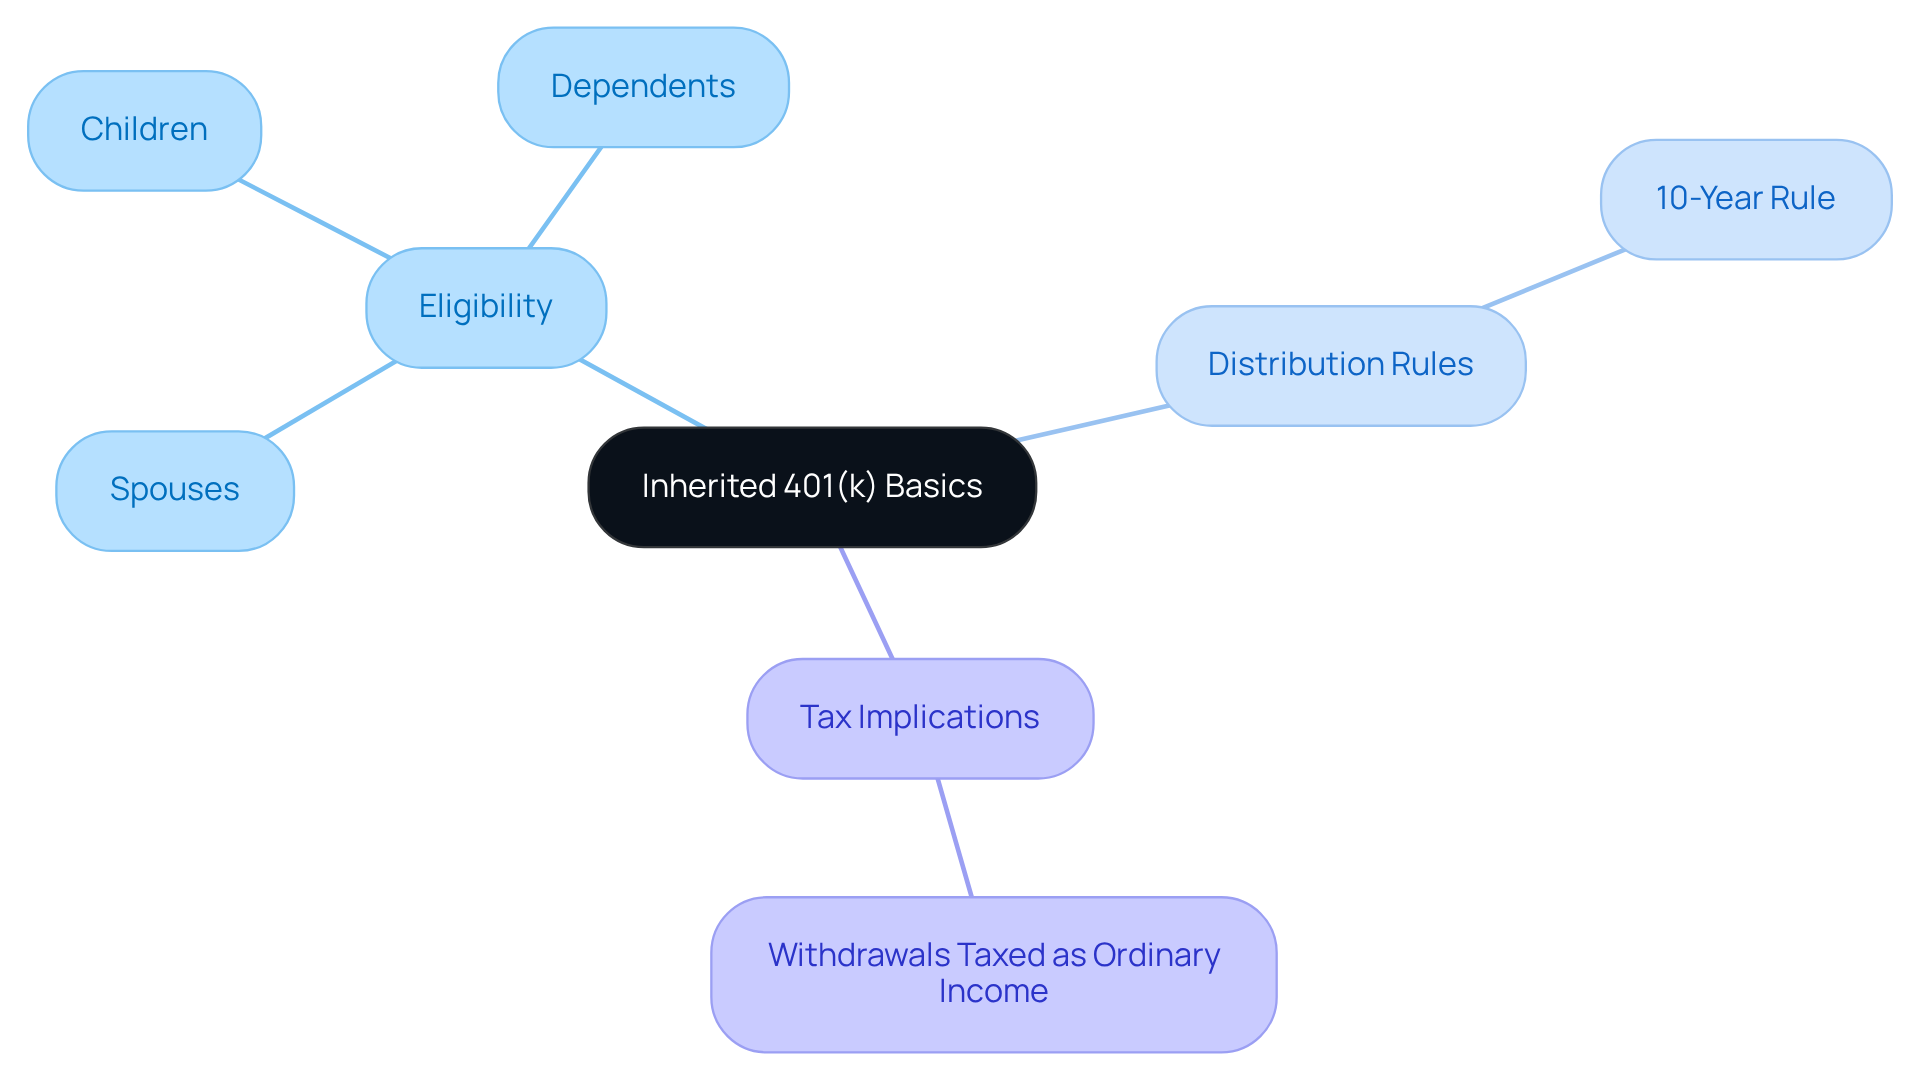
Inheriting a 401(k) can feel overwhelming, especially during such a sensitive time. A bequeathed 401(k) is a retirement plan you receive as a beneficiary after the account holder’s passing. It is crucial to understand what to do with inherited 401k, as the rules surrounding this inheritance can vary based on your relationship with the deceased and the specific terms of the plan. Here are some key points to consider:
- Eligibility: Only designated beneficiaries can inherit a 401(k). This typically includes spouses, children, and other .
- Distribution Rules: It’s important to know that beneficiaries must follow specific distribution rules. For non-spouse beneficiaries, this often means adhering to the 10-year rule, which requires the account to be fully distributed within ten years of the account holder’s death.
- Tax Implications: Withdrawals from an inherited 401(k) are generally taxed as ordinary income. This can significantly impact your overall tax situation, so it’s wise to plan accordingly.
Familiarizing yourself with these basics will empower you to make informed decisions regarding what to do with inherited 401k as you navigate the inheritance process. Remember, you’re not alone in this journey; we’re here for you, ready to help you understand your options and support your family’s financial future.
Explore Beneficiary Options: Spouse vs. Non-Spouse
When it comes to what to do with inherited 401k, your choices can feel overwhelming, especially if you’re trying to make the best decisions for your family. Understanding what to do with inherited 401k options available to you is crucial, whether you are a spouse or a non-spouse beneficiary.
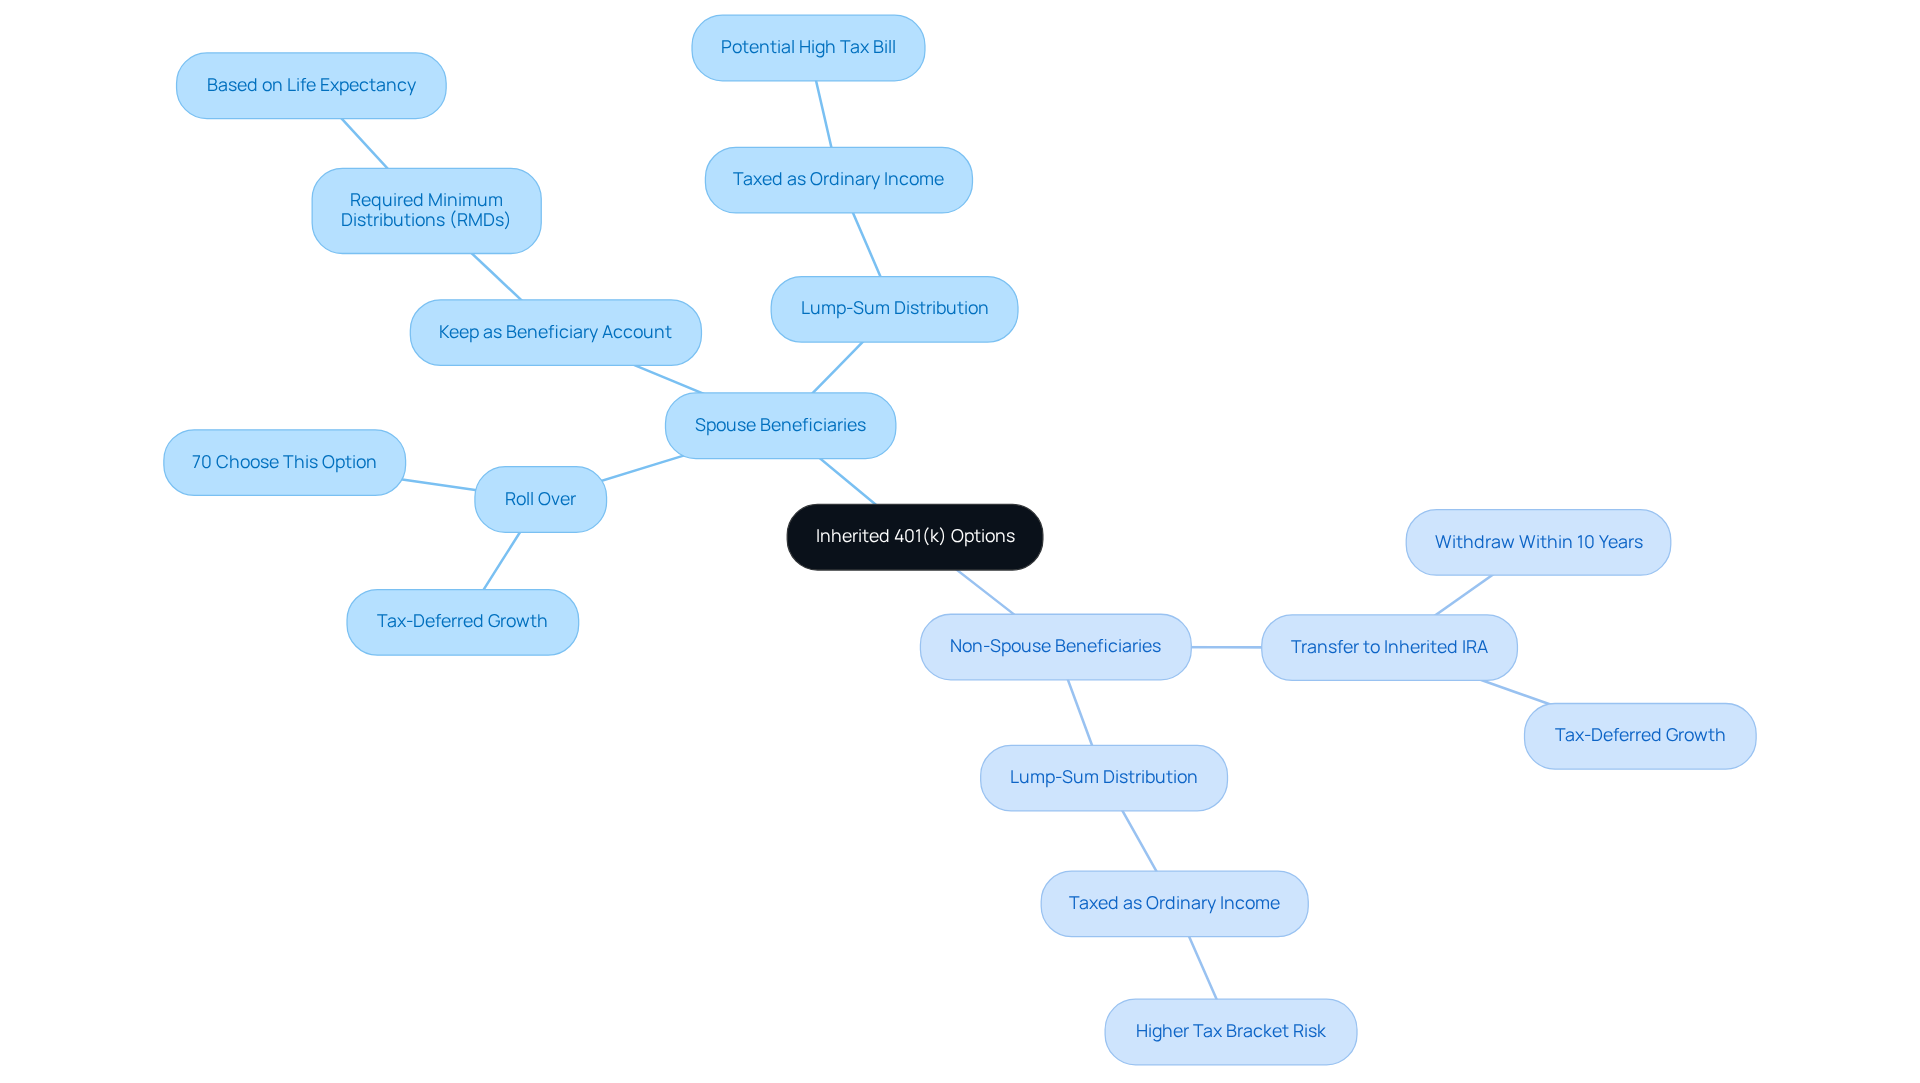
For Spouse Beneficiaries: As a spouse, you have several paths to consider:
- Roll Over: You can roll the inherited 401(k) into your own IRA. This allows for continued tax-deferred growth, which many spouses find appealing. In fact, around 70% of spouses choose this route to maximize their investment potential.
- Keep It as a Beneficiary Account: Another option is to leave the funds in the existing 401(k) plan, retitled as a beneficiary account. This way, you can take required minimum distributions (RMDs) based on your life expectancy, providing a steady income stream.
- Take a Lump-Sum Distribution: While you can withdraw the entire amount, keep in mind that this will be taxed as ordinary income, which could lead to a hefty tax bill.
For Non-Spouse Beneficiaries: If you’re a non-spouse, your options are a bit more limited:
- Transfer to an Inherited IRA: You can transfer the funds into an inherited IRA, but you must withdraw the entire balance within ten years. This option allows for continued tax-deferred growth, but it requires careful planning to avoid penalties. Remember, understanding the regulations for inherited 401(k)s can help you steer clear of unexpected taxes and penalties.
- Take a Lump-Sum Distribution: Similar to spouses, you can withdraw the entire amount, but be cautious. This could push you into a higher tax bracket, making it a less favorable choice unless you need immediate access to funds.
Understanding what to do with inherited 401k options is vital for making that align with your family’s long-term goals. And as you look ahead, it’s important to stay informed about upcoming changes in 2025 regarding 401(k) beneficiary regulations, as these may further impact your choices.
Remember, we’re here for you. Together, we can navigate this journey and ensure that your family’s financial future is secure.
Implement Strategies for Managing Your Inherited 401(k)
Managing what to do with inherited 401k can feel overwhelming, but you’re not alone. Here are some caring strategies to help you navigate this journey:
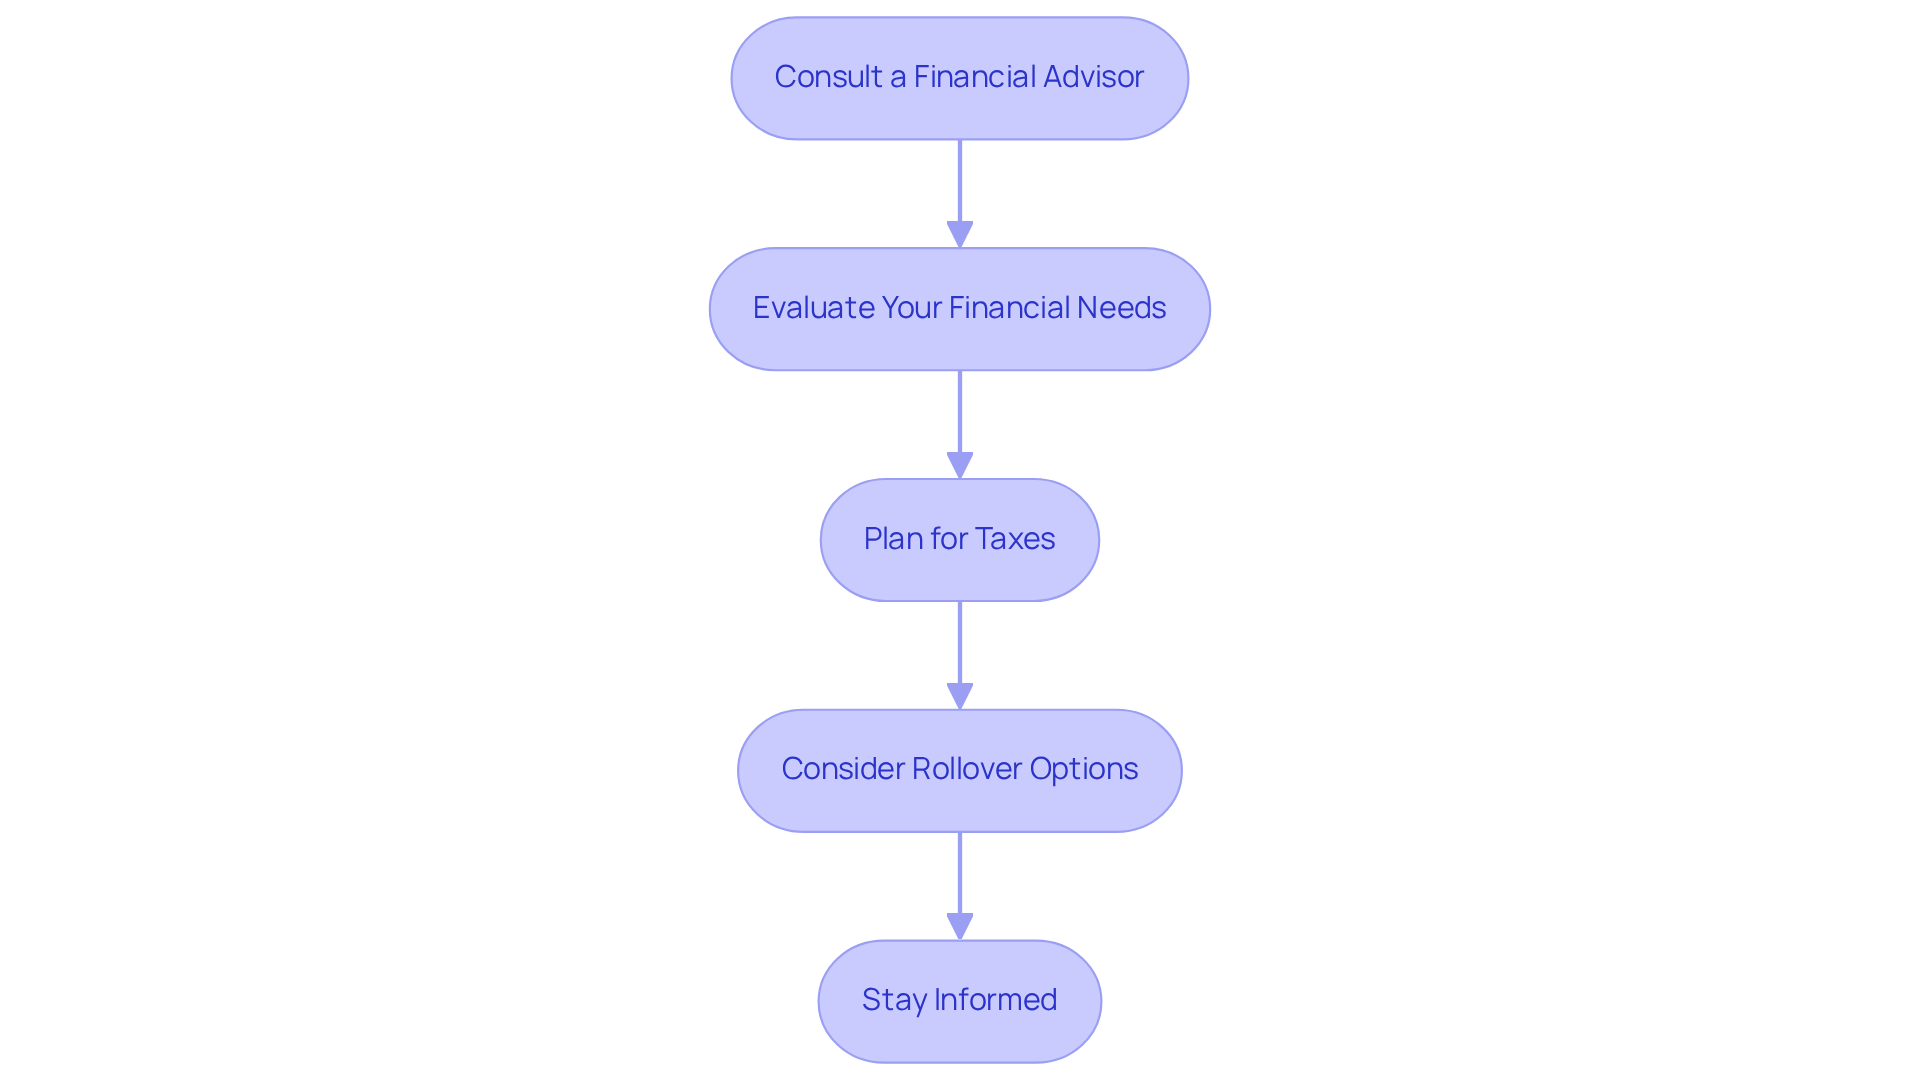
- Consult a Financial Advisor: Imagine having a trusted guide by your side. Engaging with a financial planner who can advise on what to do with inherited 401k funds can make all the difference. Their expertise will help you explore your options and create a personalized strategy that aligns with your family’s financial goals.
- Evaluate Your Financial Needs: Take a moment to assess your current financial situation and future aspirations. Understanding your needs will empower you to determine what to do with inherited 401k, whether to take distributions now or roll over the account for . It’s all about what works best for you and your family.
- Plan for Taxes: It’s important to understand how your choices can impact your taxes. Opting for a lump-sum distribution might significantly affect your taxable income. Planning ahead can help you make informed decisions that protect your family’s financial future.
- Consider what to do with inherited 401k: If you decide to roll over your inherited 401(k) into an IRA, explore investment options that align with your risk tolerance and long-term goals. A balanced portfolio can help maximize growth while preserving your inheritance for your loved ones.
- Stay Informed: Regularly updating yourself on changes in tax laws or regulations can be beneficial. Being proactive allows you to make timely decisions that optimize your financial outcomes. Remember, we’re here for you, ready to support you every step of the way.
Consider Tax Implications and Planning
Tax implications can feel overwhelming, especially when figuring out what to do with inherited 401k. Let’s break it down together, so you can make informed decisions for your family’s future.
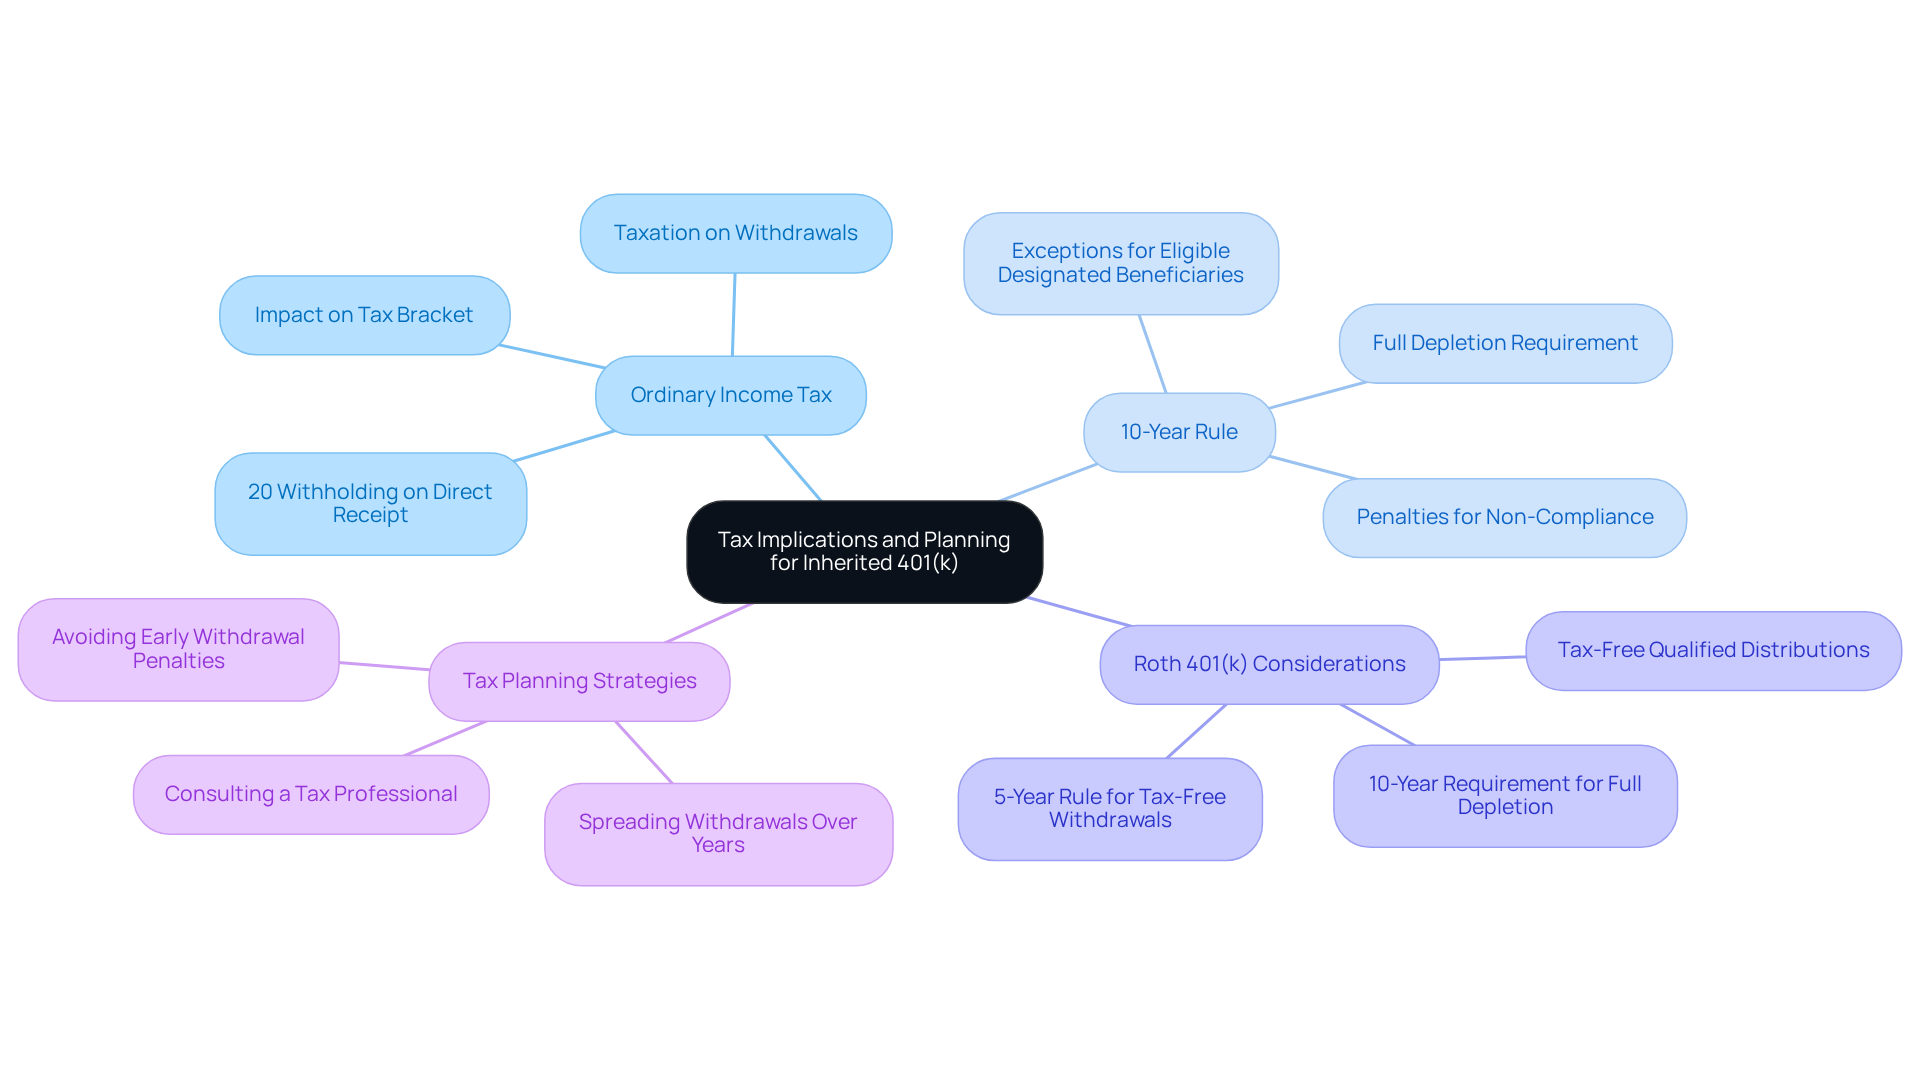
Ordinary Income Tax: When you withdraw from an inherited 401(k), it’s taxed as ordinary income. This means that the amount you take out adds to your taxable income for the year. If you withdraw a large sum all at once, it could significantly impact your overall tax liability. It’s important to think about how this might affect your family’s finances.
10-Year Rule: If you’re a non-spouse beneficiary, you’ll need to deplete the entire fund within ten years. This can lead to hefty tax bills if you’re not careful about how much you withdraw each year. The SECURE Act of 2019 changed the rules, ending the ‘stretch IRA’ and introducing this 10-year requirement. Thoughtfully is essential for understanding what to do with inherited 401k to avoid surprises down the road.
Roth 401(k) Considerations: Inheriting a Roth 401(k) comes with its own set of benefits. Qualified distributions are tax-free, which is a significant advantage for your family. However, you still need to follow the distribution rules, including that 10-year requirement for full depletion of funds. This can be a great way to support your family’s financial goals without the added tax burden.
Tax Planning Strategies: Consider spreading out your withdrawals over several years. This can help minimize your tax burden and keep you in a lower tax bracket. Plus, distributions from inherited 401(k) plans after the account owner’s death are exempt from the 10% early withdrawal penalty. Consulting with a tax professional can provide personalized strategies tailored to your unique situation.
By understanding these tax implications and planning ahead, particularly about what to do with inherited 401k, you can navigate this journey with confidence. Remember, we’re here for you, ready to support you in making the best choices for your family.
Conclusion
Navigating the complexities of an inherited 401(k) can feel overwhelming, especially during emotionally challenging times. It’s crucial to understand the options available, whether you’re a spouse or a non-spouse beneficiary. This knowledge empowers you to make informed financial decisions that align with your family’s future goals. By familiarizing yourself with the rules, distribution options, and tax implications, you can take control of your financial destiny and ensure that the inheritance serves its intended purpose.
Imagine knowing exactly what your options are. Key insights highlight the importance of understanding your eligibility and the various paths available for both spouses and non-spouses. Spouses enjoy the flexibility to roll over their inherited 401(k) into an IRA or take distributions, while non-spouses must adhere to the 10-year rule for withdrawals. Engaging with a financial advisor and evaluating your personal financial needs can empower you to make strategic choices that maximize the benefits of your inherited 401(k).
Ultimately, managing an inherited 401(k) is not just about financial gains; it’s also about honoring the legacy of your loved one. By staying informed and proactive, you can navigate the evolving landscape of inherited 401(k) regulations and strategies, especially with upcoming changes in 2025. Taking these steps not only secures your family’s financial future but also ensures that the inheritance is used wisely and effectively for generations to come. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is an inherited 401(k)?
An inherited 401(k) is a retirement plan that you receive as a beneficiary after the account holder’s passing.
Who is eligible to inherit a 401(k)?
Only designated beneficiaries can inherit a 401(k), which typically includes spouses, children, and other dependents who relied on the account holder.
What are the distribution rules for inherited 401(k)s?
Beneficiaries must follow specific distribution rules. For non-spouse beneficiaries, this often means adhering to the 10-year rule, which requires the account to be fully distributed within ten years of the account holder’s death.
How are withdrawals from an inherited 401(k) taxed?
Withdrawals from an inherited 401(k) are generally taxed as ordinary income, which can significantly impact your overall tax situation.
Why is it important to understand inherited 401(k) rules?
Understanding the rules surrounding inherited 401(k)s is crucial for making informed decisions about the inheritance process and managing your financial future effectively.
List of Sources
- Explore Beneficiary Options: Spouse vs. Non-Spouse
- Inherited 401(k): Rules and Tax Information | SoFi (https://sofi.com/learn/content/inherited-401k)
- How to Make the Most of Inherited 401(k) Funds (https://goodlifefamhc.com/blog/how-to-make-the-most-of-inherited-401k-funds)
- Avoid Making Costly Moves With A Non-Spouse Inherited 401(k) (https://forbes.com/sites/jbrewer/2025/01/14/avoid-making-costly-moves-with-a-non-spouse-inherited-401k)
- Inherited 401(k) Rules: What Beneficiaries Need To Know (https://bankrate.com/retirement/inherited-401k-rules)
- Inherited 401(k): What to know if you’re a 401(k) beneficiary | Fidelity (https://fidelity.com/learning-center/smart-money/inherited-401k-rules)
- Implement Strategies for Managing Your Inherited 401(k)
- Financial Advisor for Inheritance: Services and Examples (https://smartasset.com/financial-advisor/financial-advisor-for-inheritance-services-and-examples)
- Warren Buffett on Estate Planning | Trust & Will (https://trustandwill.com/learn/warren-buffet-estate-planning-lessons)
- This is the ‘biggest mistake’ you can make with your IRA, attorney says (https://cnbc.com/2025/11/09/biggest-ira-mistake.html)
- Here’s how to handle the complicated rules for an inherited 401(k) or IRA (https://cnbc.com/2021/04/11/how-to-handle-complicated-rules-for-inherited-401k-or-ira.html)
- Consider Tax Implications and Planning
- 401(k) Inheritance Tax Rules for Estate Planning (https://smartasset.com/taxes/401k-inheritance-tax)
- How To Avoid Taxes on 401k Inheritance: Key Options Explained (https://titanwealthinternational.com/learn/how-to-avoid-taxes-on-401k-inheritance)
- Inherited 401(k) Rules: What Beneficiaries Need To Know (https://bankrate.com/retirement/inherited-401k-rules)
- Tax on an Inherited 401k: A Complete Guide (https://commonsllc.com/insights/tax-on-inherited-401-k)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading