

Key Highlights
- Financial planners earn commissions based on the products they sell, which can vary by type, affecting the advice families receive.
- Commission structures can lead to conflicts of interest, where advisors may recommend higher-commission products over better-suited options.
- Recent data indicates advisor fees can range from 9-10% to 32-35% over four years, highlighting the need for transparent fee structures.
- The financial planning profession has evolved towards transparency, with fee-only and fee-based models prioritising clients’ needs over sales incentives.
- Bright Advisers emphasises fiduciary duty, offering personalised wealth management without hidden fees or conflicts of interest.
- Young families should be cautious of commission-based advisors, as their interests may not align with those of the families, leading to poor financial decisions.
- By 2025, a significant majority of advisor earnings are expected to come from clear, asset-based fees, reflecting a shift towards transparency in the industry.
- Choosing fee-only advisors like Bright Advisers can empower families to make informed financial decisions, ensuring a secure future.
Introduction
Imagine feeling uncertain about your family’s financial future because of hidden motives in financial advice. Understanding how financial planner commissions work is essential for young families striving for stability. Commissions can shape the advice you get, sometimes creating conflicts that don’t align with what’s best for your family. As you think about your family’s financial future, you might wonder: how can you make sure your advisor puts your needs first? This article will explore different commission structures and why fee-only advisors might be the best choice for your family’s brighter financial future.
Define Financial Planner Commission
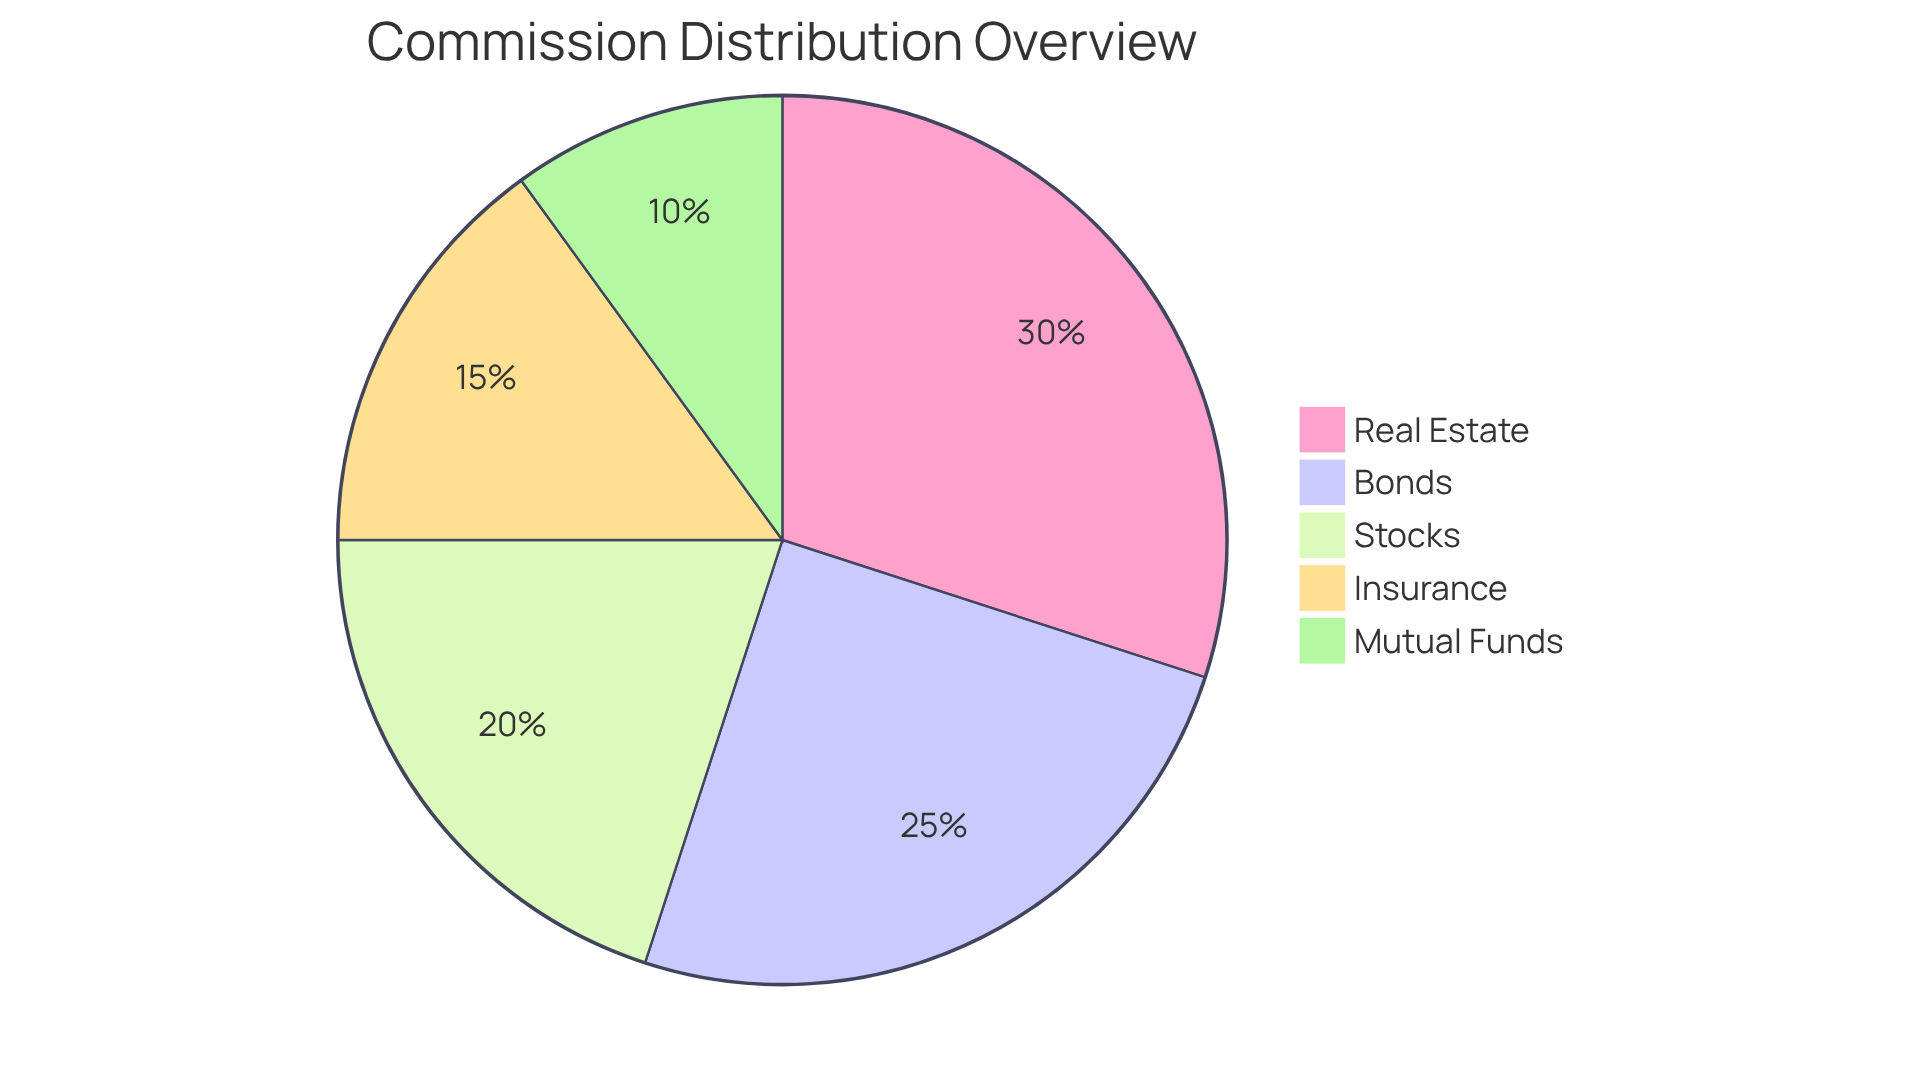
Have you ever wondered how financial planners get paid through financial planner commission and what that means for your family’s future? Financial planners earn a financial planner commission for helping families like yours with financial products and services. These fees can change based on the type of product you choose, such as mutual funds or insurance, and may influence the financial planner commission. Usually, the financial planner commission consists of a percentage of what you invest or a flat fee for each transaction.
Understanding how financial planner commission works is important for families, as it can affect the advice you receive. For example, some advisors might recommend products that provide a higher financial planner commission, which can lead to conflicts of interest. This is especially important for families in Southern California, where understanding finances is key to long-term stability.
Recent data shows that advisor fees can start at 9-10% and rise to 32-35% in just four years. This highlights the need for clear fee structures, such as financial planner commission, to ensure you get unbiased advice. Imagine trusting someone with your family’s financial future, only to find out their recommendations benefit them more than you. Without clarity on fees, families might miss out on the best financial advice, which could be influenced by the financial planner commission.
Understanding these fees can empower you to make informed decisions that truly benefit your family.
Explore the History and Context of Financial Planner Commissions
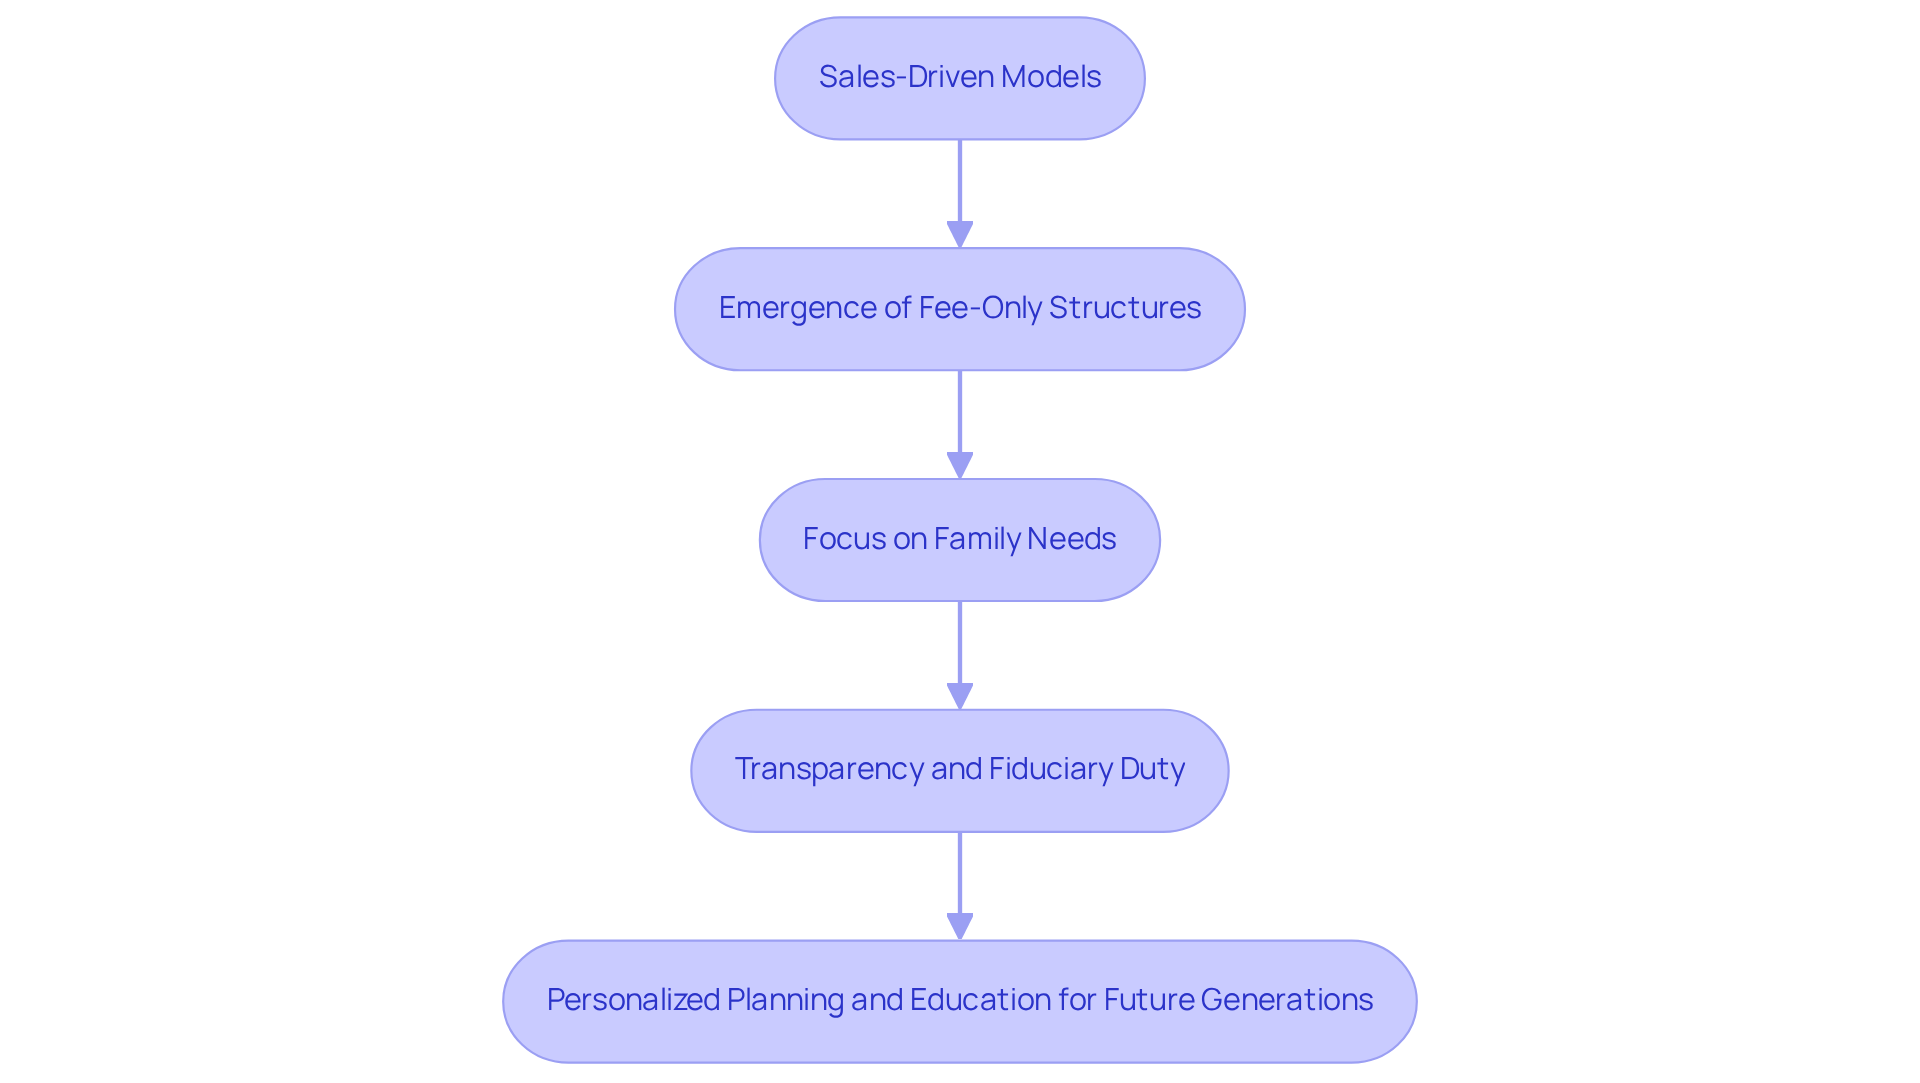
Imagine navigating the complex world of financial planning, where the history of advisor earnings reveals a journey from sales-driven models to a more caring approach focused on your family’s needs. In the past, stockbrokers focused more on making sales than on truly helping their clients. It was a challenging environment for families seeking genuine financial guidance.
As the financial planning profession matured, things began to change. Many advisors are now embracing transparency and a commitment to putting your family’s needs first. The introduction of fee-only and fee-based structures was a significant response to the conflicts of interest that often arose with financial planner commission models.
Companies like Bright Advisers are leading the way by prioritizing the best interests of households over sales incentives. They utilize a liability-driven wealth management system that aligns with your family values. This approach emphasizes personalized monetary planning and investment strategies, while also providing educational resources for your children, preparing them for future wealth.
Understanding this evolution empowers you to choose advisors who genuinely prioritize your family’s financial well-being, ensuring a brighter future for your children. Bright Advisers’ dedication to minimal fund fees improves accessibility for families, allowing you to focus on what truly matters – establishing a secure economic future for your little ones.
As noted by Mark J. Higgins in ‘Investing in U.S. Financial History,’ this evolution reflects a broader commitment to fiduciary duty, underscoring the importance of evaluating the appropriateness of investment costs. Together, we can navigate this journey towards financial security for your family.
Identify Key Characteristics of Financial Planner Commissions
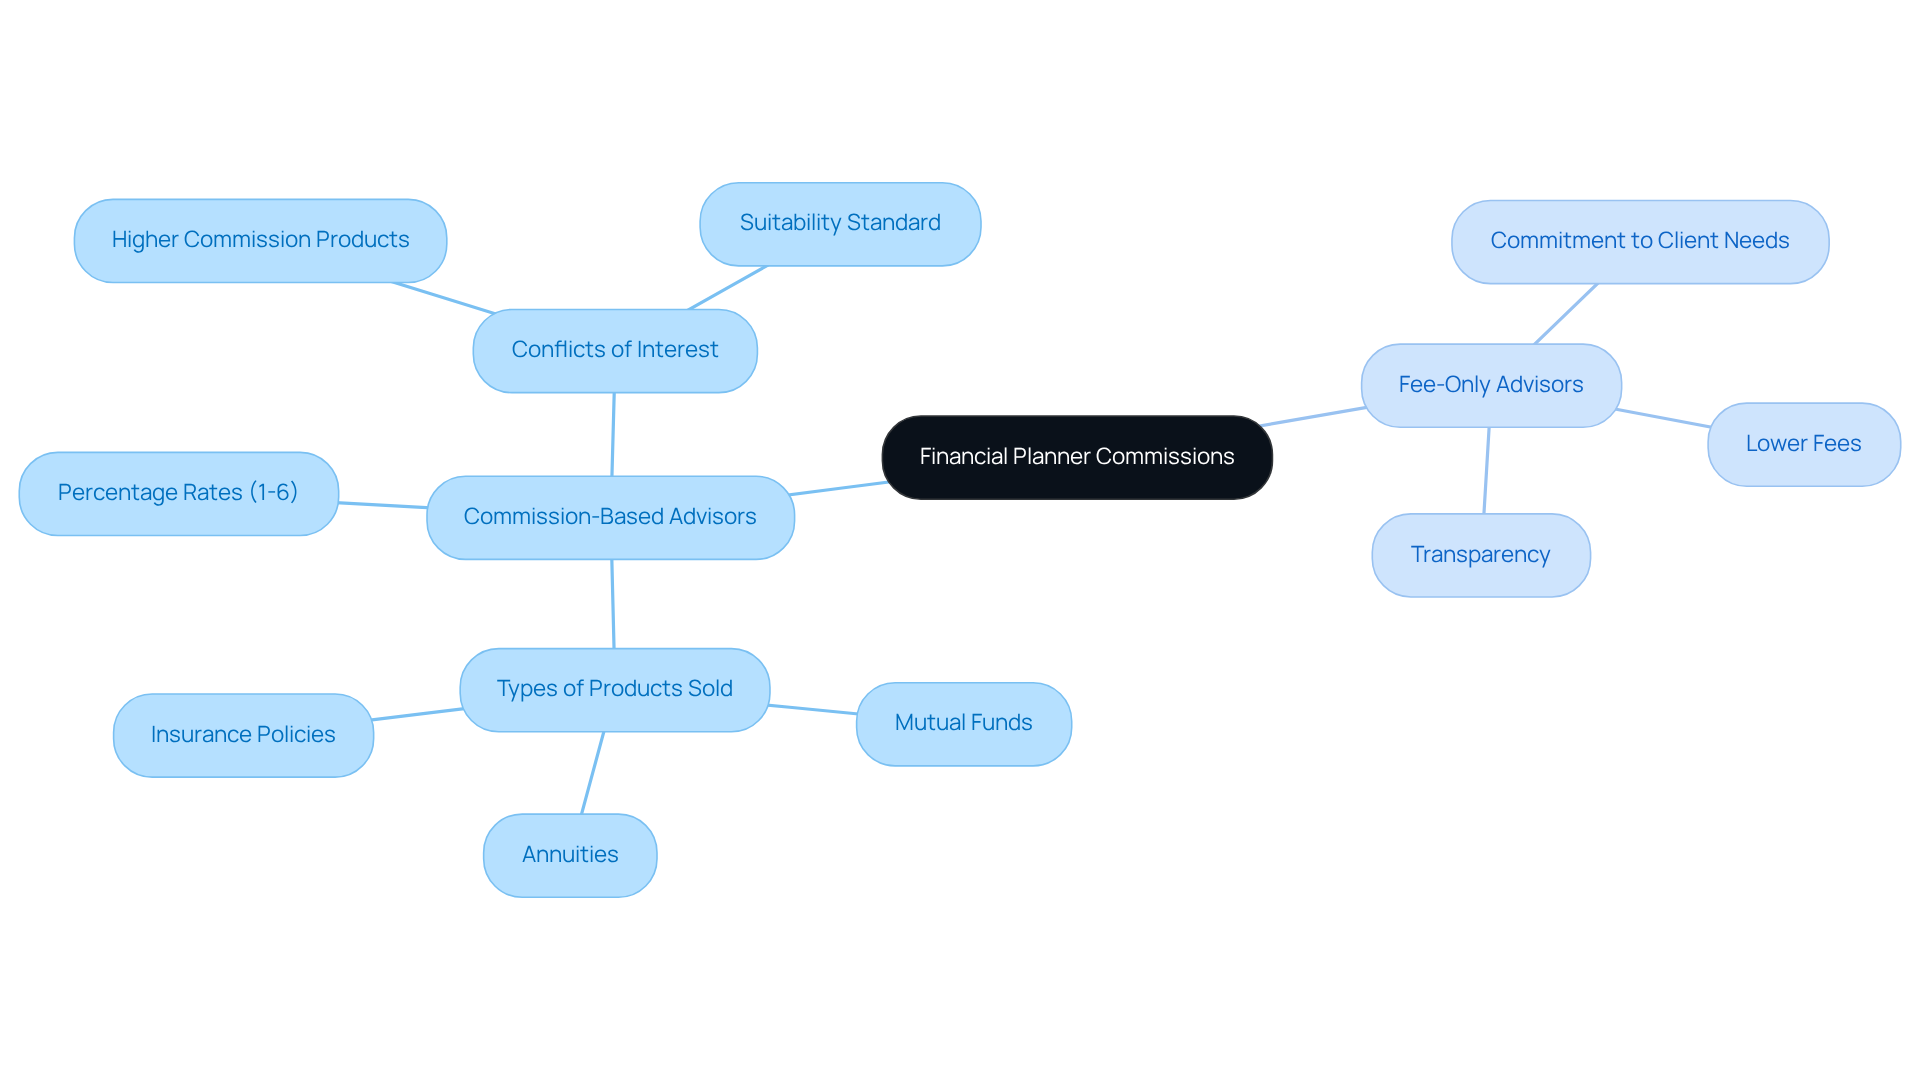
Imagine feeling overwhelmed by financial jargon while trying to secure your family’s future. Key characteristics of financial planner commission include the types of products sold and the percentage rates earned, which can feel confusing. In the coming years, you might see fees between 1% and 6% based on the type of investment. For instance, some consultants work on a financial planner commission, which means they might suggest products that aren’t always the best fit for you, just to earn more money. This can lead to conflicts of interest, especially when products with a higher financial planner commission are pushed over those that truly meet your needs.
On the other hand, fee-only advisors like Bright Advisers are committed to putting your needs first, ensuring you get the best advice without hidden agendas. Understanding these differences is crucial for families like Jay and Emma, who are juggling budgets and trying to ease financial worries. By choosing the right advisor, you can feel confident in your financial decisions and reduce stress for your family.
At Bright Advisers, we focus on keeping fees low, so you can access the wealth management help you need without breaking the bank. This dedication allows families to select consultants who align with their values and financial goals, ultimately improving their economic security. Choosing the right advisor can empower you to make informed decisions that truly benefit your family’s financial well-being.
Understand Why Young Families Should Avoid Financial Planner Commissions
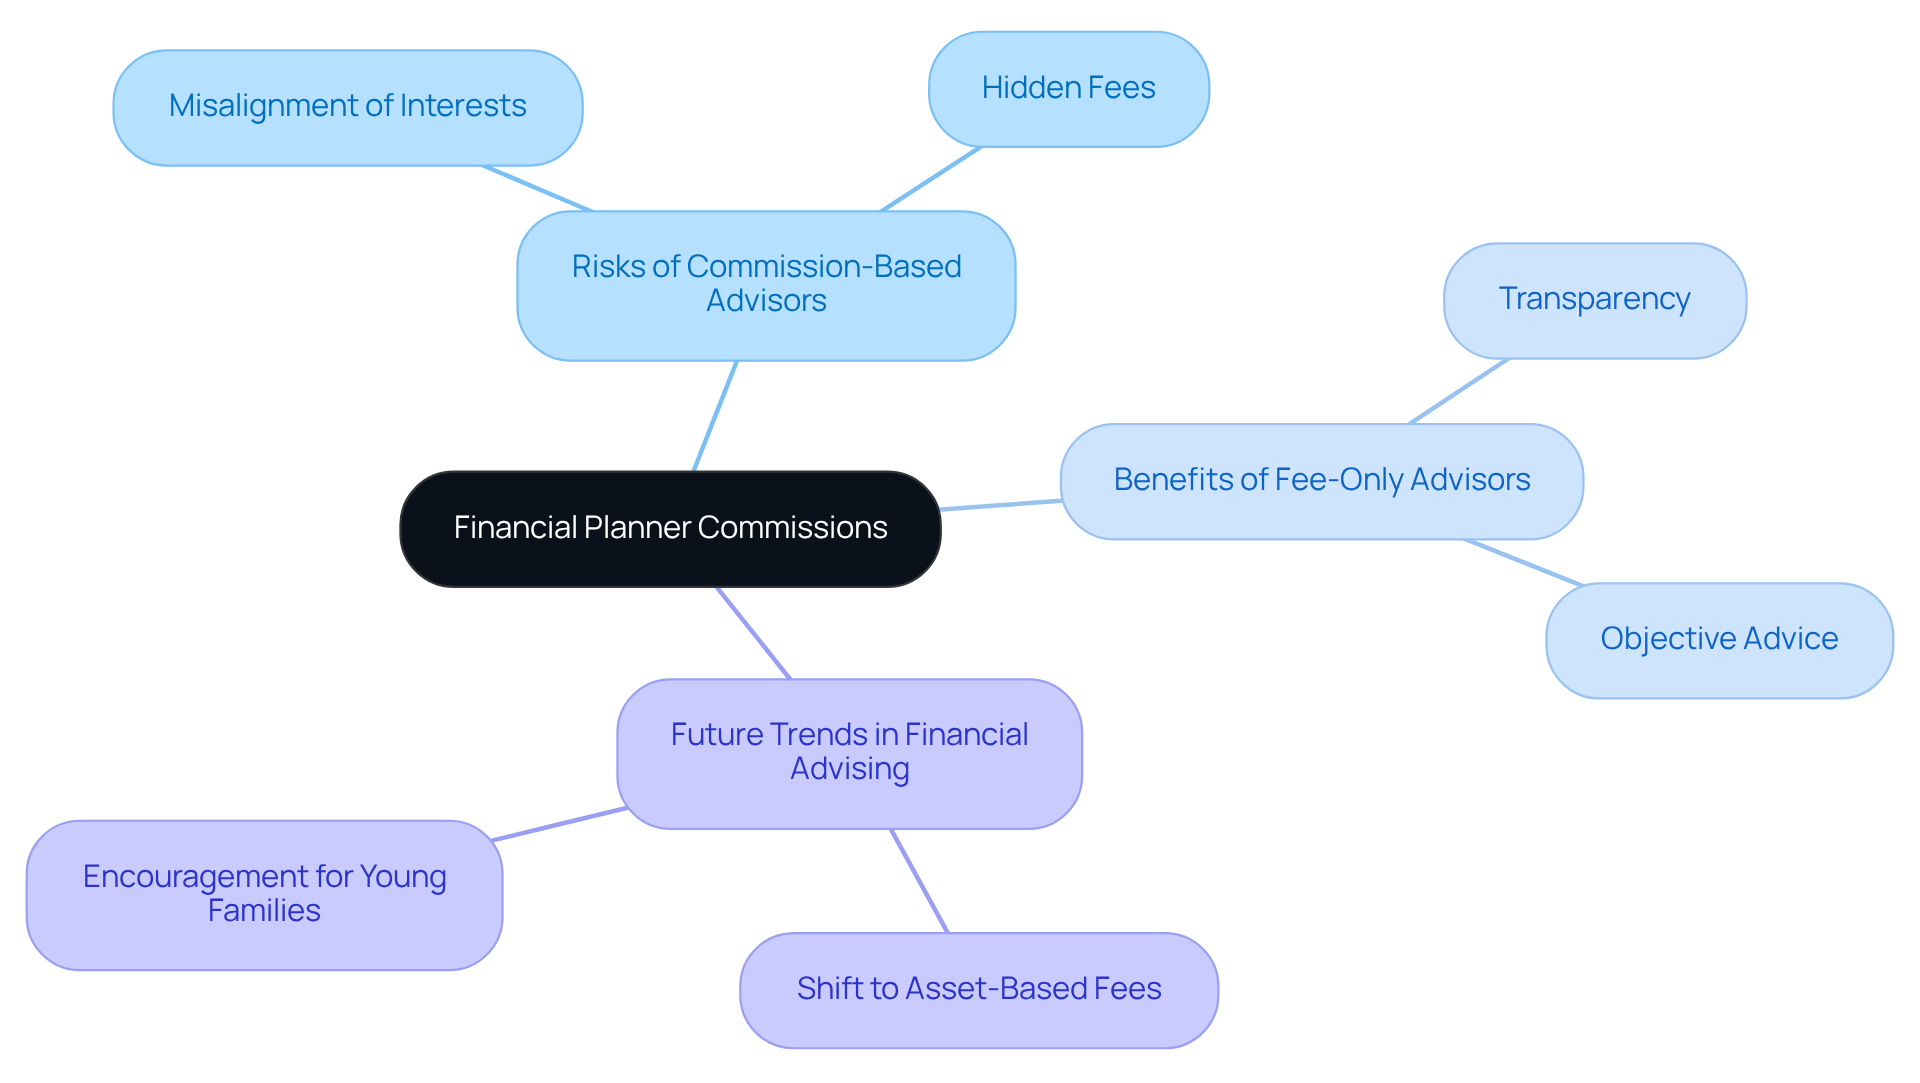
Imagine feeling uncertain about whether your financial advisor truly has your family’s best interests at heart. Young households need to be cautious when selecting financial advisors, especially those who earn a financial planner commission, as their interests may not always align with yours. When this happens, it can lead to financial decisions that don’t truly support your family’s long-term goals.
Plus, commission-based systems often hide extra fees, making it hard to understand what you’re really paying for. By 2025, it’s expected that more than 73% of consultant earnings will come from clear, asset-based fees, showing a move towards transparency in pricing. By selecting fee-only consultants, like those at Bright Advisers, families can ensure their planning is based on transparency and objectivity.
Many families who depend on advice based on financial planner commission find it tough to manage their wealth successfully. This can leave families feeling anxious about their financial future, unsure if they are making the right choices for their children. As the wealth management industry increasingly transitions to fee-based models, young families are encouraged to seek advisors who prioritize their best interests, ensuring a more stable and prosperous financial journey.
By choosing the right advisor, you can pave the way for a brighter financial future for your family, filled with peace of mind and security.
Conclusion
Many families struggle to understand how financial planners are paid, which can lead to uncertainty in their financial decisions. Understanding financial planner commissions is important for young families aiming to secure their financial future. How financial planners are paid can really affect the advice they give, which might create conflicts of interest. By understanding the different ways planners are paid and choosing fee-only advisors like Bright Advisers, families can make sure their financial planning truly reflects their needs, without hidden fees or biases.
We’ve shared important insights about how financial planner commissions have changed, the importance of transparency, and the potential pitfalls of commission-based models. Families learned how to identify the characteristics of various commission structures and why it is essential to choose advisors who prioritize their needs. The shift towards fee-only models reflects a growing commitment to fiduciary duty, ensuring that families receive unbiased advice tailored to their unique circumstances.
Ultimately, your journey to financial security starts with making informed choices together as a family. Choosing a fee-only advisor can transform your financial journey, providing clarity and confidence in your decisions. By prioritizing transparency and the right financial guidance, families can feel more at ease and confidently build wealth for generations to come. For personalized support, families are encouraged to reach out to Bright Advisers at hello@brightadvisers.com or call (714) 987-2967.
Frequently Asked Questions
How do financial planners get paid?
Financial planners earn a financial planner commission for helping families with financial products and services. This commission can be a percentage of the investment or a flat fee for each transaction.
What factors can influence financial planner commissions?
Financial planner commissions can change based on the type of product chosen, such as mutual funds or insurance, which may affect the overall commission structure.
Why is it important to understand financial planner commissions?
Understanding financial planner commissions is crucial because they can influence the advice you receive. Some advisors may recommend products that yield higher commissions, potentially leading to conflicts of interest.
What are the typical ranges for advisor fees?
Recent data indicates that advisor fees can start at 9-10% and rise to 32-35% within four years, emphasizing the need for clear fee structures.
How can unclear fee structures affect families?
Without clarity on fees, families might receive biased advice that benefits the financial planner more than themselves, potentially missing out on the best financial guidance.
What should families in Southern California consider regarding financial planner commissions?
Families in Southern California should be particularly aware of financial planner commissions, as understanding these fees is key to achieving long-term financial stability.
List of Sources
- Define Financial Planner Commission
- Financial advisor industry statistics: key data and trends (https://unbiased.com/pro/discover/trends-insight/financial-advisor-industry-statistics)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- 60+ Financial Advisor Statistics You Need to Know in 2026 (https://upmetrics.co/blog/financial-advisor-statistics)
- Compensation (https://careers.edwardjones.com/career-areas/new-financial-advisor/compensation)
- Explore the History and Context of Financial Planner Commissions
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- A Guide to Financial Advisor Compensation Models (https://smartasset.com/financial-advisor/a-guide-to-financial-advisor-compensation-models)
- Five Quotes from Financial History to Guide Trustees (https://rpc.cfainstitute.org/blogs/enterprising-investor/2024/five-quotes-from-financial-history-to-guide-trustees)
- Wealth Management Compensation Study | FP Transitions (https://fptransitions.com/compensation-study)
- Identify Key Characteristics of Financial Planner Commissions
- Fee Only Vs Commission Based A Comprehensive Guide To Financial Advisor Compensation Structures (https://raymondjames.com/talentfinancialservices/our-perspective/2024/03/01/fee-only-vs-commission-based-a-comprehensive-guide-to-financial-advisor-compensation-structures)
- What Commissions Do Financial Advisors Earn? (https://smartasset.com/financial-advisor/financial-advisor-commissions)
- Commission-Based Advisor | Meaning, Pros, Cons, & Evaluation (https://financestrategists.com/financial-advisor/advisor-types/commission-based-advisor)
- Average Sales Commission Rates by Industry in 2026 (https://everstage.com/sales-commission/average-sales-commission-rates-by-industry)
- Understand Why Young Families Should Avoid Financial Planner Commissions
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Why and how financial advisors move to fee-based ꟾ BlackRock (https://blackrock.com/us/financial-professionals/insights/why-financial-advisors-move-to-fee-based-from-brokerage)
- Your Financial Advisor Has Conflicts of Interest. What Can You Do About It? (https://linkedin.com/pulse/your-financial-advisor-has-conflicts-interest-what-do-meg)
- ‘Fee based’ vs. ‘fee only’ financial planners: There’s a big difference (https://latimes.com/business/story/2022-10-09/fee-based-vs-fee-only-financial-planners-theres-a-big-difference)
- Remedies to Avoid the Subtle Influence of Conflicts of Interest in Financial Planning (https://financialplanningassociation.org/learning/publications/journal/APR23-remedies-avoid-subtle-influence-conflicts-interest-financial-planning-OPEN)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading