

Overview
Understanding the key age milestones for drawing from an Individual Retirement Account (IRA) is essential for your family’s financial well-being. You can start making penalty-free withdrawals at age 59½, which can provide you with much-needed flexibility as you plan for your family’s future. Additionally, it’s important to know that required minimum distributions (RMDs) must begin by April 1 of the year following your 73rd birthday.
Imagine the relief of being well-informed about these rules. Many individuals, however, remain unaware of the implications of failing to take RMDs, which can lead to a significant 25% penalty on the missed amount. We’re here for you to help navigate these complexities and ensure that you feel confident in your financial decisions. Together, we can navigate this journey and secure a brighter future for your family.
Key Highlights:
- IRAs offer tax advantages for retirement savings, with two main types: Traditional and Roth IRAs.
- Withdrawals from IRAs can begin without penalties at age 59½; early withdrawals may incur a 10% penalty plus income taxes.
- Traditional IRA holders must start taking Required Minimum Distributions (RMDs) by April 1 following the year they turn 73.
- Roth IRA contributions can be withdrawn anytime, but earnings are tax-free only if the account is held for at least five years and the holder is at least 59½.
- In 2023, only 31% of households with Traditional IRAs took distributions, indicating a lack of awareness regarding IRA rules.
- Failing to take RMDs can result in a penalty of up to 25% of the missed amount, emphasizing the need for compliance.
- Financial planning is crucial, as 37% of retirees may lack adequate savings, highlighting the importance of assessing financial needs and tax implications.
- Engaging with financial advisors can provide personalized strategies for IRA management and withdrawal planning.
Introduction
Navigating the complexities of Individual Retirement Accounts (IRAs) can feel overwhelming, especially for young parents who are focused on securing their family’s future. However, understanding the fundamental rules and strategies can profoundly impact your long-term financial security. With two primary types of IRAs—Traditional and Roth—each offering unique tax advantages and withdrawal guidelines, it’s essential to grasp the nuances of these accounts to avoid unnecessary penalties.
As retirement approaches, knowing when and how to withdraw funds becomes crucial. Imagine if you could confidently navigate this aspect of your financial journey. It’s important to understand that a significant portion of Americans remains unaware of the specific rules governing their IRAs. This article delves into the essential aspects of IRA withdrawals, including:
- Age milestones
- Required Minimum Distributions (RMDs)
- Strategies for evaluating your personal financial situation
By equipping yourself with this knowledge, you can make informed decisions that align with your family’s financial goals. Together, we can navigate this journey toward a secure retirement, ensuring that your loved ones are taken care of every step of the way.
Understand IRA Basics and Withdrawal Rules
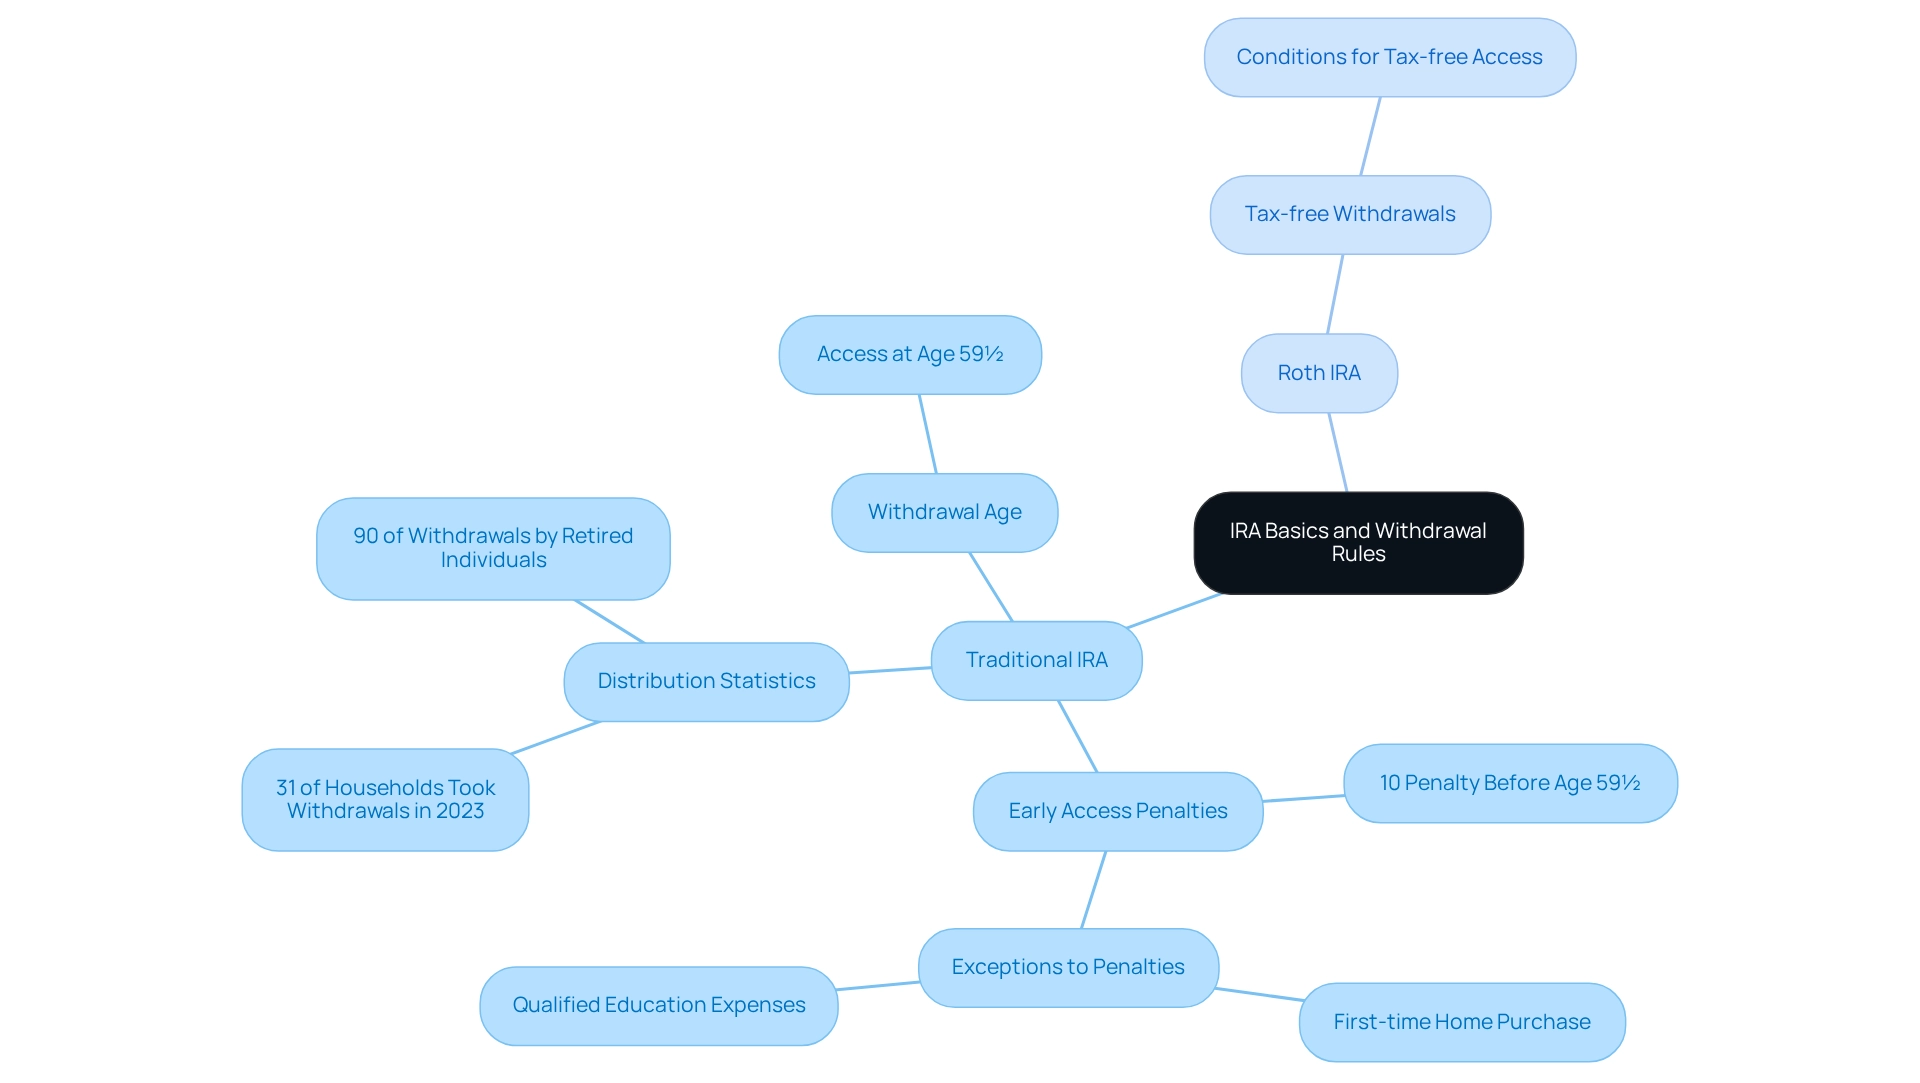
An Individual Retirement Account (IRA) is a valuable tool designed to help you save for retirement while enjoying tax advantages. The two primary types of IRAs, Traditional IRAs and Roth IRAs, each offer unique benefits and rules regarding withdrawals.
Typically, when do I have to start drawing from my IRA funds without penalties? You can access your funds once you reach age 59½. If you need to withdraw funds before this age, be mindful that a 10% early withdrawal penalty may apply, along with income taxes on the amount withdrawn. Understanding these essential rules is crucial for effective retirement planning, particularly regarding when do I have to start drawing from my IRA to avoid unnecessary penalties.
On the other hand, Roth IRAs allow for tax-free withdrawals during retirement, as long as certain conditions are met, which leads many to ask, ‘when do I have to start drawing from my IRA?’
- Age for Access: You can start accessing your funds without penalties at age 59½.
- Early Access: If you withdraw funds before age 59½, penalties may apply unless specific exceptions, like first-time home purchases or qualified education expenses, are relevant to your situation.
Recent studies reveal that many Americans are not fully aware of the rules surrounding IRA access, with a small percentage actively exploring their options. In 2023, only 31% of households with traditional IRAs took distributions, primarily retirees. This highlights the importance of understanding these accounts as families prepare for their financial futures. Economic experts emphasize that the tax benefits of IRAs can be significant, especially for young parents striving to secure their family’s financial stability. By grasping the fundamentals of IRAs and their withdrawal regulations, families can make informed decisions that align with their long-term financial goals.
At Bright Advisers, we are dedicated to helping families like yours optimize IRA management and enhance financial planning through innovative strategies, including smart beta and factor investing. Together, we can navigate the challenges of financial planning, ensuring you have access to the resources and guidance you need. Remember, we’re here for you every step of the way.
Identify Age Milestones for IRA Withdrawals
It’s crucial for your financial journey to understand when do I have to start drawing from my IRA without penalties, especially as you consider your family’s future. Here’s what you need to know:
-
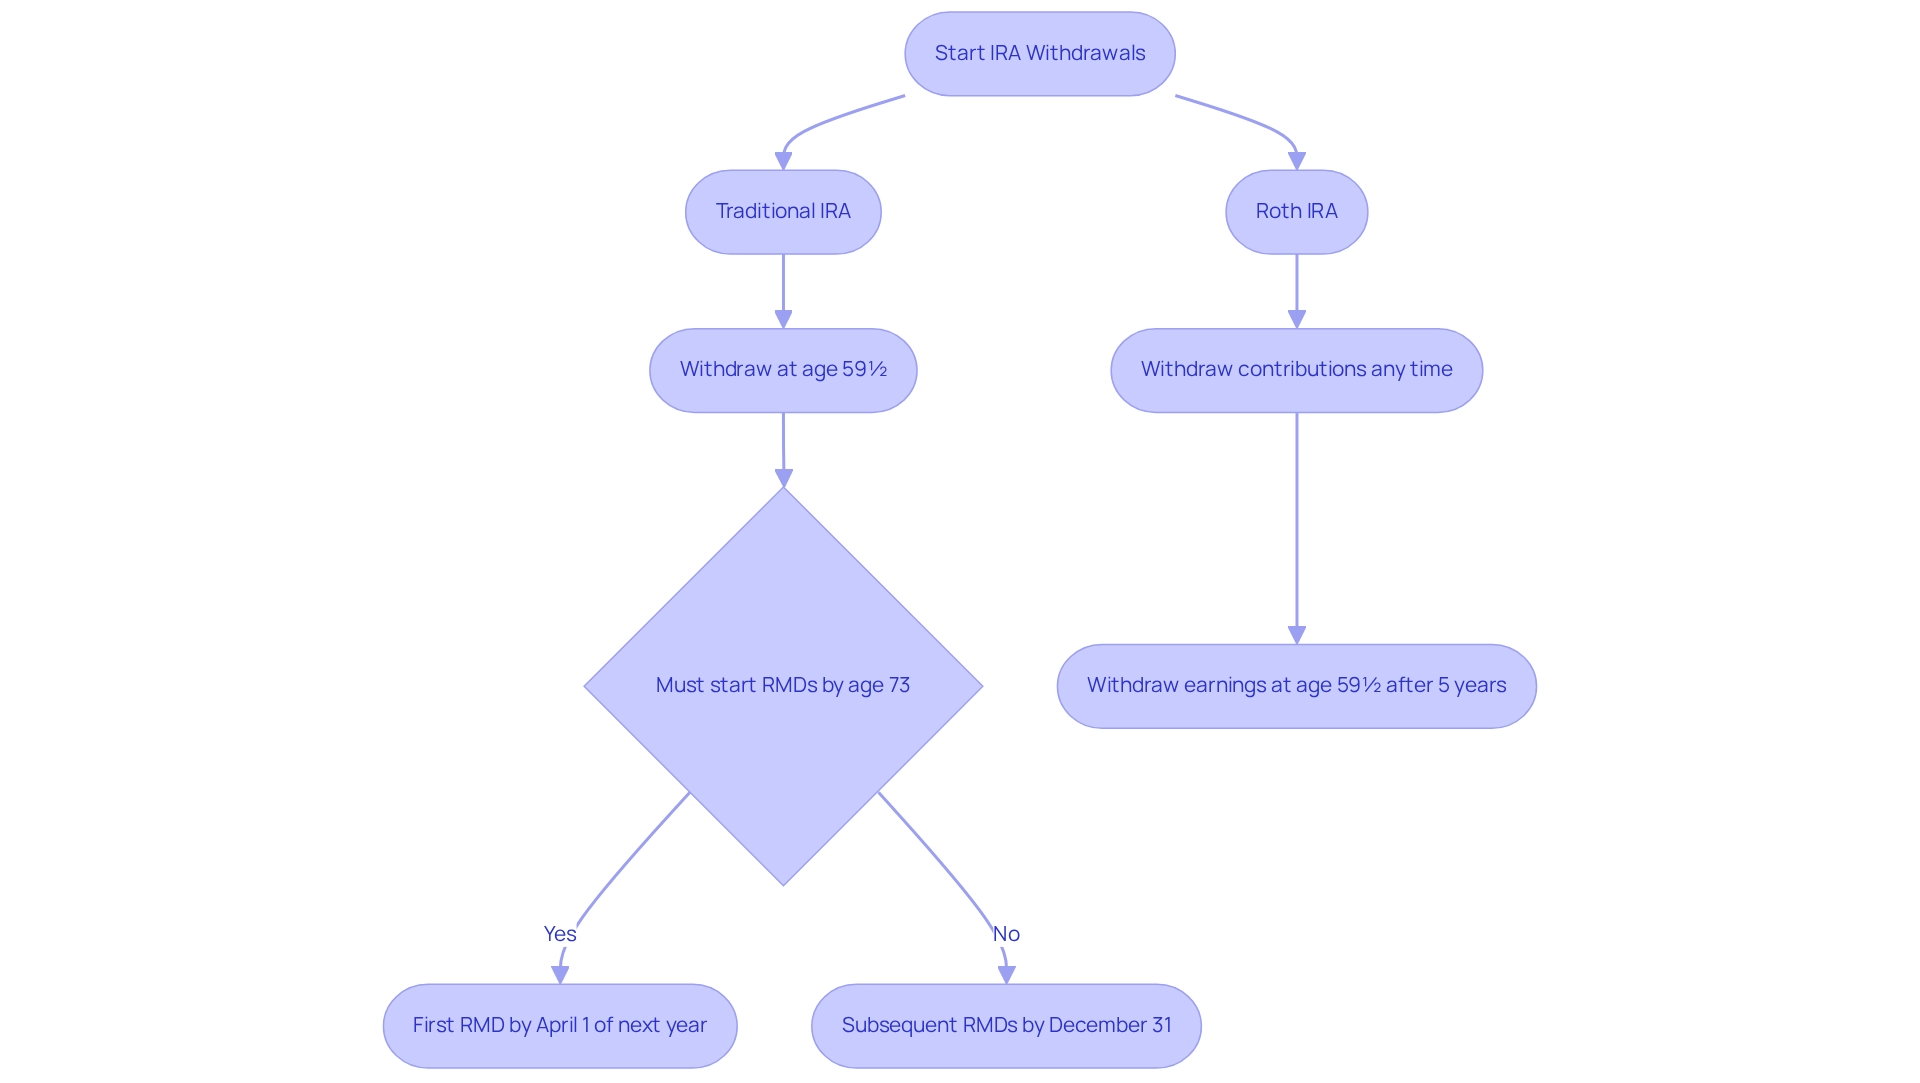
Traditional IRA: You can start making penalty-free withdrawals at age 59½. However, it’s important to remember when do I have to start drawing from my IRA, as you must begin taking Required Minimum Distributions (RMDs) by April 1 of the year following the year you turn 73. For instance, if you turn 73 in 2025, your first RMD must be taken by April 1, 2026, with subsequent RMDs due by December 31 each year.
-
Roth IRA: You have the flexibility to withdraw contributions at any time without penalties. However, to withdraw earnings tax-free, you need to be at least 59½ and have held the account for at least five years.
Imagine the peace of mind knowing that you are prepared for your retirement years. In 2025, approximately 30% of IRA holders in the U.S. have a Roth IRA, showing a growing preference for tax-free growth options among younger investors. It’s comforting to see that nearly 50% of all IRA distributions come from individuals aged 60 and older, which highlights the importance of understanding when do I have to start drawing from my IRA as you approach retirement. Experts emphasize the importance of RMDs, noting that failing to withdraw the required amount can lead to a hefty penalty—up to 50% of the amount that should have been withdrawn. But don’t worry; there are exceptions for early access without penalties, such as in cases of disability or significant medical costs. This offers flexibility for those who may need it.
Comprehending these age prerequisites and withdrawal tactics is essential for efficient planning for later life. It ensures you can optimize your savings while adhering to IRS regulations. If you have personal finance inquiries, we encourage you to submit them for upcoming columns. Engaging with experts can provide you with tailored insights for your unique situation. Remember, as noted by Bankrate, you can trust that you’re receiving credible and dependable information when navigating these complex topics. Together, we can navigate this journey towards financial security for your family.
Learn About Required Minimum Distributions (RMDs)
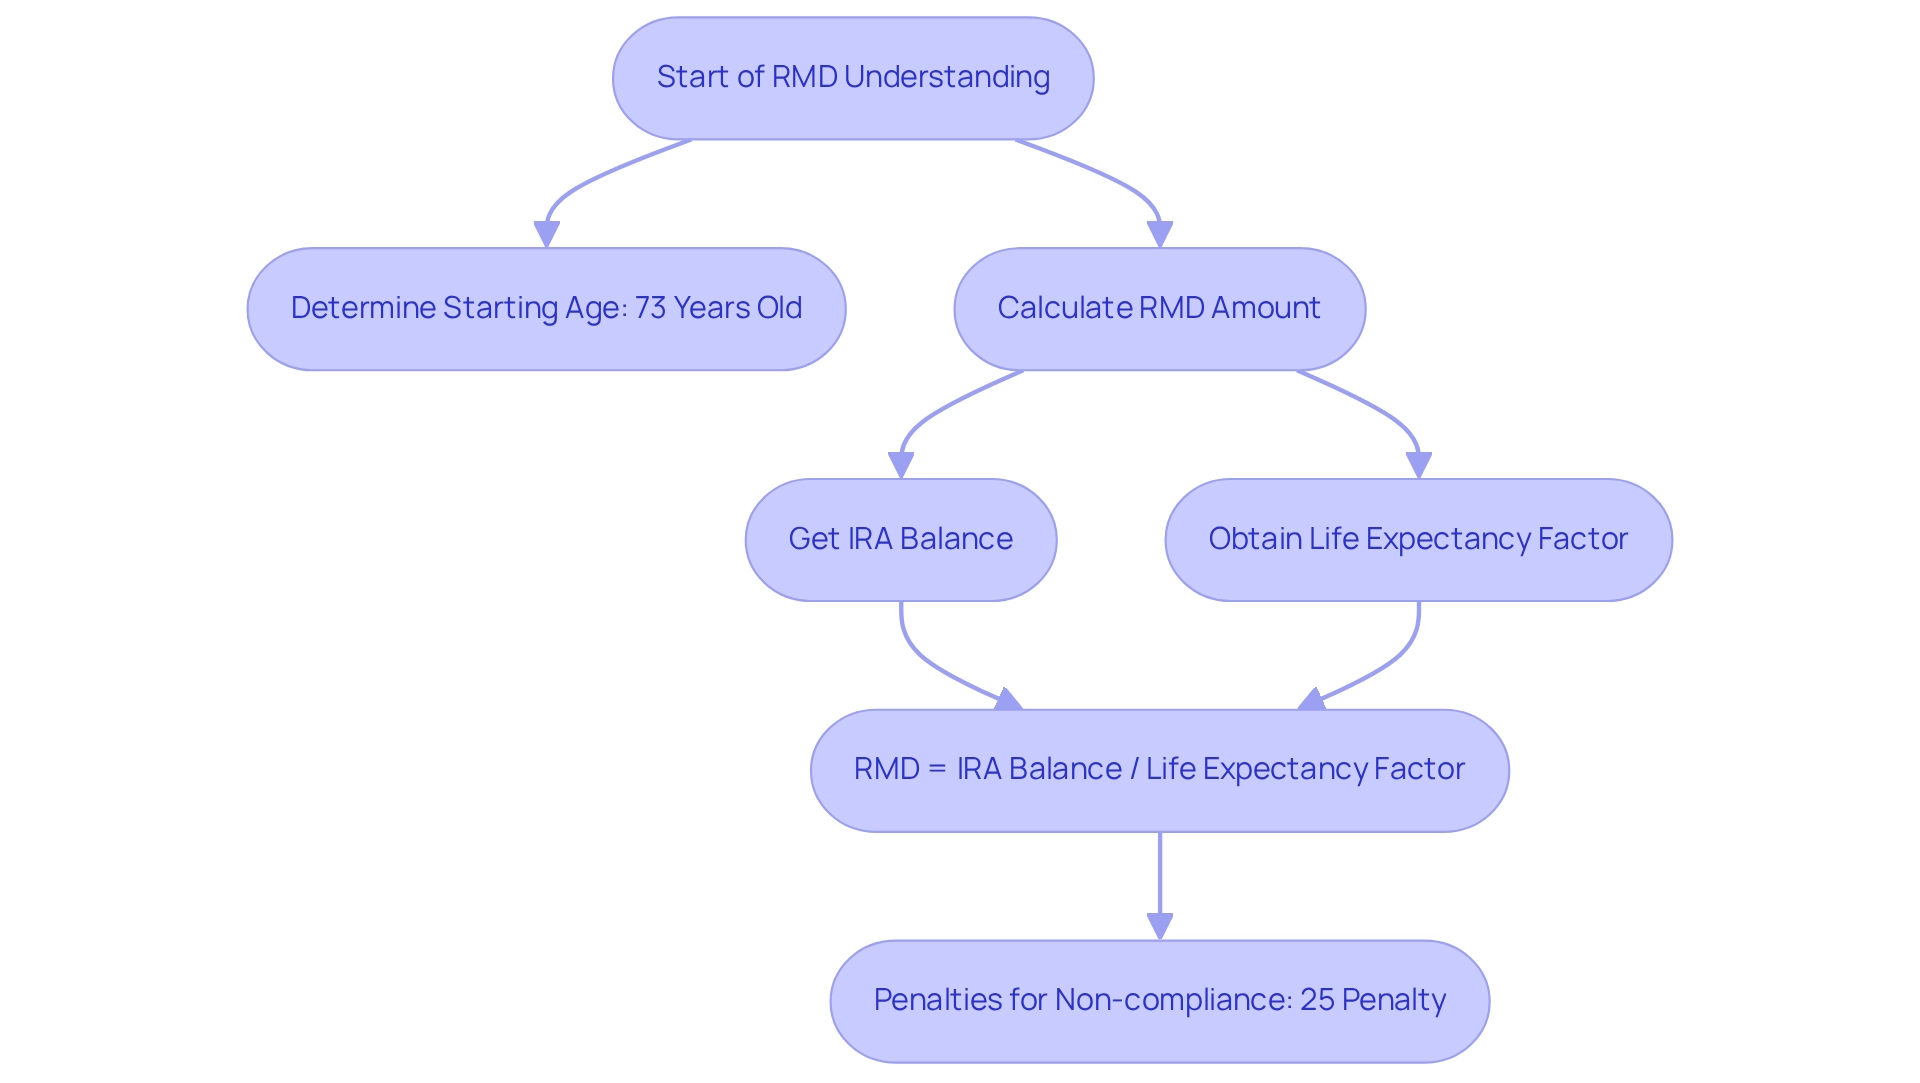
Required Minimum Distributions (RMDs) are the minimum amounts you need to withdraw from your Traditional IRA each year, which leads to the question, when do I have to start drawing from my IRA? Understanding this can feel overwhelming, but we’re here to help you navigate it with care.
Starting Age: When do I have to start drawing from my IRA? You must begin taking RMDs by April 1 of the year following your 73rd birthday. As you plan for your future, it’s important to keep in mind when do I have to start drawing from my IRA.
Calculation: The amount of your RMD is calculated by dividing your IRA balance as of December 31 of the previous year by a life expectancy factor provided by the IRS. For instance, if your IRA balance is $100,000 and your life expectancy factor is 25, your RMD would be $4,000 ($100,000 / 25). Understanding this calculation can help you feel more in control of your finances.
Penalties: If you miss taking your RMD, the IRS imposes a penalty of 25% on the amount that should have been withdrawn. Knowing this can motivate you to stay on track.
In 2025, compliance rates for RMDs in the U.S. are notably high, with over 90% of retirees meeting their RMD obligations. Financial planning specialists emphasize that understanding when do I have to start drawing from my IRA is essential for sustaining financial well-being in later life. Imagine if you could approach your retirement years with confidence and clarity.
For individuals aged 120 and over, the distribution period decreases to just 2.0 years. This highlights the need for tailored strategies as you age, ensuring your financial plan evolves with your needs.
Case studies from Dimov Tax illustrate the impact of RMDs on financial planning for later life. Their expert guidance helps clients navigate the complexities of RMDs, ensuring compliance with IRS regulations while developing proactive withdrawal strategies. As Dimov Tax states, “We’re here to assist you every step of the way,” emphasizing their commitment to personalized service and support.
As you prepare for your later years, consider the average RMD amounts taken from Traditional IRAs in 2025. This knowledge can guide your economic strategy, helping you make informed decisions. Collaborating with experts like Dimov Tax can provide additional perspectives and assistance, ensuring you fulfill your RMD responsibilities while maximizing your income during your later years. Together, we can navigate this journey.
Evaluate Your Financial Situation and Withdrawal Needs
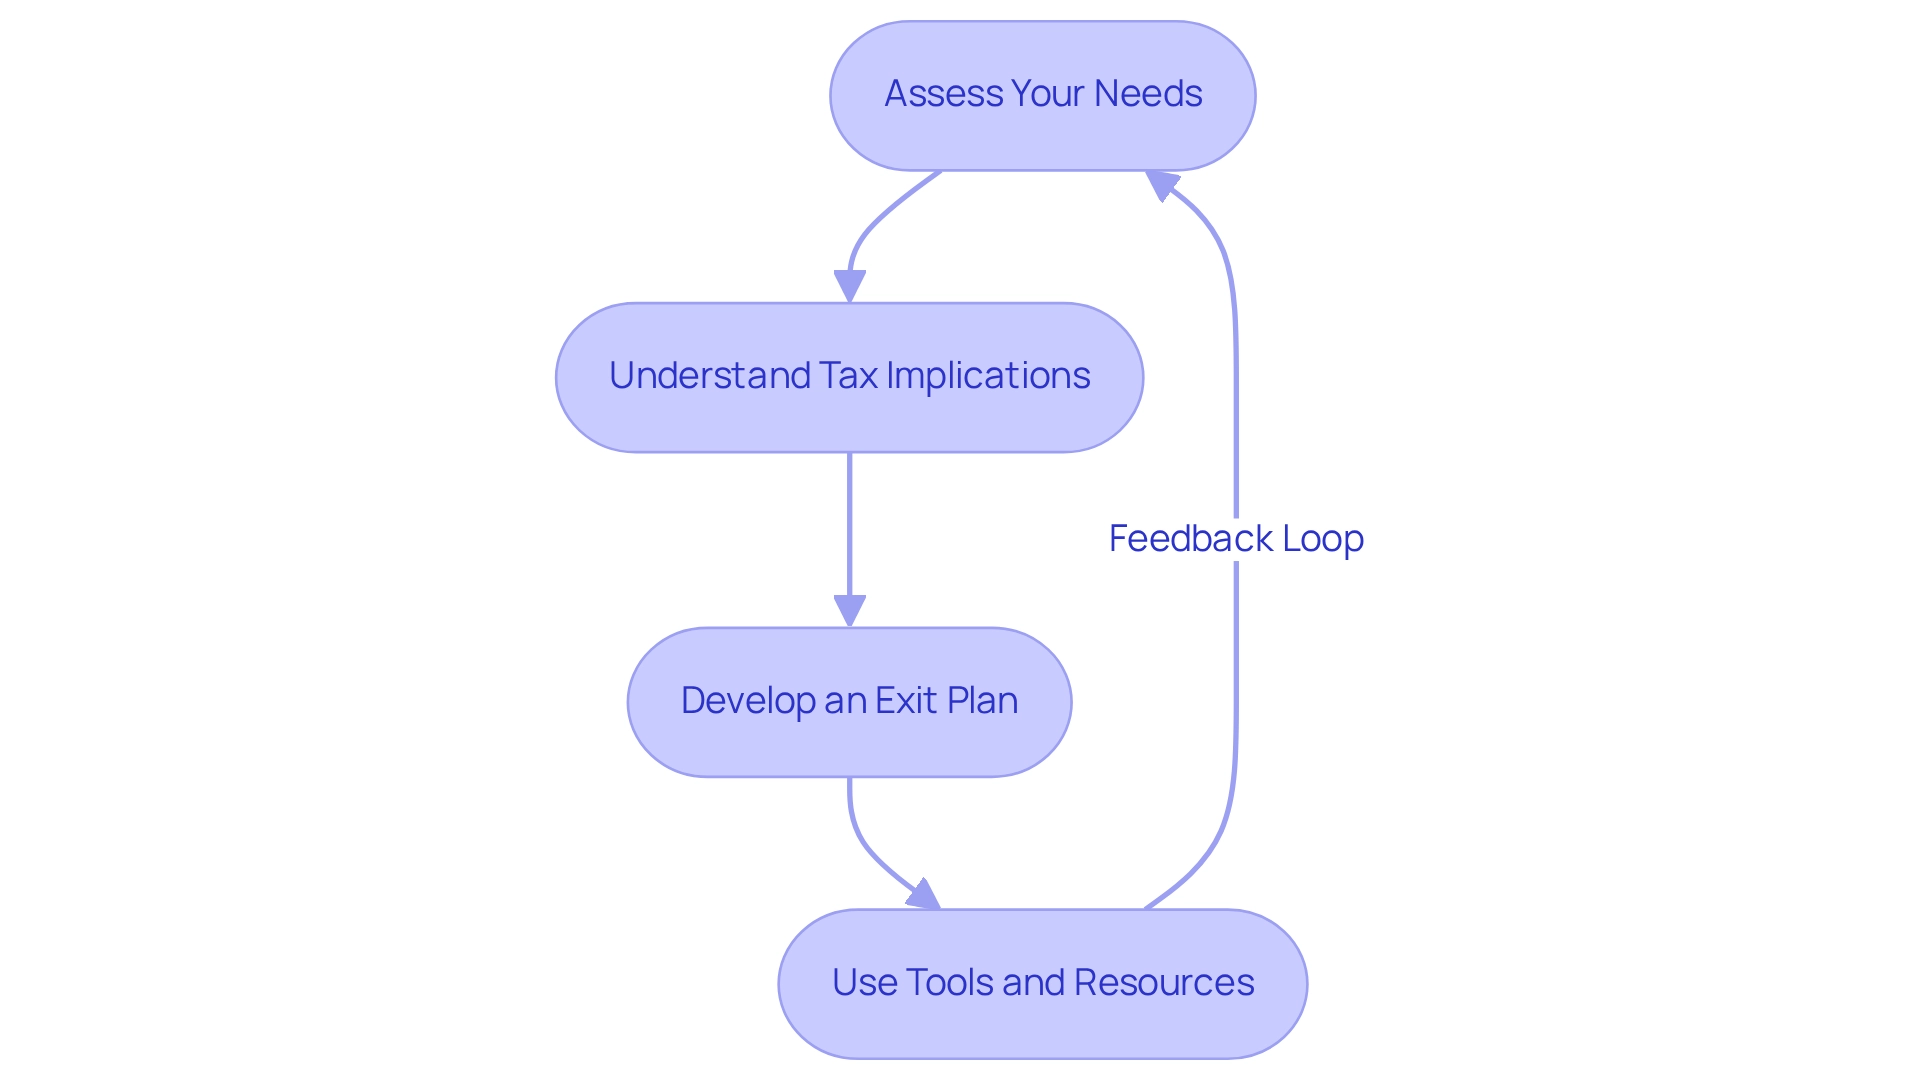
Before you determine when do I have to start drawing from my IRA, it’s essential to take a moment to assess your financial situation thoroughly. Let’s explore some key steps together:
- Assess Your Needs: Think about the income you’ll need during your later years and how your IRA fits into your overall financial picture. With 37% of retirees lacking adequate savings for their later years, understanding your needs is crucial for securing your future. As we approach 2025, young families should recognize that retirement income needs can vary significantly, making thoughtful planning vital. Bright Advisers emphasizes the importance of crafting a lasting strategy that aligns with your values and vision, guiding your choices along the way.
- Tax Implications: It’s important to grasp the tax effects of your distributions. Traditional IRA withdrawals are taxed as ordinary income, which could push you into a higher tax bracket. In 2025, understanding average tax implications for retirees will highlight the need for strategic planning to ease tax burdens. Consulting with a financial advisor, such as those at Bright Advisers, can offer valuable insights into navigating these tax implications effectively, enhancing your financial strategy.
- Exit Plan: Consider developing an exit plan that aligns with your financial goals. For example, you might choose to withdraw only the minimum required amount to minimize tax liabilities or, when do I have to start drawing from my IRA, decide to withdraw more to cover living expenses. As June Sham suggests, seeking additional help from a financial consultant can be beneficial for those concerned about their future savings. Bright Advisers offers tailored financial planning and investment management designed for families with young children, ensuring your approach is flexible and suited to your unique situation.
Tools and Resources:
- RMD Calculators: Use online calculators to estimate your Required Minimum Distributions (RMDs) based on your account balance and age.
- Advisors: Engaging with an advisor from Bright Advisers can help you create a personalized withdrawal strategy that meets your specific needs. As specialists note, seeking extra assistance can be advantageous for individuals concerned about their future financial progress.
- Educational Resources: Take advantage of resources like planning workshops, online courses, and financial literacy programs that enhance your understanding of financial planning. These tools will empower you as you navigate your financial future. Additionally, keep in mind the impact of inflation on your retirement planning, as studies show how inflation can influence savings strategies.
Conclusion
Understanding the intricacies of Individual Retirement Accounts (IRAs) is vital for young parents who wish to secure their family’s financial future. Imagine if you could navigate the complexities of retirement planning with confidence. This article explores the two primary types of IRAs—Traditional and Roth—along with their specific withdrawal rules and age milestones. Knowing when and how to withdraw funds, including the implications of Required Minimum Distributions (RMDs), empowers you to make informed decisions that align with your long-term financial goals.
As retirement approaches, it becomes increasingly important to evaluate your personal financial situation and develop tailored withdrawal strategies. It’s essential to recognize the tax implications of withdrawals and the potential penalties for early withdrawals. This awareness can safeguard you against unnecessary financial burdens. Engaging with financial advisors can provide valuable insights that enhance your retirement planning, ensuring that your family can navigate these complexities with confidence.
Ultimately, by equipping yourself with knowledge about IRAs and adopting strategic approaches to withdrawals, you can take proactive steps toward achieving a secure retirement. This understanding not only protects your savings but also lays the groundwork for a stable financial future for your loved ones. Together, we can navigate this journey toward financial security, and with the right resources and guidance, families like yours can effectively overcome the challenges ahead.
Frequently Asked Questions
What is an Individual Retirement Account (IRA)?
An IRA is a tax-advantaged vehicle designed to help individuals save for retirement, with two main types being Traditional IRAs and Roth IRAs, each offering unique tax benefits and withdrawal guidelines.
At what age can I start withdrawing from my IRA without penalties?
You can withdraw funds from your IRA without penalties once you reach age 59½.
What happens if I withdraw money from my IRA before age 59½?
If you withdraw money from your IRA before age 59½, you may face a 10% early withdrawal penalty, in addition to applicable income taxes.
Are there any exceptions to the early withdrawal penalty for IRAs?
Yes, exceptions to the early withdrawal penalty may apply for first-time home purchases or qualified education expenses.
How does a Roth IRA differ from a Traditional IRA regarding withdrawals?
Roth IRAs offer tax-free access during retirement, allowing you to begin accessing your funds without penalties at age 59½, provided certain conditions are met.
What percentage of households with traditional IRAs withdrew money in 2023?
In 2023, only 31% of households with traditional IRAs withdrew money, primarily retirees.
Why is it important to understand IRA access rules?
Understanding IRA access rules is vital for effective retirement planning, helping individuals avoid unnecessary penalties and make informed decisions regarding their financial future.
What services does Bright Advisers provide for families?
Bright Advisers offers personalized wealth management solutions tailored for young families, including access to innovative strategies, minimal fund fees, and educational resources for effective financial planning.
List of Sources
- Understand IRA Basics and Withdrawal Rules
- IRAs Play an Increasingly Important Role in Saving for Retirement (https://ici.org/news-release/25-news-ira)
- IRA Use Has Risen 10% Over Past Decade, ICI Study Finds (https://401kspecialistmag.com/ira-use-up-10-in-past-decade-study)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- The Average IRA Balance by Age (https://kiplinger.com/retirement/iras/the-average-ira-balance-by-age)
- Recent IRA Statistics – Greenleaf Trust (https://greenleaftrust.com/missives/recent-ira-statistics)
- Identify Age Milestones for IRA Withdrawals
- Ask an Advisor: Will IRA Withdrawals Before Age 73 Offset My RMDs? (https://finance.yahoo.com/news/ask-advisor-ira-withdrawals-turn-123000573.html)
- Required Minimum Distributions: What’s New in 2025 (https://schwab.com/learn/story/required-minimum-distributions-what-you-should-know)
- IRA Required Minimum Distribution (RMD) Table 2024-2025 | Bankrate (https://bankrate.com/retirement/ira-rmd-table)
- IRA and Tax Tables 2025 Archives – Ed Slott and Company, LLC (https://irahelp.com/printables/2025)
- 2 Big Changes to RMDs That Will Affect Retirees in 2023 (https://nasdaq.com/articles/2-big-changes-to-rmds-that-will-affect-retirees-in-2023)
- Required Minimum Distribution (RMD) Rules Explained | Human Interest (https://humaninterest.com/learn/articles/required-minimum-distribution-rmd-rules)
- What are the key ages for milestones on your retirement journey? (https://allianceam.com/legacy/key-ages-for-milestones-on-retirement-journey)
- Learn About Required Minimum Distributions (RMDs)
- Required Minimum Distributions: Ages & Calculations for 2025 (https://dimovtax.com/rmds-key-rules-ages-and-calculations)
- IRA And 401k RMD Table For 2024 & 2025 – Carry (https://carry.com/learn/rmd-table)
- IRA Required Minimum Distribution (RMD) Table for 2025 (https://smartasset.com/retirement/rmd-table)
- How do I calculate my required minimum distribution? (https://fidelity.com/learning-center/personal-finance/first-rmd-requirements)
- Required Minimum Distribution (RMD) Rules Explained | Human Interest (https://humaninterest.com/learn/articles/required-minimum-distribution-rmd-rules)
- Evaluate Your Financial Situation and Withdrawal Needs
- 28 Retirement Statistics You Should Know for 2025 | Harbor Life (https://harborlifesettlements.com/retirement-statistics)
- Average Retirement Savings by Age – NerdWallet (https://nerdwallet.com/article/investing/the-average-retirement-savings-by-age-and-why-you-need-more)
- Average Retirement Income 2025: How Do You Compare? (https://retirable.com/advice/lifestyle/average-retirement-income-how-do-you-compare)
- Americans Believe They Will Need $1.26 Million to Retire Comfortably According to Northwestern Mutual 2025 Planning & Progress Study (https://news.northwesternmutual.com/2025-04-14-Americans-Believe-They-Will-Need-1-26-Million-to-Retire-Comfortably-According-to-Northwestern-Mutual-2025-Planning-Progress-Study)
- What are the Average Retirement Expenses? | 4 Typical Expenses (https://actsretirement.org/resources-advice/finance-saving-money/saving-money-after-retirement/retirement-expenses)
- The Average Retirement Budget in the U.S. (https://smartasset.com/retirement/average-retirement-budget)
- The Average Monthly Retirement Budget Is $4,345 — Can Millennials Live Off That? (https://nasdaq.com/articles/average-monthly-retirement-budget-4345-can-millennials-live)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading