

Overview
Imagine a future where your child’s education is within reach, free from the weight of financial stress. 529 plans serve as tax-deferred savings vehicles, thoughtfully designed to help families like yours save for future education expenses. These plans allow your contributions to grow without immediate taxation, and when it’s time to withdraw for qualified expenses, those withdrawals are tax-free. This means that the money you save can work harder for you, enhancing the potential for compound growth.
It’s important to understand how these tax advantages can significantly alleviate the financial burdens associated with education costs. By choosing a 529 plan, you are not just saving; you are creating a pathway to a brighter future for your child. This strategy empowers families to manage education expenses more effectively, making it an invaluable tool in your financial planning journey.
We’re here for you, ready to support you as you navigate this important decision. Together, we can explore how 529 plans can fit into your family’s financial goals, ensuring that your child’s educational aspirations are not just dreams, but achievable realities.
Key Highlights:
- 529 plans are tax-advantaged savings vehicles designed to help families save for future education expenses.
- There are two main types of 529 plans: college savings accounts and prepaid tuition plans.
- The primary goal of 529 plans is to make higher education more accessible and affordable for families.
- As of 2025, all states except Wyoming offer 529 options, with around 17 million accounts in use.
- Contributions to 529 plans grow tax-deferred, and withdrawals for qualified education expenses are tax-free at the federal level.
- Many states offer additional tax incentives for contributions to 529 accounts, enhancing their attractiveness.
- 529 plans enable families to benefit from compound growth without annual taxes, significantly increasing potential savings.
- Families can automate contributions for consistent saving, and early saving leads to higher overall savings for education.
- Limitations of 529 plans include non-deductible contributions for federal taxes and potential penalties for non-qualified withdrawals.
- Alternatives to 529 plans include Coverdell Education Savings Accounts (ESAs) and custodial accounts, which may offer more investment flexibility.
Introduction
Understanding the financial landscape of education savings is essential for families who wish to secure their children’s future. Imagine the peace of mind that comes with knowing you are preparing for their educational journey.
529 plans, crafted specifically for educational expenses, present a wonderful opportunity to save while enjoying significant tax advantages. It’s important to understand why 529 plans are tax deferred and how families can leverage this feature to maximize their savings.
Exploring the intricacies of these plans reveals not only their benefits but also the challenges and alternatives that families must consider in their educational financial planning. Together, we can navigate this journey, ensuring that your family’s goals are met with care and support.
Define 529 Plans and Their Purpose
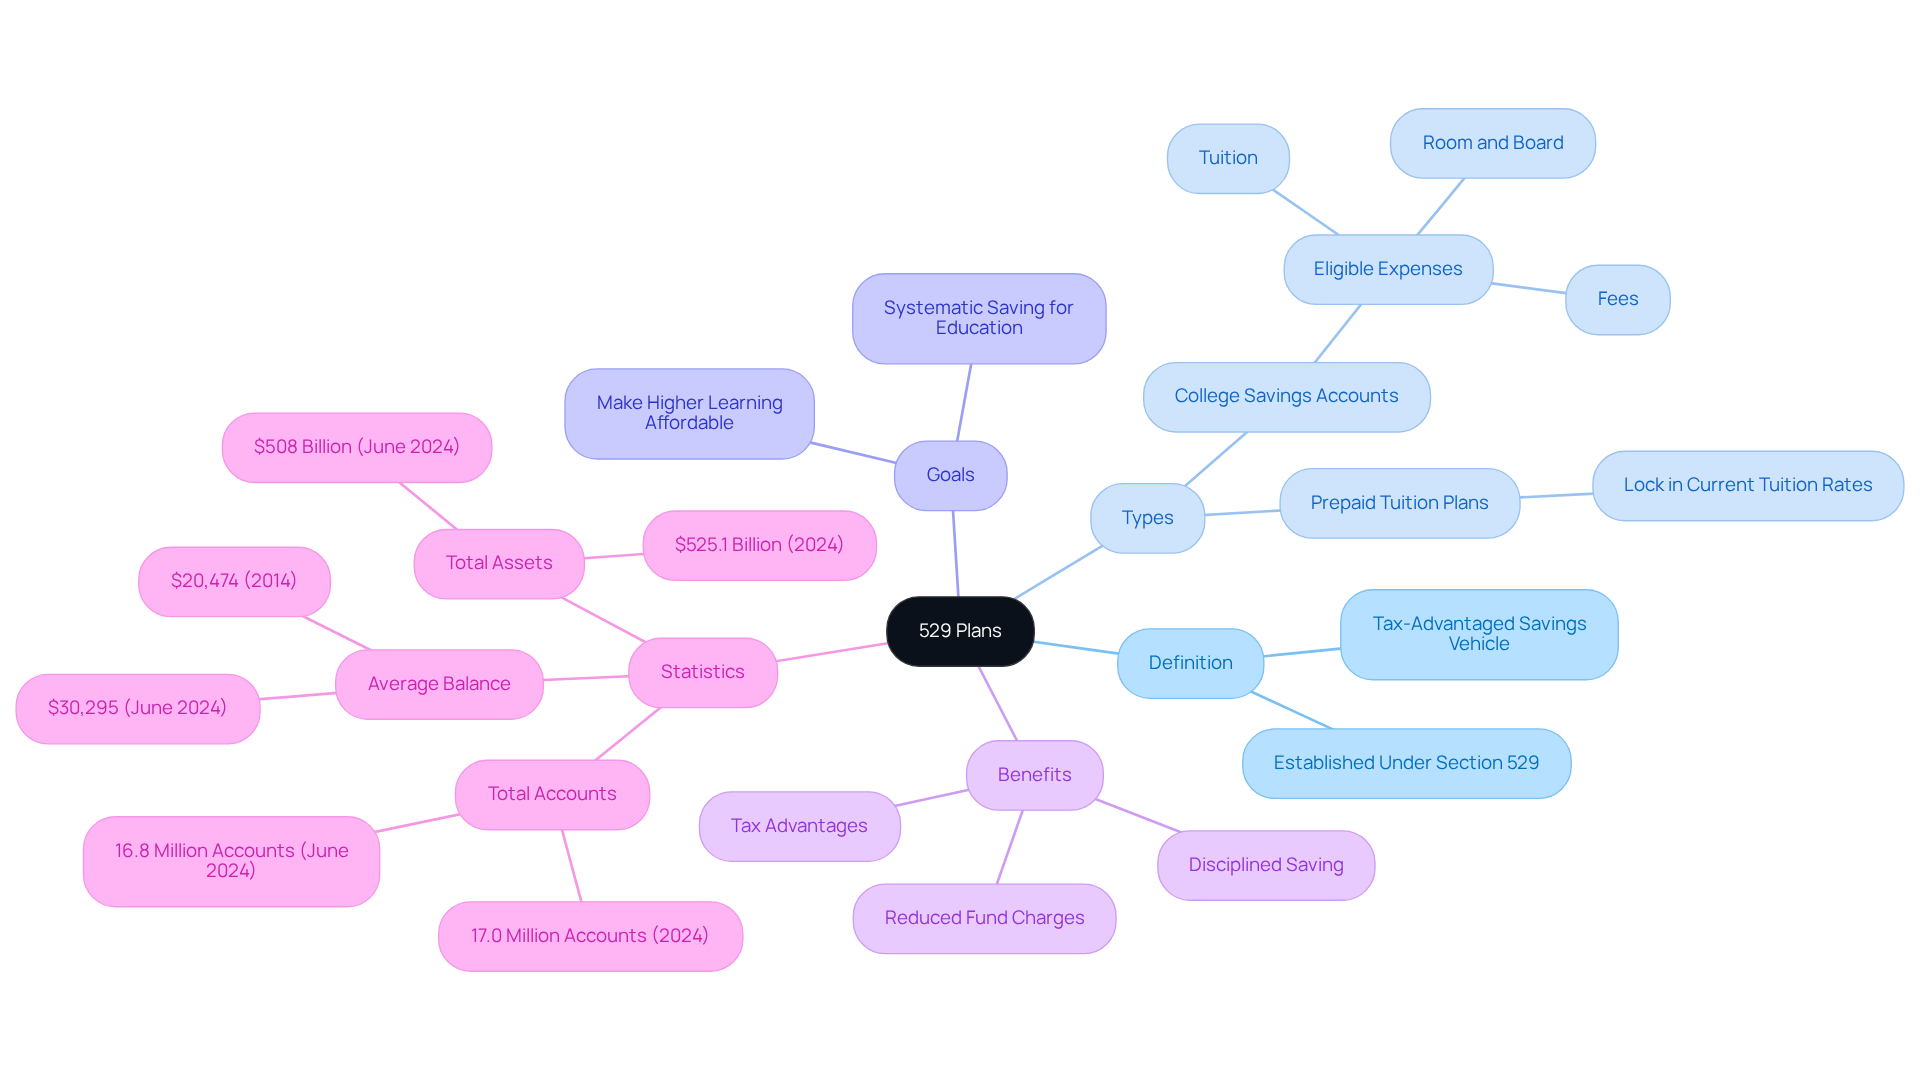
A 529 program is a tax-advantaged savings vehicle specifically designed to help families save for future education expenses. Established under Section 529 of the Internal Revenue Code, these programs are primarily sponsored by states or educational institutions. There are two main types of 529 options: college savings accounts and prepaid tuition plans. Imagine being able to gather resources for a range of eligible academic expenses, such as tuition, fees, and room and board. College savings programs allow you to do just that. On the other hand, prepaid tuition programs enable you to secure current tuition rates for future educational purposes, providing a safeguard against rising costs.
The main goal of 529 programs is to offer families a systematic and effective way to save for their children’s education, making higher learning more reachable and affordable. As of 2025, all states except Wyoming provide 529 options, reflecting a growing recognition of their importance in financial preparation for education. With around 17 million accounts across the country, more families are utilizing these arrangements to ensure a bright educational future for their children. Financial advisors, including those at Bright Advisers, emphasize that the question of whether 529 plans are tax deferred highlights their tax advantages and encourages disciplined saving. By reducing fund charges, Bright Advisers enhances the availability of these options, making them a vital part of a holistic financial approach for families focused on education.
This approach empowers young families to effectively allocate resources, alleviate financial anxiety, and secure their futures. Together, we can navigate this journey, ensuring your children have the opportunities they deserve.
Examine Tax Advantages of 529 Plans
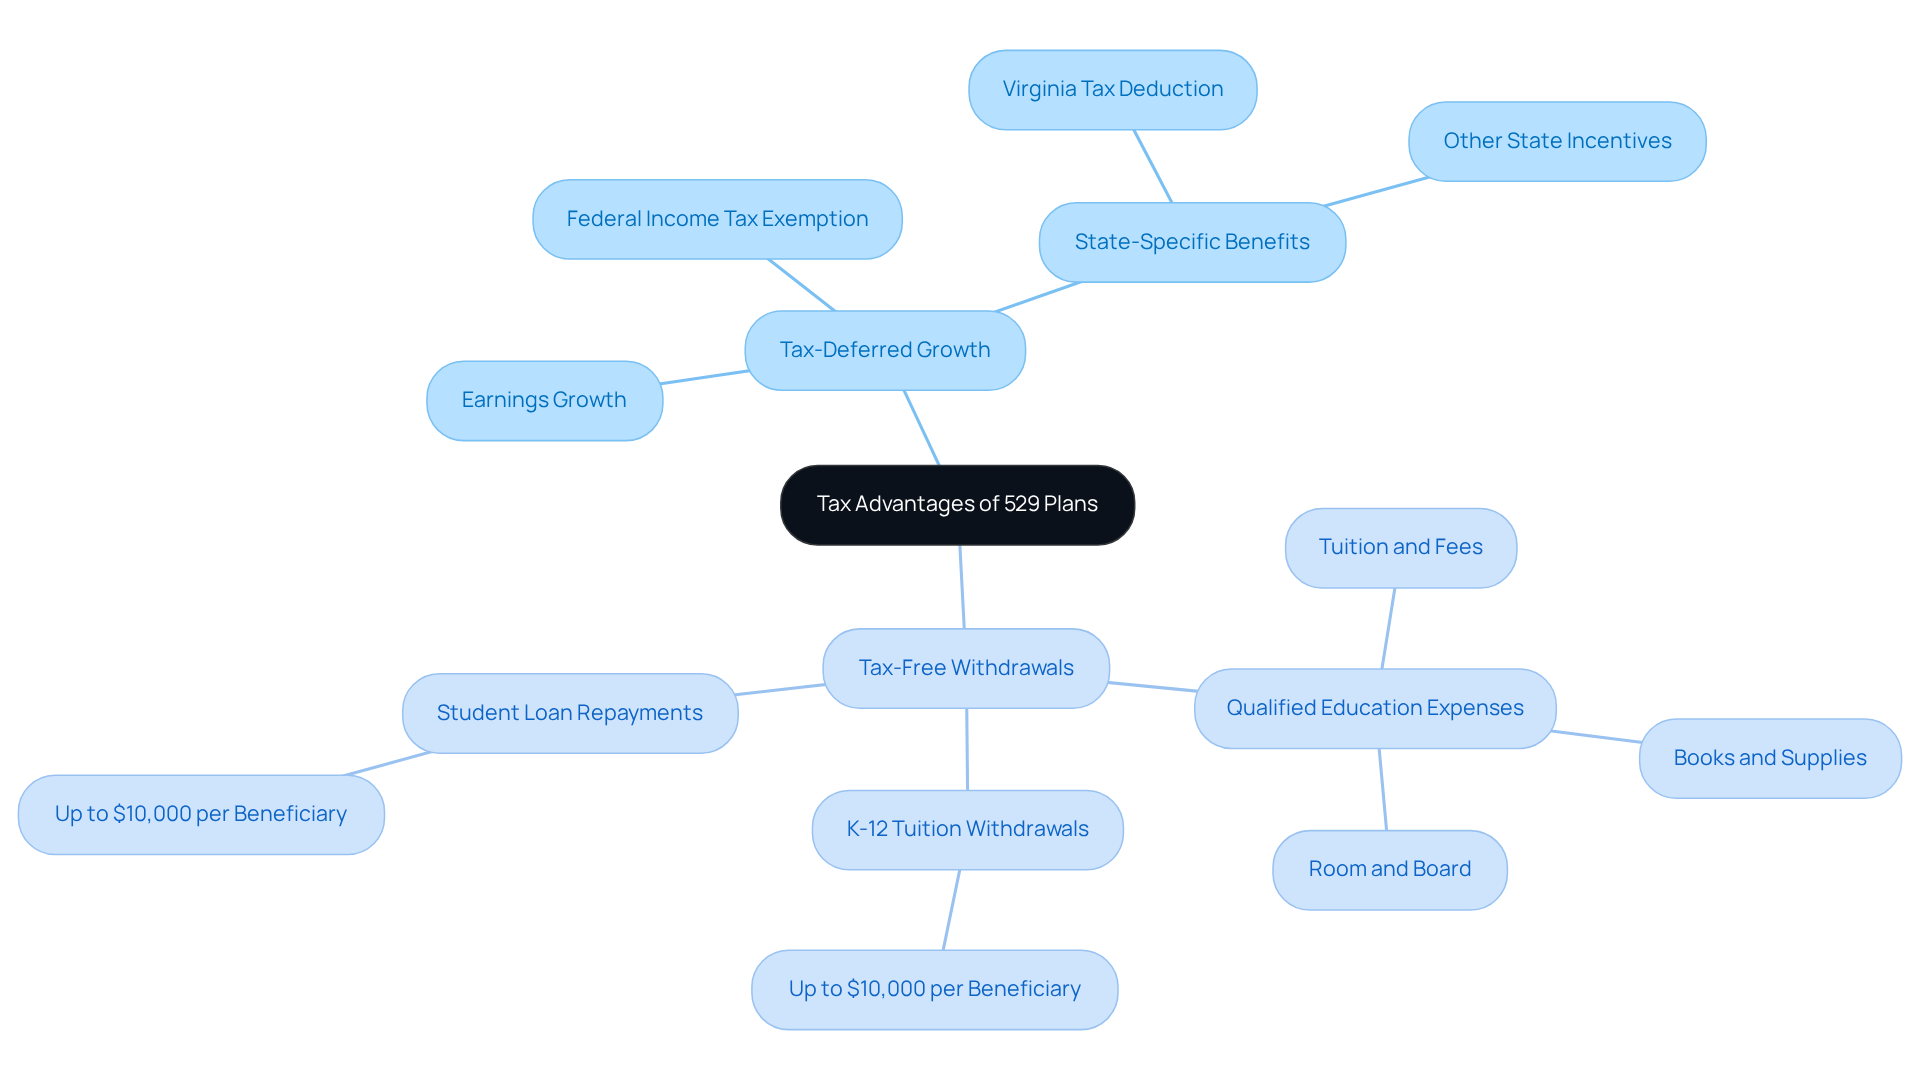
Are you feeling the weight of planning for your children’s education? You’re not alone. Families are increasingly drawn to 529 options, and it’s easy to see why. These programs, which are 529 plans tax deferred, come with significant tax benefits that can make a real difference in your financial journey. Imagine watching your contributions grow because 529 plans are tax deferred, freeing you from the burden of immediate taxation. Earnings like interest, dividends, or capital gains remain untouched by federal income tax while they stay in your account.
When it comes time to withdraw funds for qualified education expenses—think tuition, fees, books, and even room and board—those withdrawals are tax-free at the federal level. This means more money in your pocket when it matters most. Plus, many states offer additional incentives, such as tax deductions or credits for contributions to 529 accounts. For example, if you’re a Virginia resident, you can deduct up to $4,000 per account per year from your state income tax for contributions to Invest529.
This blend of tax-deferred growth and tax-free withdrawals illustrates how 529 plans are tax deferred, making them a powerful tool for families looking to optimize their savings for education. By leveraging these benefits, you can significantly lighten the financial load of education costs, making it easier to save for your children’s future. Remember, together, we can navigate this journey and ensure a brighter educational path for your little ones.
Analyze Financial Implications of Tax Deferral
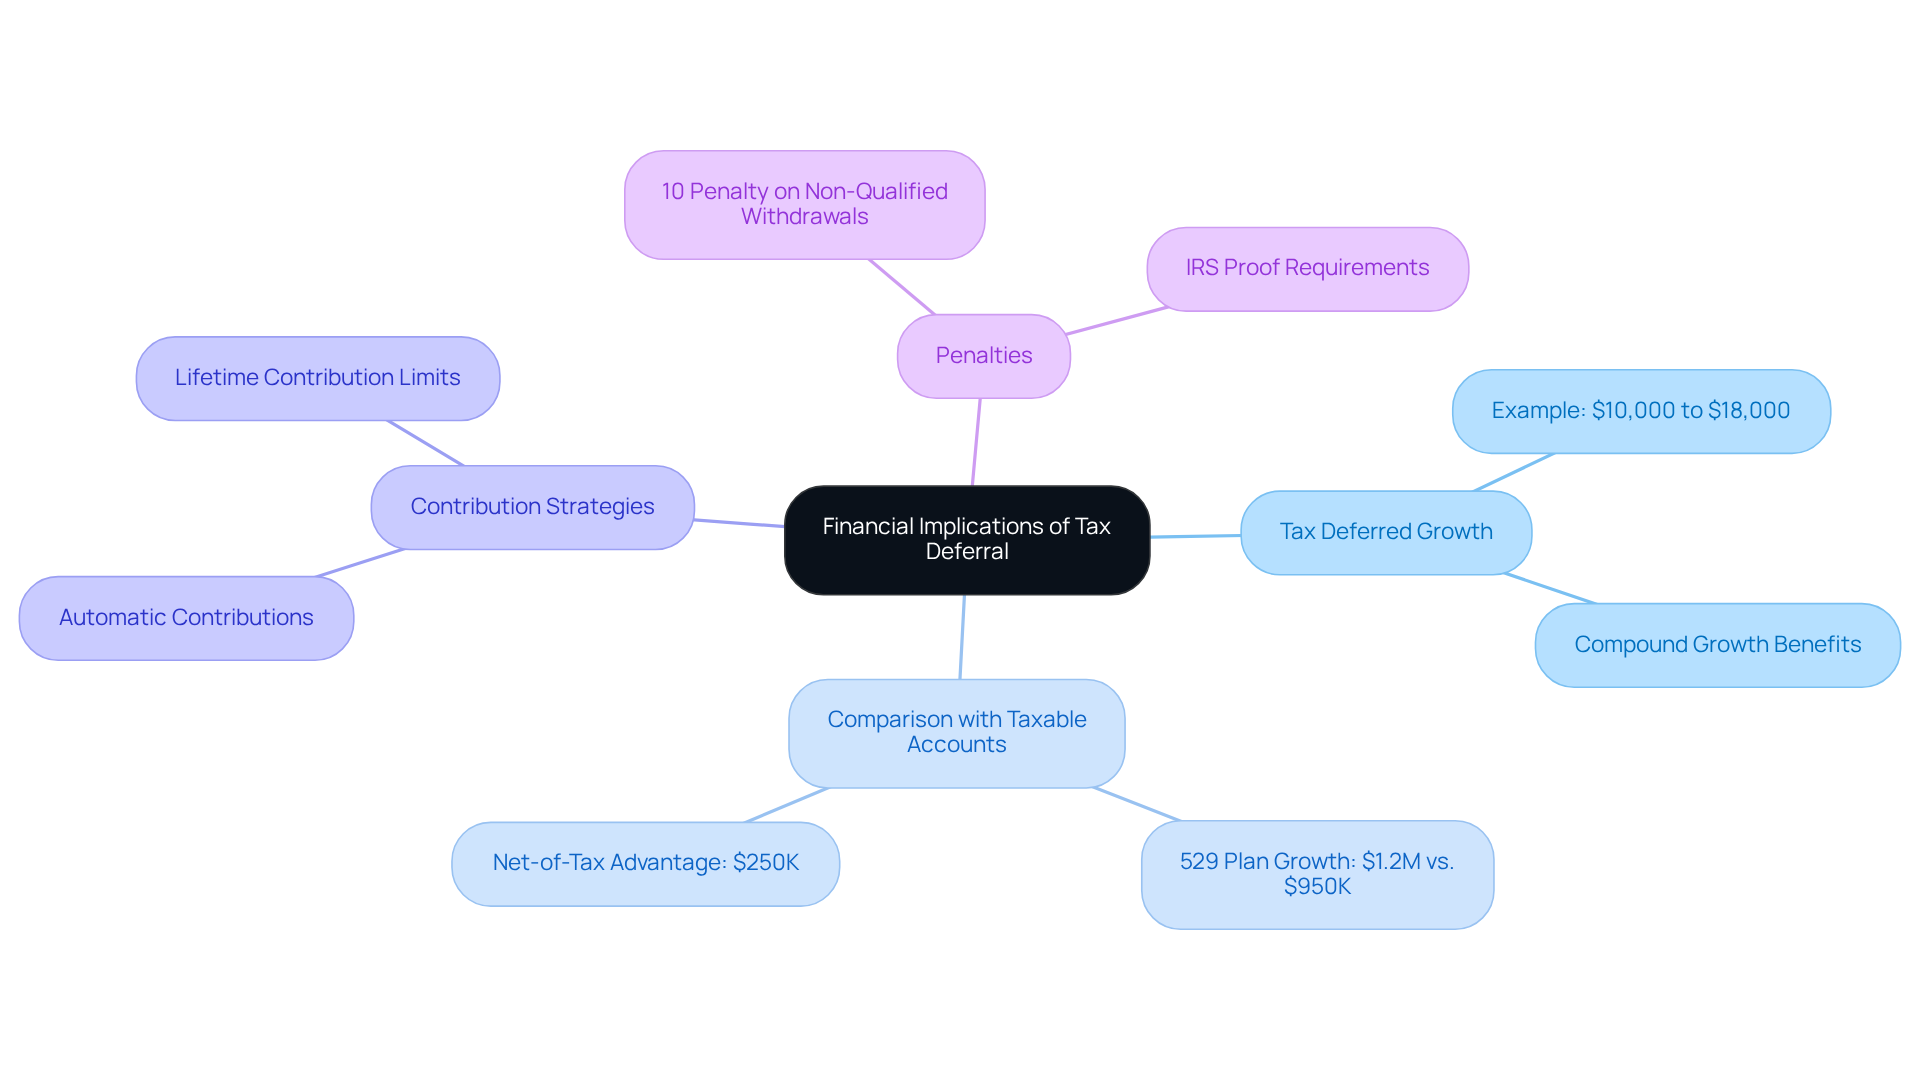
The remarkable financial advantages for families, as illustrated by Allison and Brian’s journey with Bright Advisers, stem from the fact that 529 plans are tax deferred. Imagine being able to watch your investments grow, especially since 529 plans are tax deferred, allowing you to avoid the burden of yearly taxes. This allows families to harness the power of compound growth over time. For instance, if a family contributes $10,000 to a 529 account with an average yearly return of 6%, they could see their balance swell to approximately $18,000 over 18 years—tax-free on those earnings. In contrast, placing the same amount in a taxable account would mean annual taxes on earnings, significantly limiting growth potential.
This tax-efficient growth is especially beneficial for families preparing for the rising costs of higher education, particularly because 529 plans are tax deferred. It empowers them to gather more resources for their children’s futures while alleviating tax obligations. Furthermore, the ability to withdraw funds tax-free for qualified higher education expenses enhances the financial benefits of a 529 account, which shows that 529 plans are tax deferred, making it a wise choice for education savings. As Susan Bart insightfully notes, “And when you withdraw the funds, provided they are used for qualified higher learning expenses, there’s no federal income tax on the distribution and often no state income tax.” This underscores why 529 options are a strategic choice for families.
Consider this: a 529 account funded with $377,000 could grow to exceed $1.2 million by age 18, compared to around $950,000 in a taxable account. This illustrates the significant financial advantages of 529 accounts. Families can also enjoy the convenience of automatic contributions, enabling consistent savings through monthly deposits directly from paychecks or savings accounts.
However, it’s essential to be mindful of potential penalties for non-qualified withdrawals, which can affect the overall effectiveness of the savings strategy. Bright Advisers’ commitment to minimal fund fees further enhances wealth management accessibility for families, empowering them to achieve financial security and freedom through personalized planning and tax optimization.
In conclusion, utilizing 529 accounts, which are 529 plans tax deferred, can significantly enhance a family’s ability to save for education while minimizing tax burdens. Together, we can navigate this journey towards better financial health for your household.
Consider Limitations and Alternatives to 529 Plans
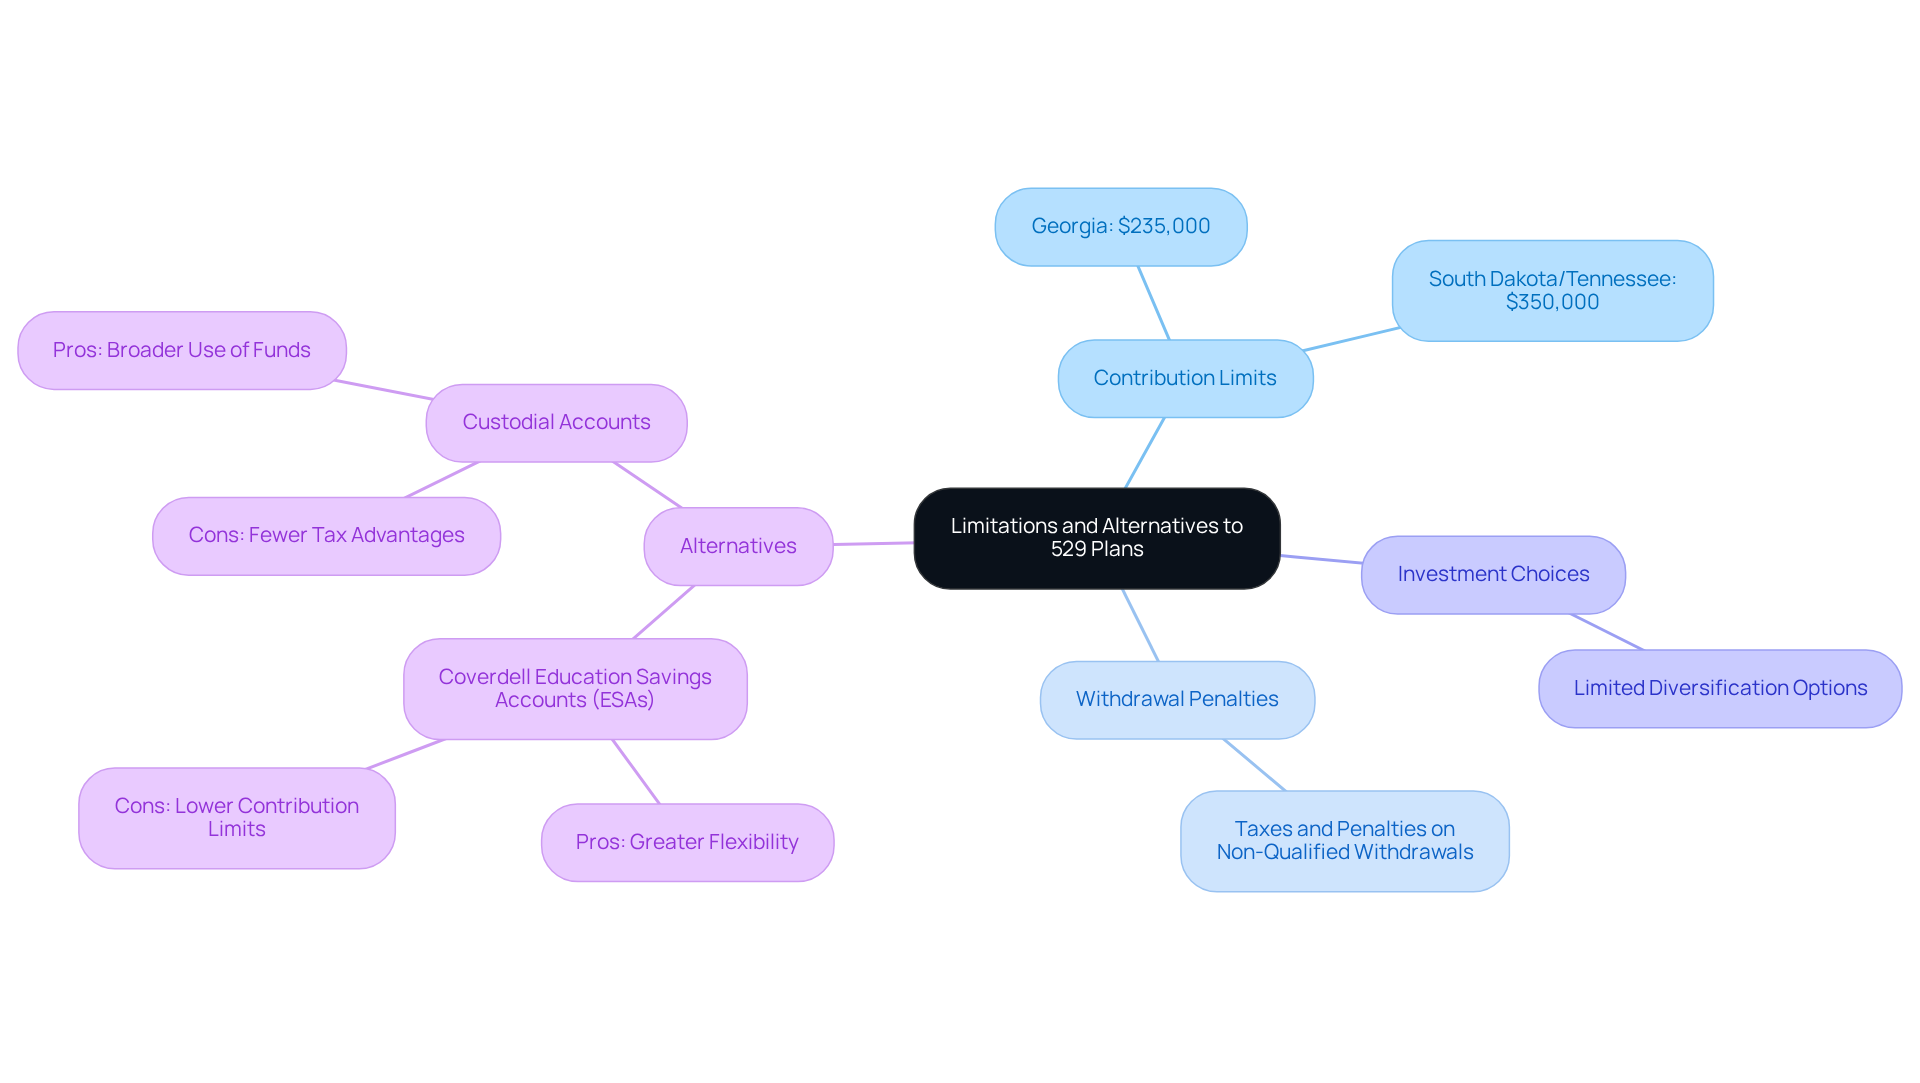
While it is essential to consider their drawbacks as well, many parents wonder if 529 plans are tax deferred, as they can be a valuable tool for saving for your child’s education. Contributions to a 529 account are not tax-deductible on federal tax returns, and each state has specific contribution limits that can vary significantly. For example:
- Georgia has the lowest aggregate contribution limit at $235,000.
- States like South Dakota and Tennessee allow contributions of up to $350,000.
Additionally, if the funds aren’t used for qualified education expenses, withdrawals may incur taxes and penalties, which could reduce your overall savings potential.
Investment choices within 529 accounts can also be more limited compared to other options, making it challenging for families to diversify their portfolios. As an alternative, Coverdell Education Savings Accounts (ESAs) provide greater flexibility in investment choices and can be used for K-12 expenses as well as college costs. Custodial accounts are another option, allowing for broader use of funds, though they might not offer the same tax advantages as 529 plans.
As you explore these alternatives, it’s important to weigh the pros and cons of each option against your unique financial situation and educational goals. Imagine if a Coverdell ESA aligns better with your investment strategy, especially if you anticipate needing funds for K-12 tuition. Working with a financial advisor, like those at Bright Advisers who focus on low fund fees, can help you navigate these options efficiently, ensuring you choose the best savings approach for your children’s education.
Significantly, families that start saving early in a 529 account report much higher savings. On average, parents save about $18,135 for their child’s college education. Plus, starting in 2024, families will have the option to roll over unused funds into a Roth IRA without incurring taxes or penalties, as 529 plans are tax deferred, providing even more flexibility in managing educational savings. Together, we can navigate this journey and make informed decisions for your family’s future.
Conclusion
The significance of 529 plans, especially their tax-deferred nature, is truly important for families planning for educational expenses. These savings vehicles not only provide a structured way to save but also allow families to grow their investments without the immediate burden of taxation. This ultimately makes higher education more accessible and affordable for our children.
Throughout this discussion, we’ve explored the many advantages of 529 plans. These include:
- Tax-deferred growth
- Tax-free withdrawals for qualified expenses
These advantages can lead to significant financial gains over time. It’s also vital to recognize the limitations of these plans and to consider alternatives, ensuring that families can make informed decisions that fit their unique financial situations and educational dreams.
Given the rising costs of education, leveraging the benefits of 529 plans is more crucial than ever. Imagine starting to save early and exploring the various options available, including potential rollovers to Roth IRAs. By taking proactive steps today, families can secure a brighter educational future for their children while optimizing their financial health.
Together, we can navigate this journey towards financial security and educational success. Remember, we’re here for you, supporting you every step of the way.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a tax-advantaged savings vehicle designed to help families save for future education expenses, established under Section 529 of the Internal Revenue Code.
What are the two main types of 529 plans?
The two main types of 529 plans are college savings accounts and prepaid tuition plans.
What can 529 plans be used for?
529 plans can be used for a range of eligible academic expenses, including tuition, fees, and room and board.
How do college savings programs differ from prepaid tuition plans?
College savings programs allow families to save for various educational expenses, while prepaid tuition plans enable families to secure current tuition rates for future educational purposes, protecting against rising costs.
What is the main goal of 529 programs?
The main goal of 529 programs is to provide families with a systematic and effective way to save for their children’s education, making higher education more accessible and affordable.
How widespread are 529 plans in the United States?
As of 2025, all states except Wyoming provide 529 options, with around 17 million accounts across the country being utilized by families.
What are the tax advantages of 529 plans?
529 plans offer tax-deferred growth, which means that the funds in the accounts can grow without being taxed until they are withdrawn for qualified education expenses.
How do financial advisors view 529 plans?
Financial advisors emphasize the tax advantages of 529 plans and encourage disciplined saving, viewing them as a vital part of a holistic financial approach for families focused on education.
List of Sources
- Define 529 Plans and Their Purpose
- Release: 529 Plan Program Statistics, December 2024 (https://ici.org/research/stats/529s/529s_24_q4)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- FRB: FEDS Notes: Saving for College and Section 529 Plans (https://federalreserve.gov/econresdata/notes/feds-notes/2016/saving-for-college-and-section-529-plans-20160203.html)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Examine Tax Advantages of 529 Plans
- Saving for College in the Shenandoah Valley: Is a 529 Plan Right for Your Family? – F&M Bank (https://fmbankva.com/is-a-529-right-for-you)
- Saving for K-12 education with a 529 plan (https://raymondjames.com/palmdesert-branch/commentary-and-insights/2025/07/07/saving-for-k12-education-with-a-529-plan)
- 529 Plan: What It Is, How It Works, Pros and Cons (https://investopedia.com/terms/1/529plan.asp)
- PA 529 College and Career Savings Program (https://pa529.com/invest)
- Unravelling Education Savings: Mastering 529 Plans to Maximize Tax Benefits – Brown Graham & Company, P.C. (https://bgc-cpa.com/unravelling-education-savings-mastering-529-plans-to-maximize-tax-benefits)
- Analyze Financial Implications of Tax Deferral
- Why 529 plans are worth it for saving for college (https://cnbc.com/select/how-529-college-plans-become-more-valuable)
- 529 Plan Pros and Cons (https://actec.org/resource-center/video/529-plan-pros-and-cons-529-plan-faqs-educational-savings-plans)
- 529 Plans, Roth Conversions, and Avoiding Too Much of a Good Thing | Yellow Cardinal Advisory Group (https://bankatfirst.com/personal/discover/flourish/529-plans-roth-conversions.html)
- The unique benefits of 529 college savings plans (https://thetaxadviser.com/issues/2023/may/the-unique-benefits-of-529-college-savings-plans)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Consider Limitations and Alternatives to 529 Plans
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 7 Key Insights on 529 Plan Superfunding for Young Parents – Bright Advisers (https://brightadvisers.com/7-key-insights-on-529-plan-superfunding-for-young-parents)
- The new rules that have money rolling into 529 accounts | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/529-to-roth-ira-rules)
- 529 plan contribution limits for 2025: What college savers need to know (https://finance.yahoo.com/news/529-plan-contribution-limits-2024-000036093.html)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading