

Key Highlights:
- Wirehouses are large, full-service firms offering various financial solutions, operating under a centralised structure with employed advisors.
- Broker-dealers assist in buying and selling securities, can operate independently, and may not adhere to fiduciary standards, leading to potential conflicts of interest.
- By 2025, wirehouses are projected to control 27.7% of industry assets, down from over 50% in 2005, indicating a shift towards independent advisory models.
- Wirehouses provide a wide range of services but may limit personalization due to standardised offerings, while broker-dealers offer more flexibility but with variable quality.
- Wirehouses typically charge a percentage of assets under management, which can be costly for families with smaller portfolios, whereas broker-dealers have diverse fee structures that may reduce expenses.
- The trend in the advisory landscape is moving towards greater transparency, with a significant increase in fee-based revenue expected by 2026.
- Wirehouses assign advisors based on client needs, which can lead to transactional relationships, while broker-dealers often provide a more personalised experience, though quality can vary.
Introduction
Navigating the financial landscape can feel overwhelming, especially for young families eager to secure their future. Imagine facing the ongoing debate between wirehouses and broker-dealers – this is a pivotal moment for families to explore their financial management options.
Wirehouses provide a comprehensive suite of services under one roof, offering a sense of security. On the other hand, broker-dealers present a more flexible approach, tailoring their services to meet individual needs. As families weigh these choices, it’s important to ask: which financial service provider truly resonates with your values and goals in this ever-changing market?
We understand that making these decisions can be daunting. But remember, you’re not alone in this journey. Together, we can navigate the complexities of financial planning, ensuring that your family’s priorities are at the forefront.
Let’s explore how these options can align with your family’s aspirations. With the right support, you can confidently take steps toward a brighter financial future.
Define Wirehouses and Broker-Dealers in Financial Services
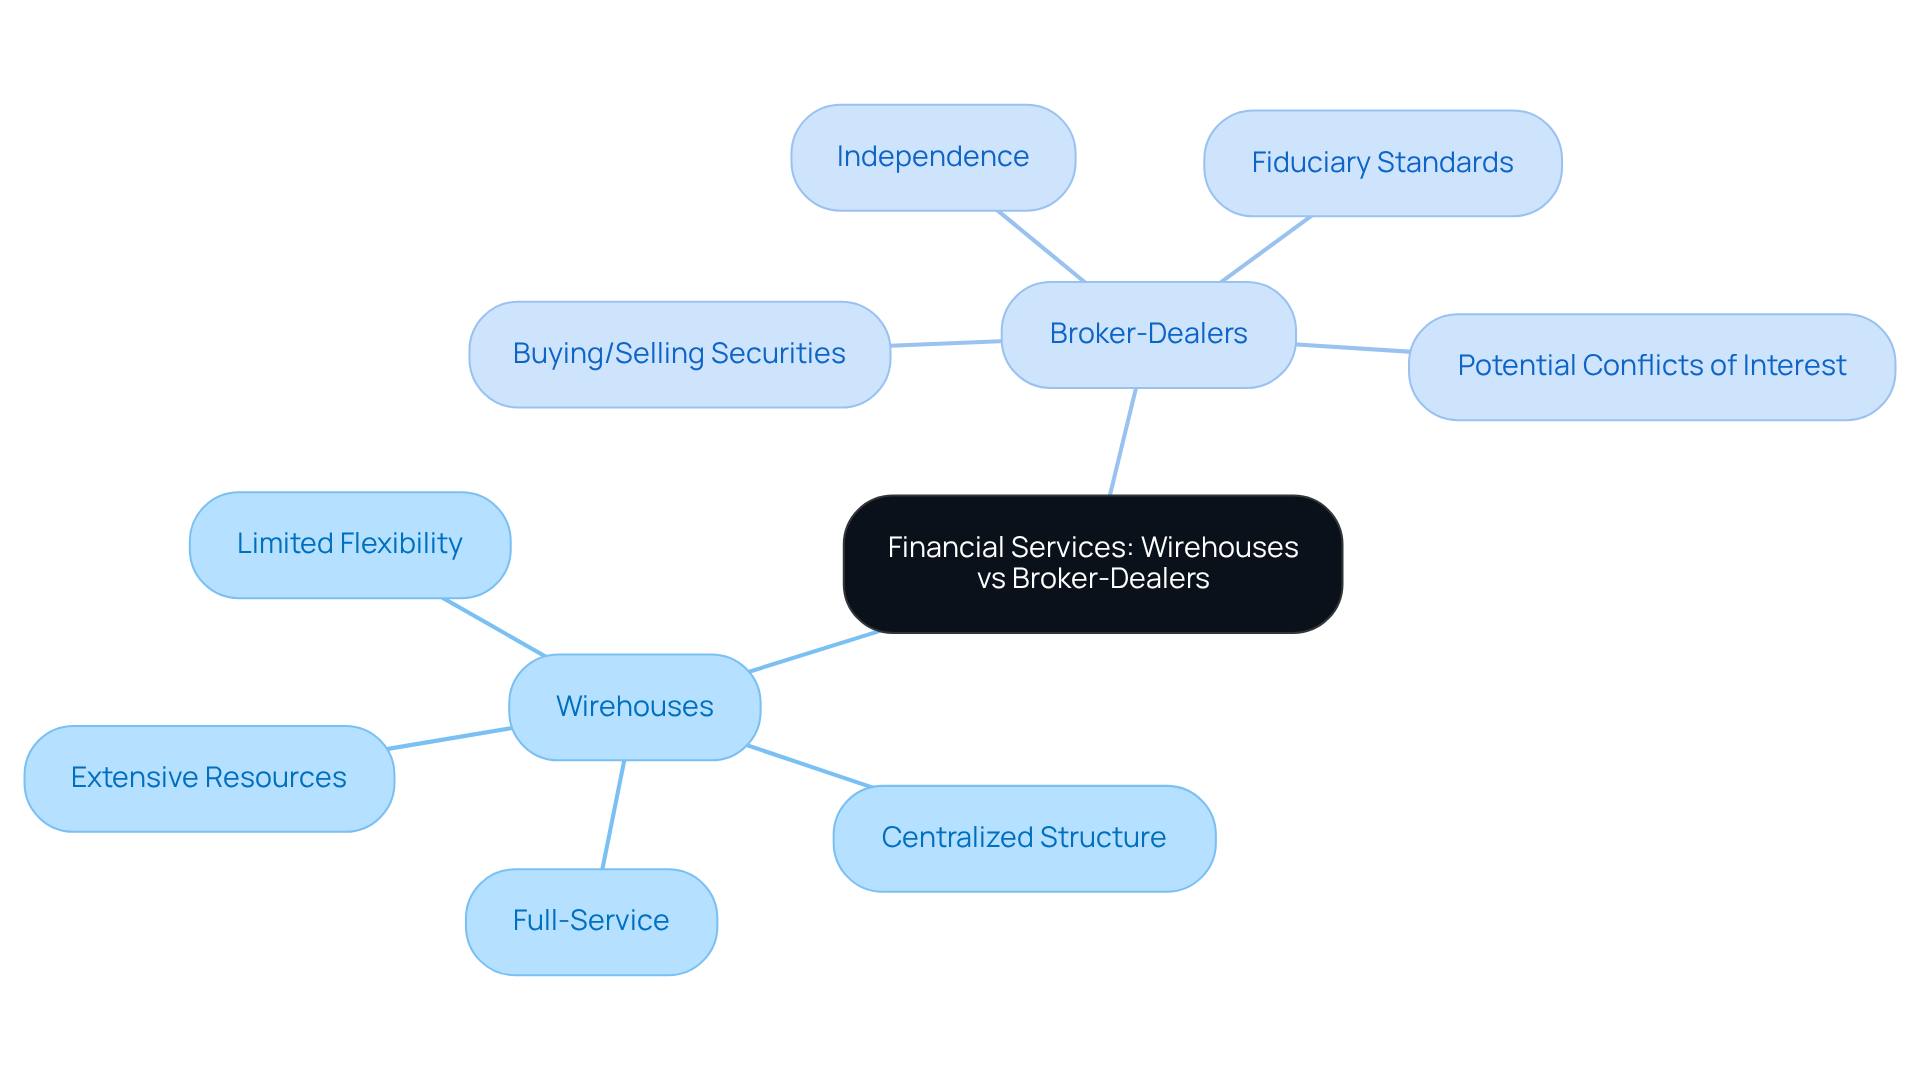
When it comes to managing your family’s finances, understanding the landscape of is crucial. The comparison of [wirehouse vs broker dealer](https://thinkadvisor.com/2025/02/07/5-factors-driving-advisors-out-of-wirehouses) highlights that wirehouses, being large, full-service firms, offer a variety of [monetary solutions](https://brightadvisers.com/?p=10972) like [investment guidance](https://brightadvisers.com/?p=10998), [retirement planning](https://brightadvisers.com/?p=11125), and wealth management. They operate under a centralized structure, employing advisors as firm employees. This setup provides extensive resources and support, but it can sometimes limit the flexibility of services tailored to your unique needs.
On the other hand, when considering wirehouse vs broker dealer, broker-dealers-whether firms or individuals-assist in buying and selling securities for customers or their own accounts. They can work independently or as part of a larger organization. Unlike wirehouse vs broker dealer, broker-dealers may not always follow fiduciary standards, meaning they aren’t legally required to act in your best interests. This lack of obligation can lead to conflicts of interest, making it essential for families to carefully consider which type of provider aligns with their values and needs.
Looking ahead to 2025, wirehouses are expected to control about 27.7% of industry assets, a notable drop from over 50% in 2005. Meanwhile, independent broker-dealers are seeing modest growth. This shift highlights the evolving landscape of financial solutions, where families must explore their options to find the best fit for their financial goals.
Imagine having a comprehensive wealth management solution that not only integrates investment strategies but also considers estate and tax planning. This holistic approach can provide your family with the financial security you deserve. We’re here for you, ready to help you navigate this journey and ensure your family’s financial future is bright.
Compare Operational Structures and Service Offerings
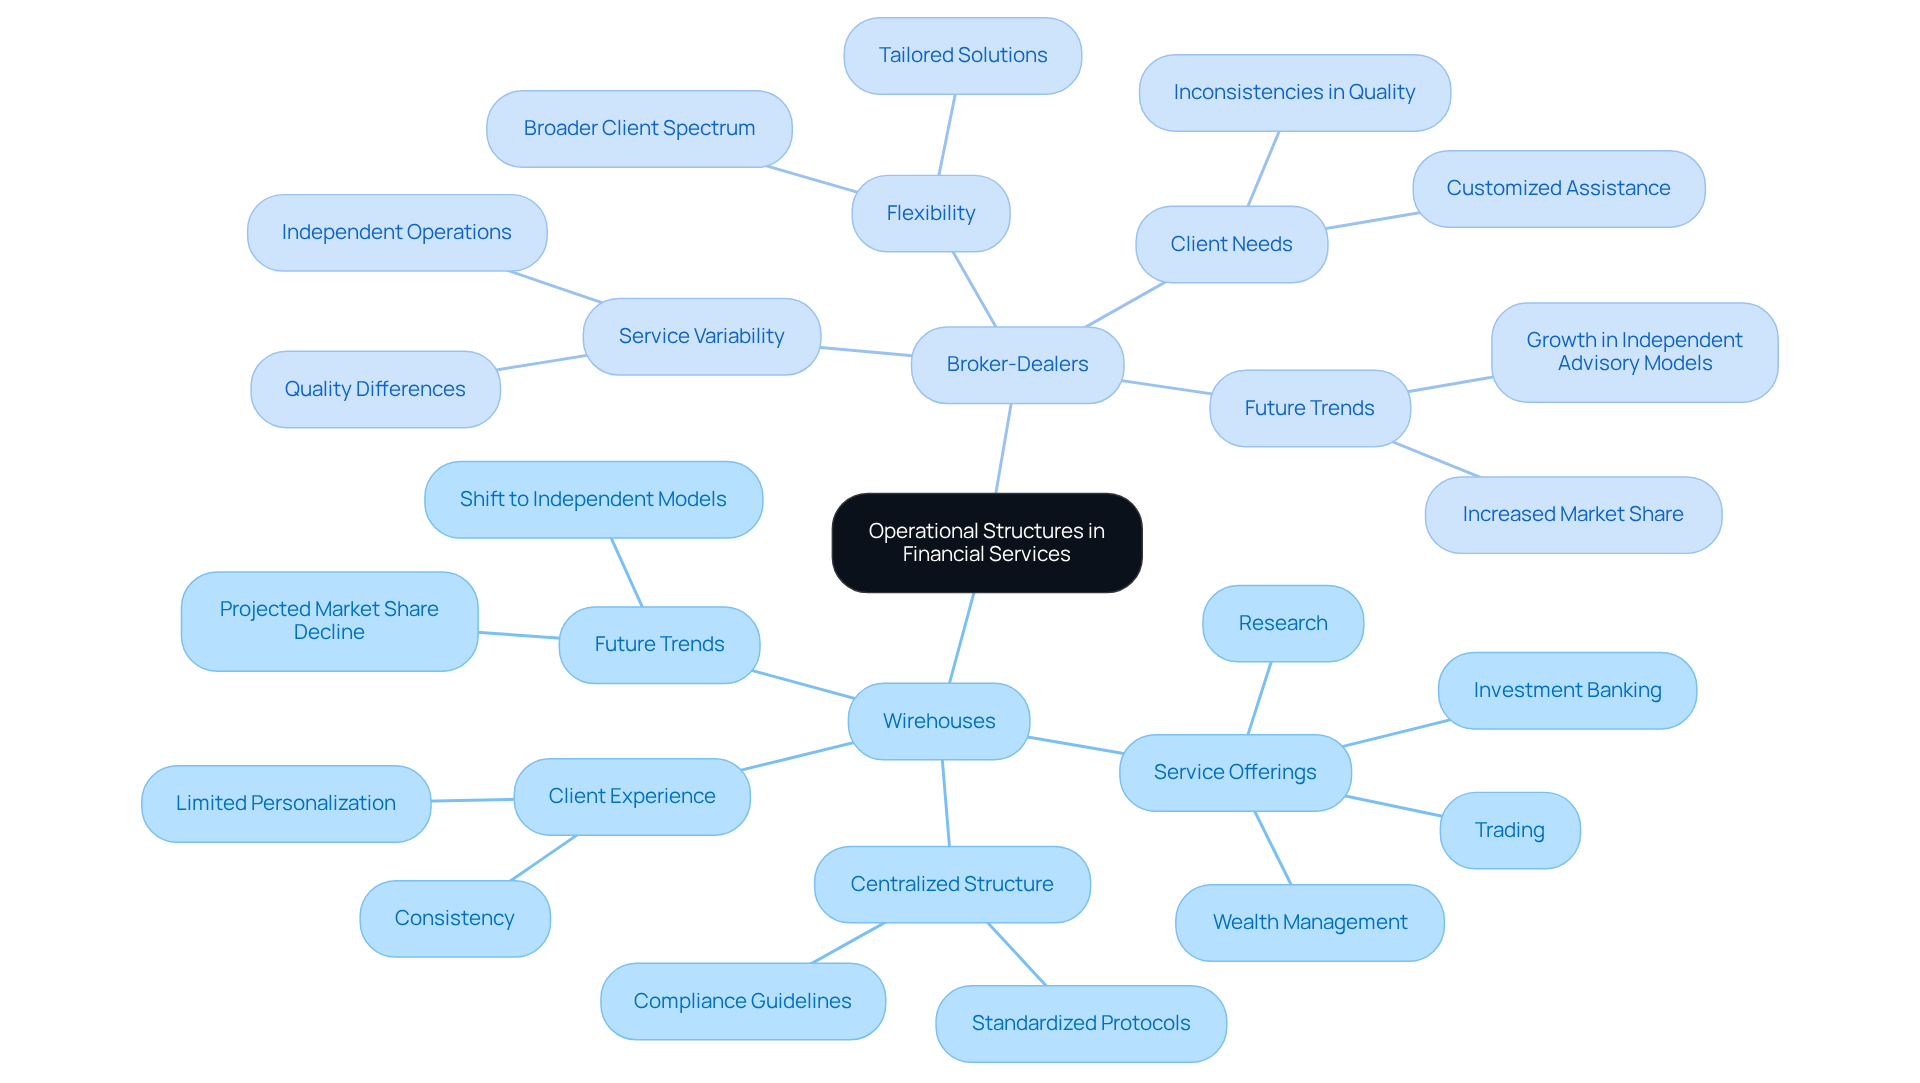
In the context of financial services, the discussion of [wirehouse vs broker dealer](https://investopedia.com/articles/active-trading/082715/independent-brokerdealers-what-you-should-know.asp) highlights how wirehouses stand out with their wide range of offerings, including investment banking, research, trading, and comprehensive wealth management. This centralized structure means that all advisors follow the same protocols and compliance guidelines. While this consistency can enhance your experience as a client, it might also limit personalization, as the focus often leans towards standardized services.
On the other hand, in the discussion of wirehouse vs broker dealer, it is evident that broker-dealers provide a more flexible approach, catering to a broader spectrum of client needs – from basic trading options to more complex investment strategies. However, the quality of assistance can vary significantly among broker-dealers. Many operate independently and may not have the extensive resources that larger wirehouses possess. For young families, this variability is crucial; while broker-dealers can offer tailored solutions, the thoroughness and quality of these solutions can differ widely. It’s essential for families to weigh the benefits of customized assistance against the potential inconsistencies in quality.
Looking ahead, statistics show that [by 2027, wirehouses are expected to control only 27.7% of industry assets](https://fa-mag.com/news/finra-continues-to-lose-wirehouse-members-83225.html), a significant drop from over 50% in 2005. This shift highlights the growing importance of independent advisory models. As you navigate your financial choices, it’s vital to assess the operational frameworks and service offerings in the context of wirehouse vs broker dealer. This way, you can make informed decisions that align with your family’s values and goals.
Remember, we’re here for you. Together, we can navigate this journey and find the right .
Evaluate Fee Structures and Transparency
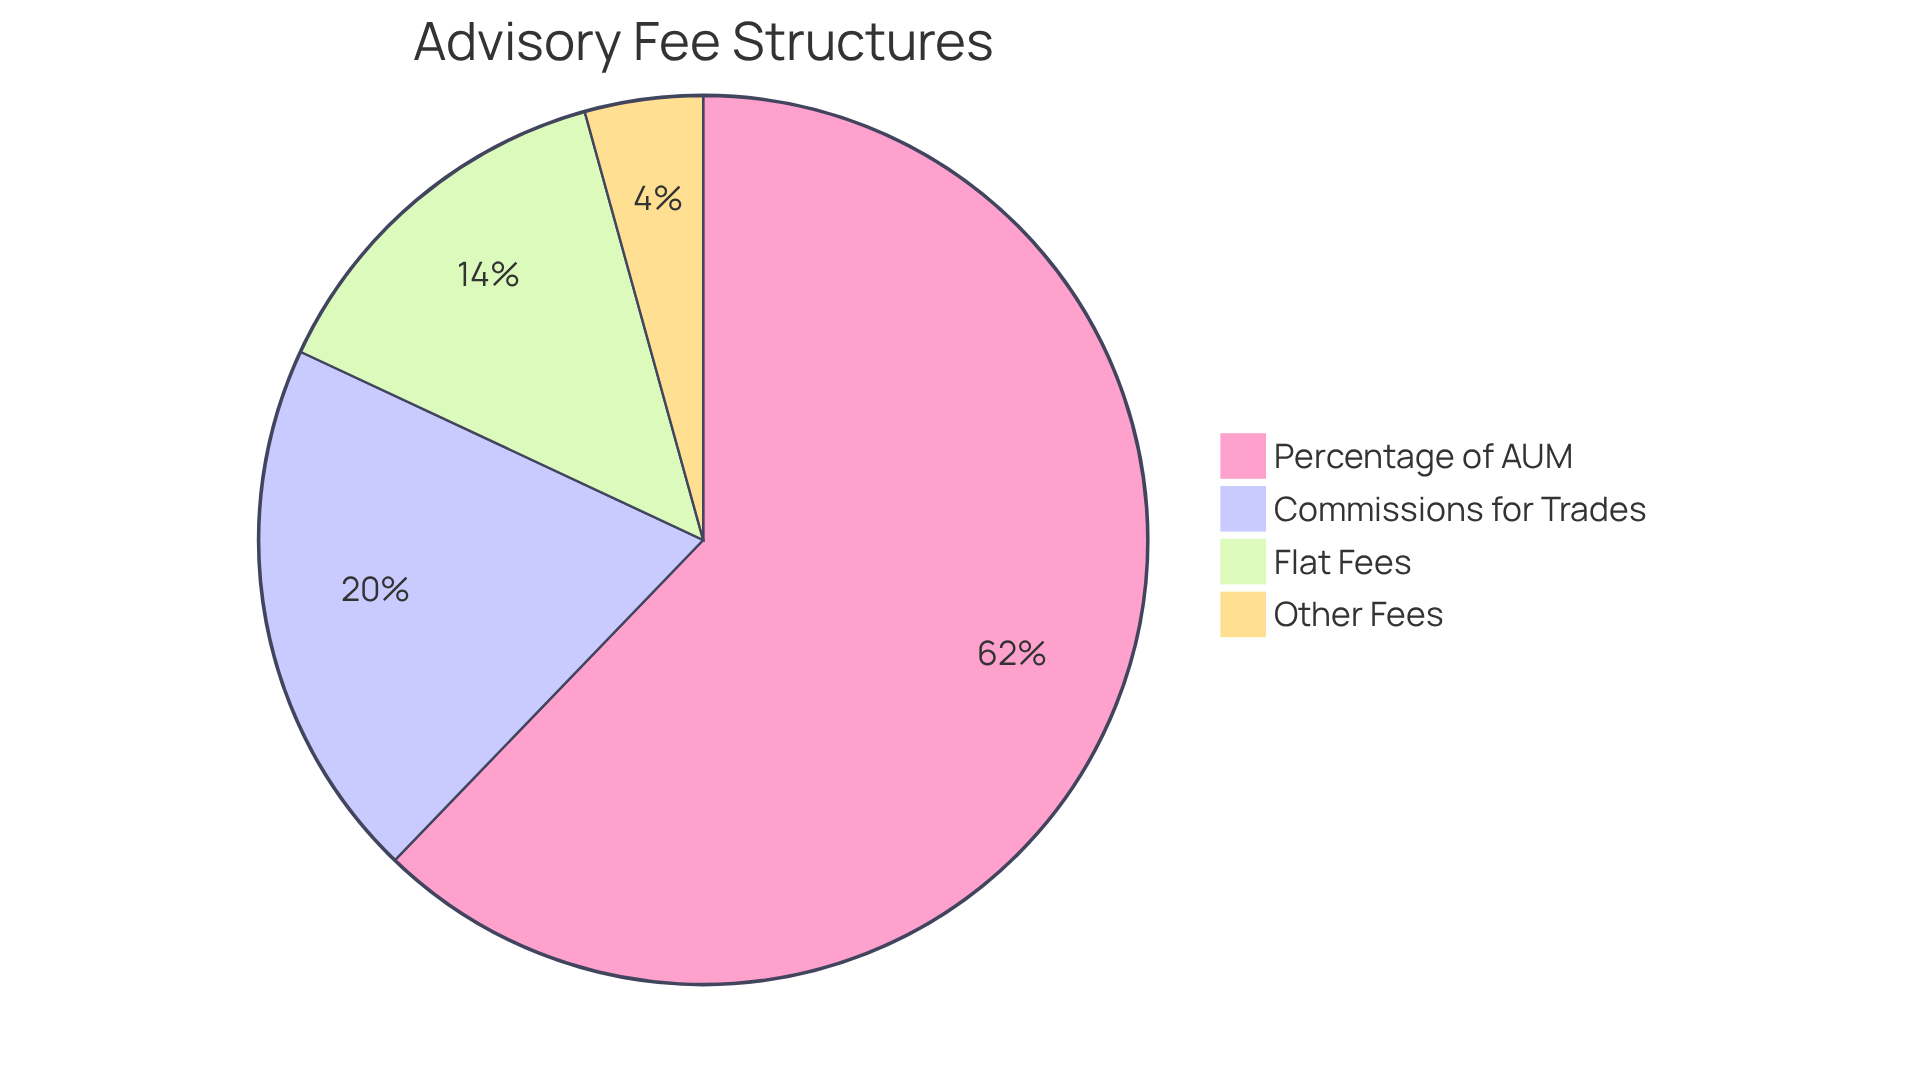
Navigating the world of [financial services](https://brightadvisers.com/comparing-wealth-management-advisory-firms-for-young-families) can feel overwhelming, especially for young families. Imagine if you could find a partner who truly understands your needs and priorities. When comparing wirehouse vs broker dealer, it’s important to note that wirehouses often charge clients a percentage of assets under management (AUM), which can lead to [higher costs](https://wealthsolutionsreport.com/cerulli-almost-78-of-industry-on-fee-based-model-by-2026), particularly for families with smaller portfolios. While they defend these fees by offering a wide range of services, including [exclusive investment products](https://brightadvisers.com/?p=13801) and extensive research resources, it’s essential to consider whether these benefits .
On the flip side, when considering wirehouse vs broker dealer, broker-dealers provide a variety of [fee structures](https://brightadvisers.com/understand-investment-fee-structures-to-maximize-savings), including commissions for trades and flat fees for advisory services. This flexibility can help reduce overall expenses, especially for those who trade frequently. However, without a [fiduciary standard](https://brightadvisers.com/?p=10979) in many broker-dealer arrangements, potential conflicts of interest can arise. It’s crucial for families to carefully examine the fee structures of both wirehouse vs broker dealer options to ensure they’re making informed decisions.
At Bright Advisers, we prioritize your family’s [financial well-being](https://brightadvisers.com/understanding-the-cost-of-financial-planning-for-young-families) by keeping fund fees to a minimum. While some clients may still hold legacy fee-bearing mutual funds and ETFs, we actively support clients in [transitioning to low-fee ETFs](https://connectmoney.com/stories/nearly-78-of-advisors-to-shift-toward-fee-based-services-by-2026), particularly for fixed income and alternative asset classes like precious metals and cryptocurrencies. As we look ahead to 2025, the advisory landscape is shifting towards greater transparency. In fact, 87% of advisors report that at least half of their revenue is fee-based, a figure expected to rise to 97% by 2026. This trend underscores the importance of clear communication about expenses, ensuring that your chosen financial service aligns with your family’s budget and objectives.
Assessing these fee structures is vital for families aiming to make informed choices in their budgeting. Remember, we’re here for you, ready to help you navigate this journey together.
Assess Client Relationships and Support
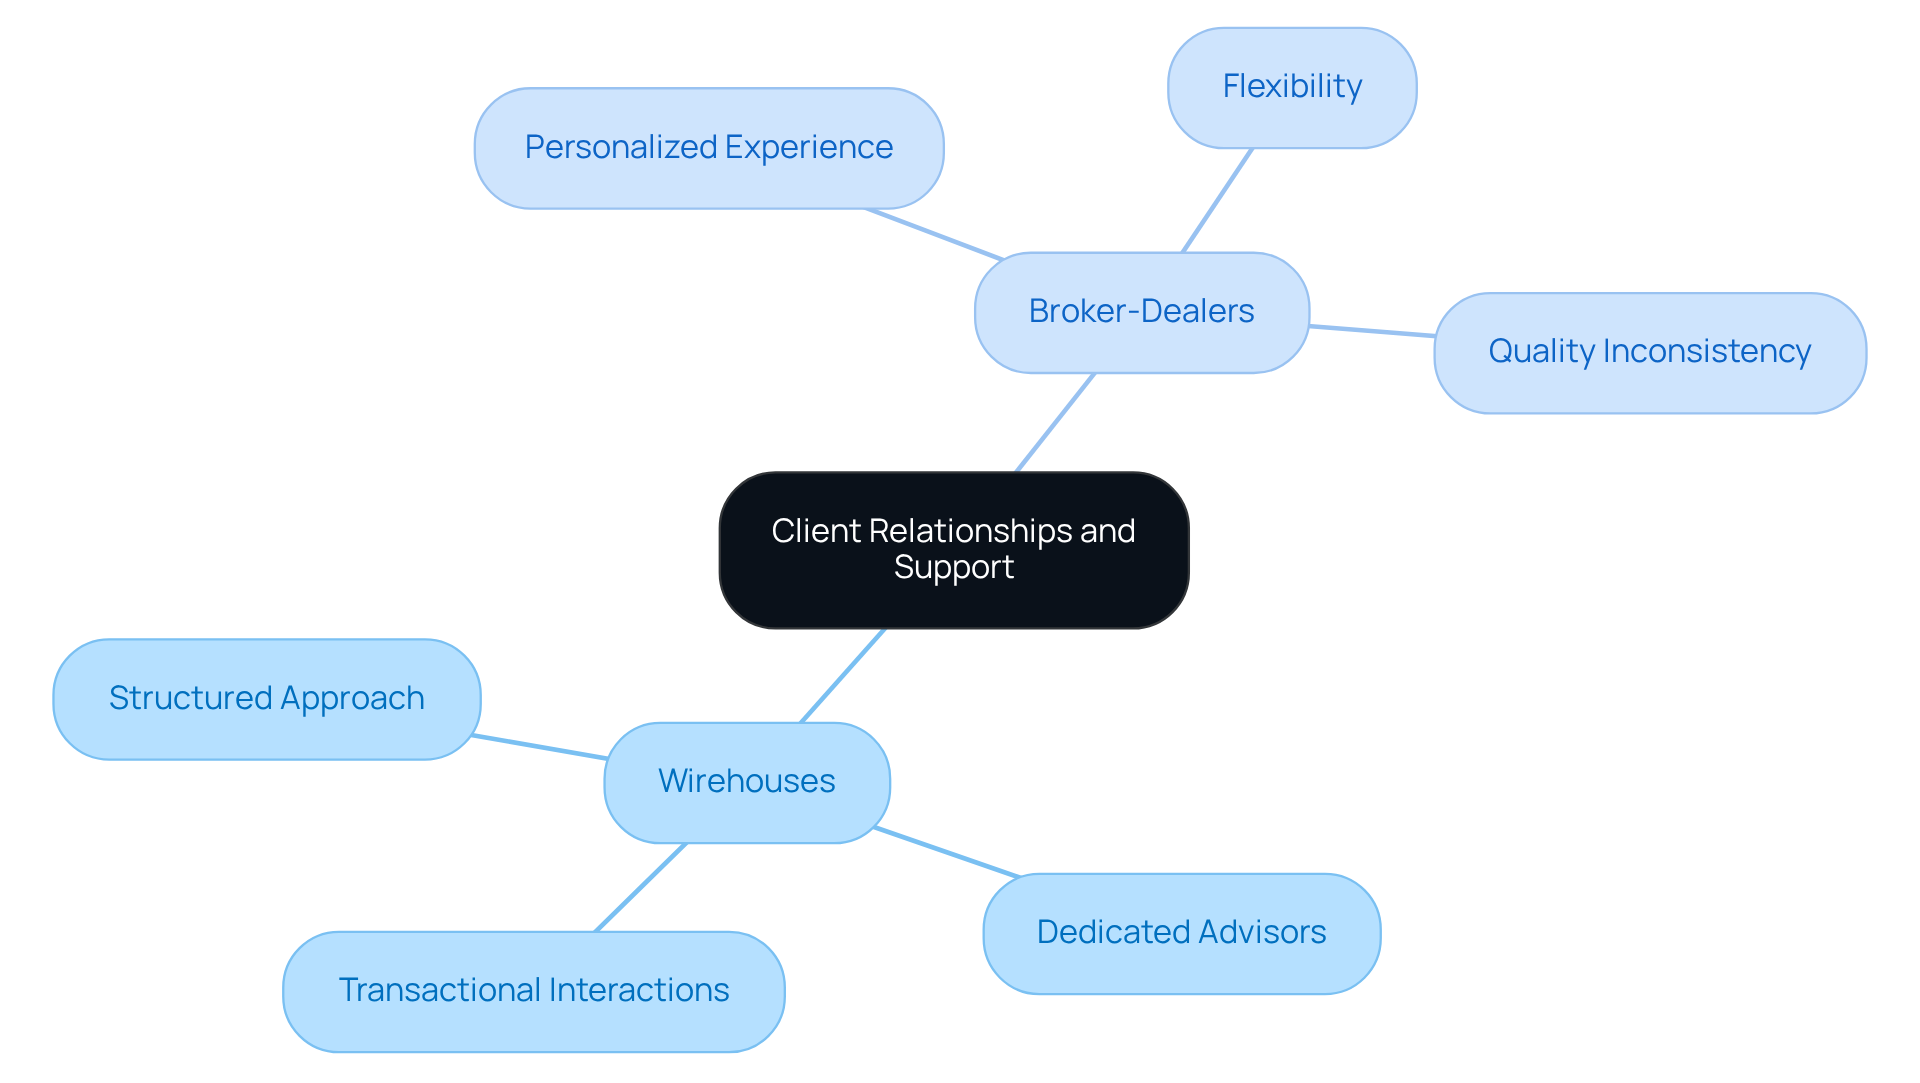
The comparison of wirehouse vs broker dealer often shows that wirehouses take a structured approach to customer relationships by assigning advisors to specific individuals based on their needs and the firm’s resources. This model can provide a sense of security for families, as they have a dedicated advisor to help them [navigate their financial journey](https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management). However, the centralized nature of wirehouses might lead to more transactional interactions, where the focus is on meeting sales targets rather than nurturing long-term partnerships.
Imagine if you could have a more personalized experience. In the discussion of wirehouse vs broker dealer, it is evident that [broker-dealers frequently offer](https://aldeninvestmentgroup.com/blog/why-financial-advisors-are-leaving-their-wirehouses-to-be-rias) just that, as many operate independently and can adapt their services to fit unique customer requirements. This flexibility enhances the experience for families, allowing them to build stronger bonds with their advisors. Yet, it’s important to understand that the among broker-dealers means families need to do their homework to find a provider that aligns with their values and expectations.
The significance of [strong client support](https://cerulli.com/press-releases/wirehouses-lead-advisor-productivity-rates-among-all-broker-dealer-channels) in [financial services](https://brightadvisers.com/essential-tax-planning-strategies-for-young-families-financial-health) cannot be overstated, especially for young families looking to secure their economic futures. A supportive advisor relationship can profoundly impact a family’s ability to make informed decisions and achieve their [financial goals](https://brightadvisers.com/10-essential-steps-for-family-financial-planning-success). Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized.
Conclusion
Understanding the differences between wirehouses and broker-dealers is crucial for young families as they navigate their financial futures. Imagine having a partner who truly understands your needs. Wirehouses, with their comprehensive service offerings and centralized structures, provide a solid framework for wealth management. However, they may not always offer the tailored flexibility that some families require.
On the other hand, broker-dealers present a more adaptable approach, catering to diverse client needs. Yet, it’s important to be aware of potential inconsistencies in service quality and fiduciary obligations. As you consider your options, think about what matters most to your family.
Throughout this journey, key points emerge regarding the operational structures, fee transparency, and client relationships inherent in each model. Wirehouses are known for their extensive resources and standardized services, which can be beneficial for families seeking a reliable partner. Meanwhile, broker-dealers offer opportunities for personalized care and flexibility. Just remember, it’s essential to evaluate the quality of services to ensure your financial goals are met.
Ultimately, the choice between wirehouses and broker-dealers hinges on your family’s specific needs and values. As the financial landscape continues to evolve, staying proactive is key. Together, we can explore your options and find providers that align with your unique circumstances. Prioritizing transparency, personalized support, and a clear understanding of fee structures will empower you to make informed decisions that secure your family’s financial well-being for years to come. We’re here for you, ready to support you on this journey.
Frequently Asked Questions
What are wirehouses in financial services?
Wirehouses are large, full-service firms that offer a variety of financial solutions, including investment guidance, retirement planning, and wealth management. They operate under a centralized structure and employ advisors as firm employees.
What are broker-dealers?
Broker-dealers are firms or individuals that assist in buying and selling securities for customers or their own accounts. They can operate independently or as part of a larger organization.
How do wirehouses and broker-dealers differ in their service structure?
Wirehouses provide extensive resources and support with a centralized structure, while broker-dealers may not always follow fiduciary standards and can work independently, which may lead to potential conflicts of interest.
What are fiduciary standards, and how do they relate to broker-dealers?
Fiduciary standards require financial advisors to act in their clients’ best interests. Broker-dealers are not always legally obligated to follow these standards, which can create conflicts of interest.
What is the projected market share of wirehouses by 2025?
By 2025, wirehouses are expected to control about 27.7% of industry assets, a significant decrease from over 50% in 2005.
What trend is being observed with independent broker-dealers?
Independent broker-dealers are experiencing modest growth, indicating a shift in the financial services landscape.
How can a holistic wealth management solution benefit families?
A comprehensive wealth management solution integrates investment strategies with estate and tax planning, providing families with enhanced financial security and support for their financial goals.
List of Sources
- Define Wirehouses and Broker-Dealers in Financial Services
- Wirehouses lead alternatives adoption, RIAs face strategic crossroads (https://investmentnews.com/alternatives/wirehouses-lead-alternatives-adoption-rias-face-strategic-crossroads/262247)
- Why Advisors Are More Than Happy to Leave the Wirehouses (https://thinkadvisor.com/2025/02/07/5-factors-driving-advisors-out-of-wirehouses)
- What is the outlook for the US wealth management market? (https://hanoversearch.com/en-us/blog/what-is-the-outlook-for-us-wealth-management-market)
- Cerulli: Advisor Headcount Stagnates (https://wealthmanagement.com/insights-analysis/cerulli-advisor-headcount-stagnates)
- Finra Continues To Lose Wirehouse Members (https://fa-mag.com/news/finra-continues-to-lose-wirehouse-members-83225.html)
- Compare Operational Structures and Service Offerings
- Independent Broker-Dealers vs. Wirehouse: Pros, Cons, and Key Differences (https://investopedia.com/articles/active-trading/082715/independent-brokerdealers-what-you-should-know.asp)
- What is the outlook for the US wealth management market? (https://hanoversearch.com/en-us/blog/what-is-the-outlook-for-us-wealth-management-market)
- Finra Continues To Lose Wirehouse Members (https://fa-mag.com/news/finra-continues-to-lose-wirehouse-members-83225.html)
- Why Financial Advisors Are Leaving their Wirehouses to be RIAs (https://aldeninvestmentgroup.com/blog/why-financial-advisors-are-leaving-their-wirehouses-to-be-rias)
- Wirehouses are most productive channel: Cerulli (https://investmentnews.com/ria-news/wirehouses-are-most-productive-channel-cerulli/216913)
- Evaluate Fee Structures and Transparency
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Nearly 78% of Advisors to Shift Toward Fee-Based Services by 2026 (https://connectmoney.com/stories/nearly-78-of-advisors-to-shift-toward-fee-based-services-by-2026)
- Fee-Based Models Rise as Advisers Adapt to Client Needs | PLANADVISER (https://planadviser.com/fee-based-models-dominate-advisers-respond-shifting-client-expectations)
- Cerulli: Almost 78% Of Industry On Fee-Based Model By 2026 (https://wealthsolutionsreport.com/cerulli-almost-78-of-industry-on-fee-based-model-by-2026)
- More than three-quarters of advisors to embrace fee models by 2026, Cerulli says (https://investmentnews.com/practice-management/more-than-three-quarters-of-advisors-to-embrace-fee-models-by-2026-cerulli-says/259740)
- Assess Client Relationships and Support
- Press Release – Wirehouses Lead Advisor Productivity Rates Among All… (https://cerulli.com/press-releases/wirehouses-lead-advisor-productivity-rates-among-all-broker-dealer-channels)
- Why Financial Advisors Are Leaving their Wirehouses to be RIAs (https://aldeninvestmentgroup.com/blog/why-financial-advisors-are-leaving-their-wirehouses-to-be-rias)
- Online Brokerages Still Grabbing Market Share From Wirehouses (https://wealthmanagement.com/business-planning/online-brokerages-still-grabbing-market-share-from-wirehouses)
- Are Advisors Communicating Enough with Their Clients? (https://nasdaq.com/articles/are-advisors-communicating-enough-with-their-clients)
- The looming advisor shortage in US wealth management (https://mckinsey.com/industries/financial-services/our-insights/the-looming-advisor-shortage-in-us-wealth-management)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading